
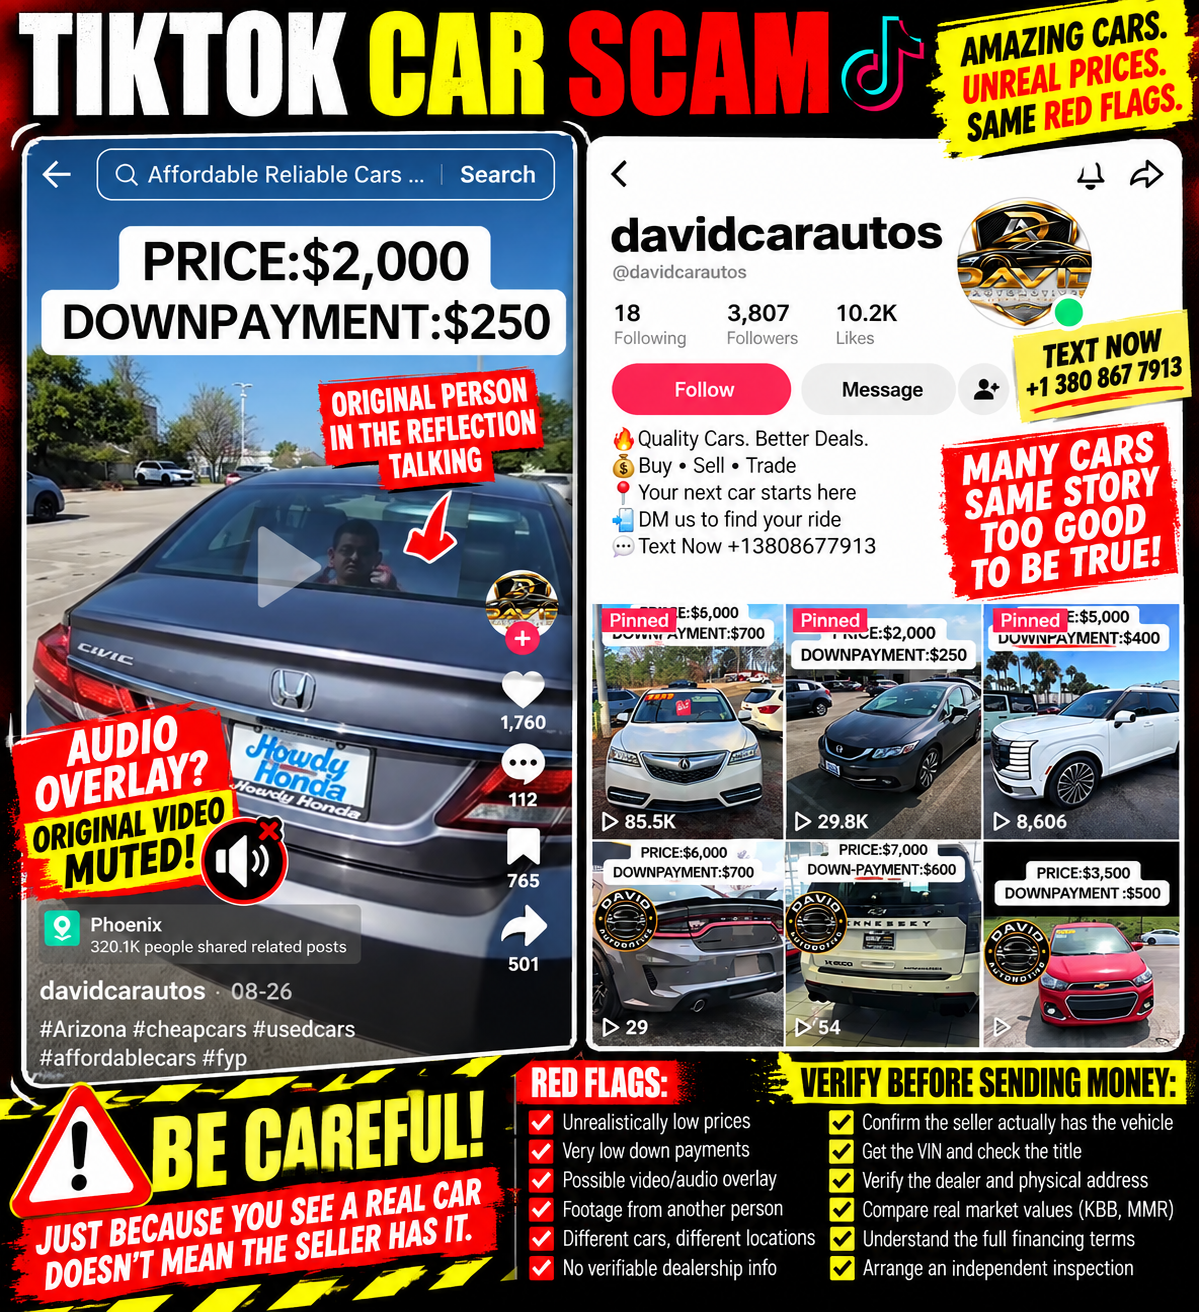
Another TikTok Car Deal — But Who Actually Has the Car?
At this point, TikTok may know my viewing habits a little too well.
Another extremely inexpensive vehicle landed in my feed. This time, it's from an account called davidcarautos, and the featured vehicle looks like a Honda Civic.
The advertisement couldn't be much simpler:
PRICE: $2,000
DOWN PAYMENT: $250
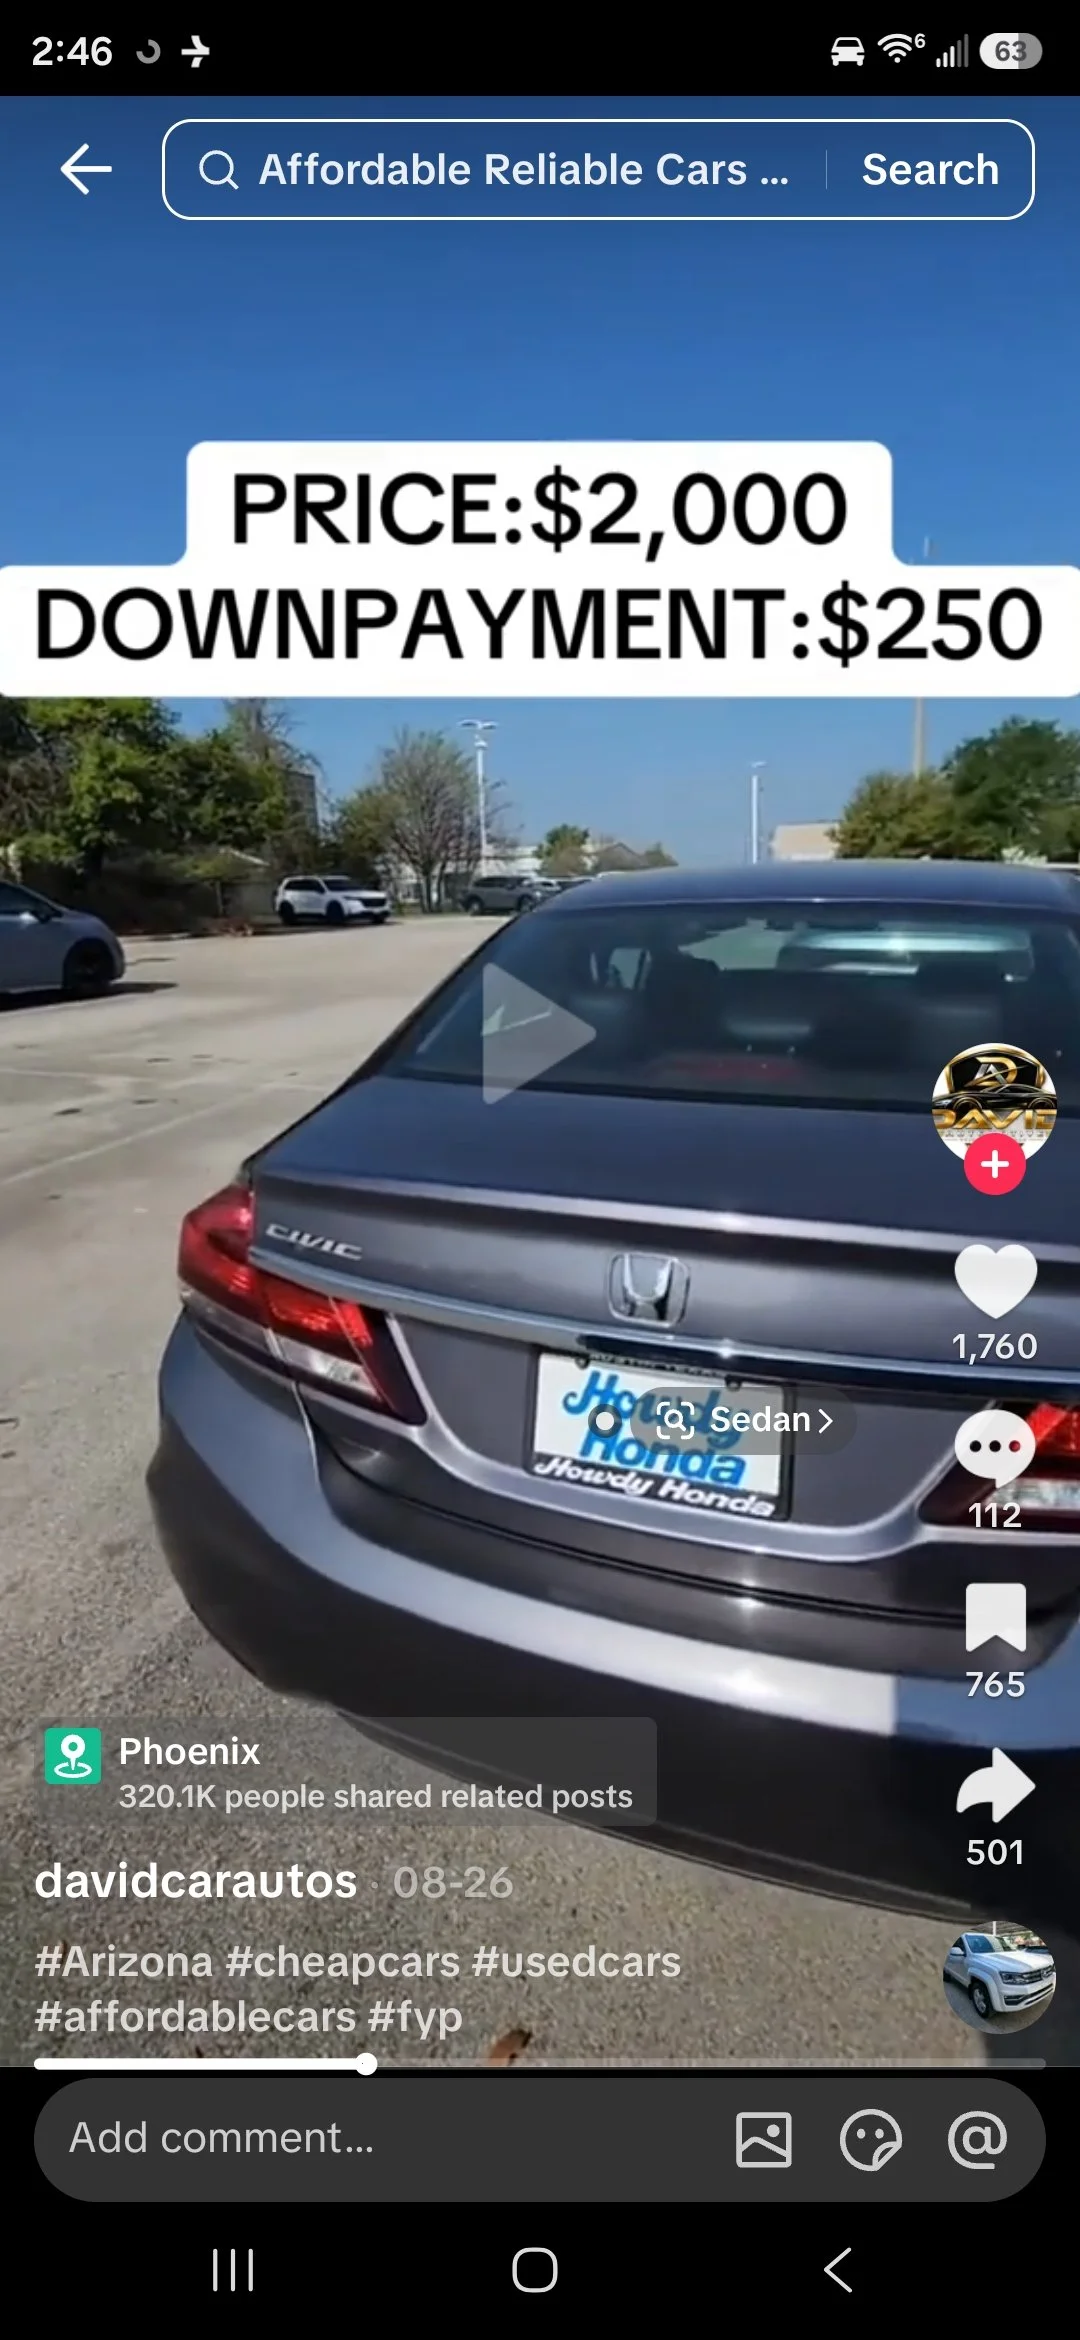
Two thousand dollars for the car, and apparently I can get started for $250.
But this video caught my attention for a reason beyond the price.
Wait—Whose Video Am I Watching?
I watched the video instead of just looking at the price.
That's when something looked odd.
The video appears to have been overlaid with new audio while the original video's audio is muted. As the camera moves around the Honda, I can see what appears to be the original person recording or speaking reflected in the car's window.
Meanwhile, the narration I'm hearing doesn't seem to match what's happening in the original footage.
The new narration makes a particularly interesting pitch: you don't have to go to a dealership to purchase a car.
That's supposed to make the transaction sound easier.
To me, it raises the opposite question:
Does the person posting this TikTok actually possess this car?
I can't establish from these screenshots alone who originally recorded the video or whether the TikTok account has permission to use it. So I'm not going to claim I've proven the footage was stolen.
But an apparently repurposed video combined with a new sales narration is absolutely something I would investigate before sending $250 to anybody.
🚗 A Real Honda in a Video Doesn't Prove the Seller Owns It
This is becoming one of the recurring lessons in my TikTok car series:
A real car doesn't automatically make the offer real.
That's especially important here.
The Honda clearly exists.
A license-plate frame is visible that appears to say Howdy Honda. There's a parking lot. A person is reflected in the vehicle.
All of that makes the video look authentic.
But those things establish the existence of a car and a video.
They don't establish that @davidcarautos owns the car, possesses the car, represents the owner, or has authority to sell it for $2,000.
That's a huge distinction.
The FTC issued a consumer warning this month specifically about scammers impersonating dealerships. It says scammers can copy legitimate dealerships' branding, vehicle listings, and photos, then collect money for cars the supposed seller doesn't actually have. The FTC recommends independently verifying the dealership and, when you can't visit the vehicle yourself, arranging an independent inspection. Consumer Advice
The FBI has also warned about fraudulent online vehicle advertisements involving cars that aren't—and sometimes never were—in the advertiser's possession. Internet Crime Complaint Center
That's why this video's altered presentation matters to me.
“You Don't Have to Go to a Dealer”
Technically, that's true.
People legitimately purchase vehicles remotely every day.
Dealerships deliver cars. Buyers purchase vehicles from other states. Documents can be signed electronically. Independent inspections can be arranged.
Remote car buying isn't inherently suspicious.
But there's a big difference between:
“You don't have to physically visit our dealership.”
and:
“You don't need to independently establish that we actually have the car.”
That second part is non-negotiable for me.
If someone wants my money for a vehicle, I want to know exactly where that vehicle is sitting.
👀 Then I Looked at the Profile
The account had approximately:
3,807 followers
10,200 likes
Its bio says:
🔥 Quality Cars. Better Deals.
💰 Buy • Sell • Trade
📍 Your next car starts here
➡️ DM us to find your ride
💬 Text Now +1 380-867-7913
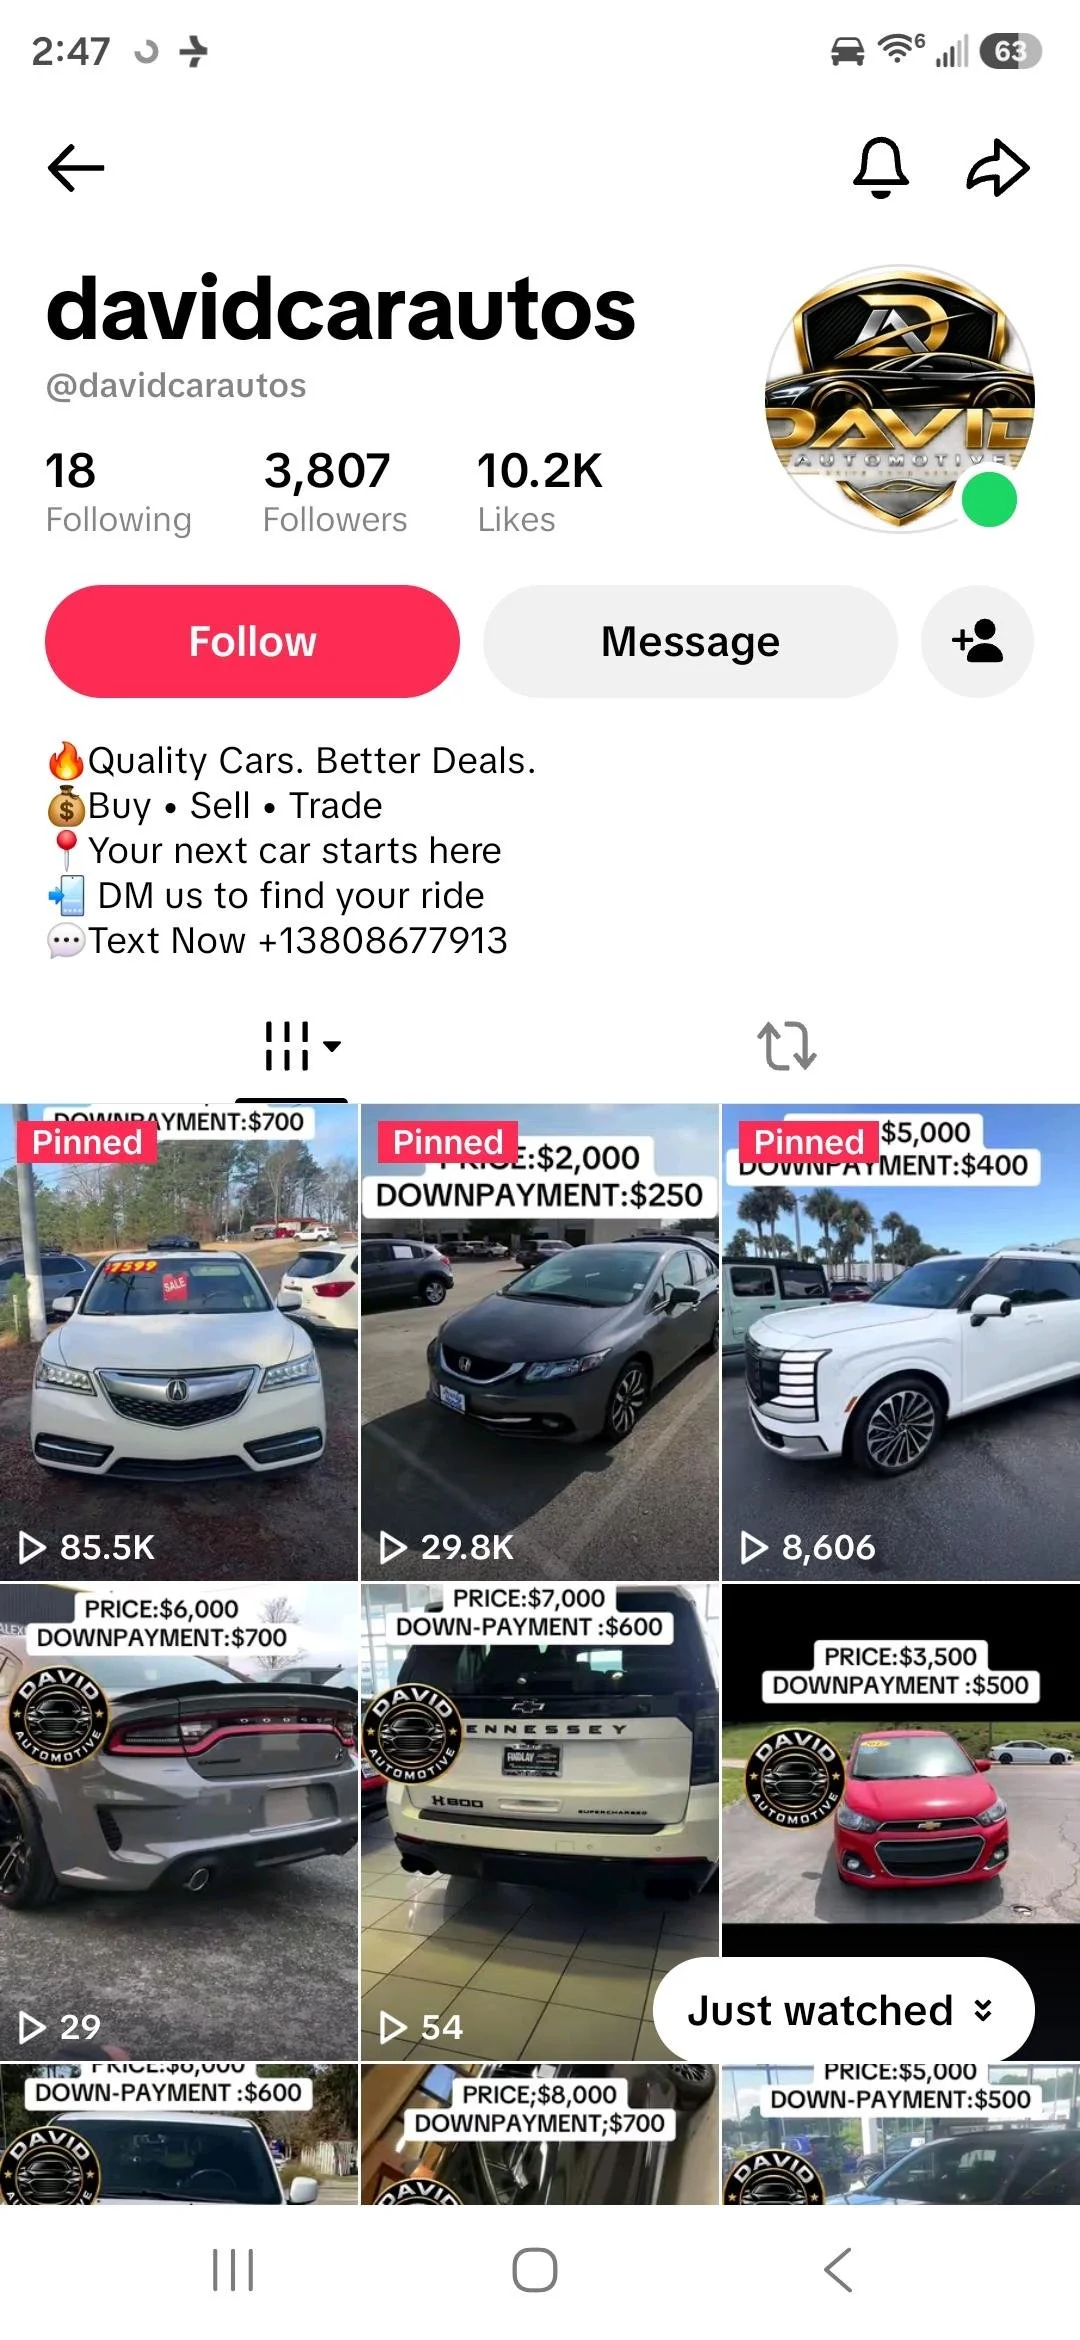
Then I looked at the inventory.
Here we go again.
The Honda is advertised for:
$2,000 — $250 down
Another vehicle:
$5,000 — $400 down
A Dodge:
$6,000 — $700 down
A Chevrolet Hennessey vehicle:
$7,000 — $600 down
Another:
$3,500 — $500 down
And more vehicles appear farther down the page with similarly low asking prices and down payments.
Different cars.
Different backgrounds.
Different dealerships appearing in some of the footage.
Same account selling all of them.
That doesn't prove anything by itself.
It does make one question increasingly important:
Where are these cars actually located?
📍 The Honda Video Says Phoenix
The TikTok interface on the Honda video displays Phoenix, and the hashtags include:
#Arizona #cheapcars #usedcars #affordablecars
Meanwhile, the visible dealership plate frame appears to identify a Honda dealership.
So before sending $250, I'd want to independently identify that dealership and call it using the telephone number from its own official website, not a number supplied by the TikTok account.
Then I'd ask a remarkably simple question:
Do you have this Honda, and is @davidcarautos authorized to sell it?
That could clear up a lot very quickly.
💰 And What Does “$250 Down” Actually Mean?
We've seen this repeatedly.
A tiny down payment gets enormous visual emphasis.
$250 DOWN!
That number feels attainable.
But it tells me almost nothing about the financing.
If the vehicle's total price really is $2,000 and I'm putting $250 down, the remaining amount is $1,750 before taxes, fees, interest and other charges.
So give me the rest:
What's the APR?
What's the term?
What's the monthly payment?
Who's the lender?
What's the total amount financed?
What's the total of payments?
What fees are included?
What credit requirements apply?
Is $2,000 actually the cash purchase price, or is there another condition attached to receiving that price?
The FTC has long warned consumers that unusually low advertised prices, down payments and monthly payments can come with qualifications or additional terms that aren't obvious from the headline advertisement. Consumer Advice
The giant number gets my attention.
The contract gets my money.
I care much more about the second one.
🎥 The Video Overlay May Be the Most Interesting Part
This is what distinguishes this post from some of the others I've documented.
The video itself appears to contain evidence of two different presentations:
The original footage.
And the new narration selling the vehicle.
Maybe there's a perfectly legitimate explanation.
Maybe the account licenses videos from dealerships.
Maybe it's a broker.
Maybe it has agreements with multiple dealers.
Maybe the person who made the original footage is connected with this account.
All of those possibilities can exist.
But I shouldn't have to guess.
If you're asking me to send money, tell me:
Who recorded the original video?
Who currently owns the vehicle?
Where is it physically located?
What's the VIN?
What's the dealer's legal business name?
Can I call that business independently?
Can someone inspect the vehicle before I pay?
A legitimate transaction should survive those questions.
🚨 This Isn't a Hypothetical Type of Scam
The FTC's September 2026 warning describes consumers paying supposed online dealerships only to discover that the actual dealership has no record of the order or payment and no car waiting for them. The FTC says fraudulent sellers can clone legitimate dealership material, including vehicle listings and photos. Consumer Advice
This problem isn't limited to websites, either. FTC data released this year show that nearly 30% of people reporting a scam loss in 2025 said the scam began on social media, with reported losses totaling $2.1 billion. Federal Trade Commission
So seeing a real automobile in a TikTok video isn't where my verification process ends.
It's where it begins.
🏡 Be a Good Neighbor
Here's the person I worry about.
Someone desperately needs transportation.
Their credit isn't great.
They've been turned down elsewhere.
They see:
HONDA CIVIC
PRICE: $2,000
DOWN PAYMENT: $250
And then they hear:
You don't even have to go to the dealership.
Convenient.
Affordable.
Easy.
Exactly what they need.
That's when somebody needs to say:
“Before you send the $250, let's verify the car.”
Not ridicule them.
Not call them stupid.
Help them investigate.
Reverse-search screenshots from the video. Identify the dealership visible in the footage. Call that dealership independently. Ask for the VIN. Verify the title. Check the seller's dealer license. Compare the price with KBB and wholesale values. Arrange an independent inspection.
And most importantly:
Verify that the person asking for your money actually has the legal ability to sell you the car.
The FTC's current advice is similarly straightforward: if you're too far away to see an online vehicle yourself, ask to have a mobile inspection service examine it. If the seller won't allow that, consider walking away. Consumer Advice
The Cars Keep Changing. My Question Doesn't.
Different TikTok accounts.
Different prices.
Different down payments.
And now apparently repurposed-looking video accompanied by a new narration telling me I don't have to visit a dealership.
I don't necessarily need to visit the dealership.
But before anybody gets one dollar from me, I need something considerably more important:
Proof that you actually have the car you're trying to sell me.
Because if the seller doesn't possess the vehicle or have authority to sell it, I'm not purchasing a car remotely.
I'm just sending $250 to somebody on TikTok.
Questions or another suspicious car listing you'd like me to look at? Reach out by DM or email niel@nielflamm.com.
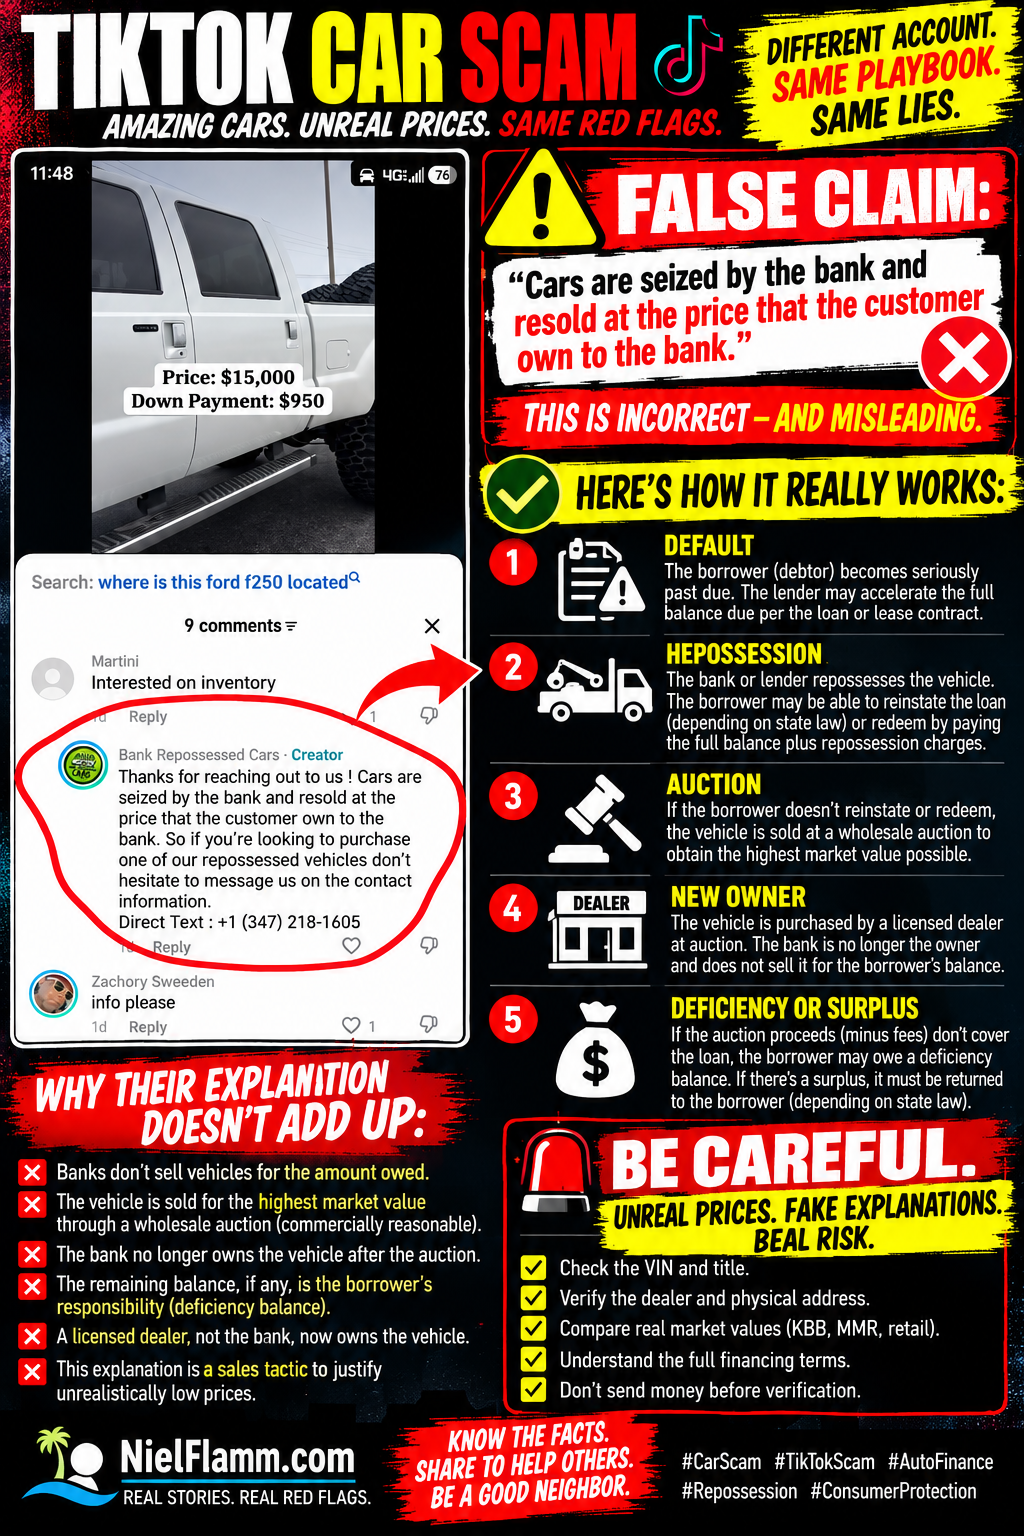
The “Bank Repo” Story Falls Apart: That’s Not How Vehicle Repossession Works
I've been following another TikTok account advertising remarkably inexpensive “bank repossessed” vehicles. This time, I noticed something in the comments that deserves its own post.
The account responded to someone interested in a vehicle with this explanation:
“Cars are seized by the bank and resold at the price that the customer own to the bank.”
In other words, the account appears to be telling potential buyers that banks repossess vehicles and then sell those vehicles for whatever balance the previous customer owed.
That's not an accurate description of the normal repossession and disposition process.
This is an area where I have quite a bit of professional experience.
First, Let's Talk About What Repossession Actually Is
A bank, credit union, captive automotive finance company or other lender doesn't generally repossess a vehicle because it suddenly wants to become a discount used-car dealership.
The vehicle is collateral securing a financial obligation.
When a borrower—often called the debtor—defaults under the retail installment contract or lease, the lender may have the contractual and legal right to repossess the vehicle. Exactly when that can happen and what notices are required depend on the contract and state law. The FTC notes that in many states, a lender may repossess once the borrower defaults, and missed payments are a common form of default. Consumer Advice
State laws vary significantly, so I'm not presenting one procedure as universal across all 50 states.
But the TikTok explanation isn't how the basic economics work.
Reinstatement and Redemption Come Before the Sale
After repossession, the borrower may still have rights.
Depending upon state law and the contract, a borrower may have an opportunity to reinstate the loan by bringing the delinquency current and paying allowable repossession-related expenses.
In other circumstances, the borrower may have the right to redeem the vehicle by paying the full amount required, along with applicable repossession expenses.
The CFPB specifically distinguishes these concepts. Some states permit curing or reinstating a loan after repossession, while redemption generally involves paying the full loan amount plus repossession costs before the vehicle is sold. Consumer Financial Protection Bureau
So repossession doesn't automatically mean:
Bank takes car → bank reviews the remaining balance → a random person gets a screaming deal.
There's a process.
Then Comes the Disposition of the Vehicle
If the borrower doesn't reinstate or redeem where those options apply, the lender may dispose of the collateral.
F
In the automotive finance world, repossessed vehicles commonly move through wholesale channels, including dealer auctions. But to be precise, federal guidance notes that a lender can sell a repossessed vehicle through a public or private sale, depending on applicable law and circumstances. Consumer Advice
Under Article 9 of the Uniform Commercial Code, every aspect of a secured creditor's disposition of collateral must be commercially reasonable. A sale may qualify when it's conducted in the usual manner in a recognized market, at the prevailing market price, or in accordance with reasonable commercial practices among dealers in that type of property. Legal Information Institute
That's an extremely important distinction.
The objective isn't:
“Bob owes $5,850, so let's sell Bob's $35,000 car for $5,850.”
The unpaid loan balance and the vehicle's market value are two different numbers.
That's Where the TikTok Explanation Really Falls Apart
Think about the implications of what this account is saying.
Suppose someone financed a $60,000 vehicle.
Years later, the vehicle is still worth $30,000.
But the borrower happens to owe only $6,000 when the vehicle is repossessed.
According to the explanation in this TikTok comment, the bank would essentially resell the vehicle for what the customer owed.
Why would a lender voluntarily turn a $30,000 asset into $6,000?
That's not how a commercially reasonable disposition works.
The vehicle is sold, the proceeds are applied according to the applicable rules, and then the account is reconciled. Under UCC Article 9, reasonable disposition expenses generally come out of the proceeds, followed by satisfaction of the secured obligation and certain other permitted claims. Legal Information Institute
And then we find out whether there's a deficiency or a surplus.
What's a Deficiency Balance?
Here's where my former world comes into play.
Suppose the borrower owes:
$25,000
The vehicle is repossessed and ultimately sells for:
$18,000
There are also allowable repossession, storage, auction or other disposition expenses.
After applying the proceeds, money is still owed.
That's the deficiency balance.
The CFPB defines a deficiency as the difference between the amount remaining on the loan, plus applicable repossession fees, and what the lender receives from selling the vehicle. Depending on state law and whether the lender complied with applicable requirements, the borrower may remain responsible for that balance. Consumer Financial Protection Bureau
The reverse can also happen.
If the disposition produces more money than the debt and allowable expenses, there can be a surplus, which generally must be returned to the debtor. Legal Information Institute
That's another reason the statement in the TikTok comment doesn't make sense.
The balance owed doesn't establish the vehicle's resale price.
How Do I Know This?
This isn't something I learned yesterday from Google.
In a previous professional life, I worked for a captive automotive finance company—the finance subsidiary of a major European import automobile manufacturer.
I held several different roles there.
I started in primary collections, working delinquent retail contracts at different stages and statuses.
I managed an inbound customer-service team.
I helped set up a predictive dialer.
I worked in retail credit, extending credit through franchised dealership partners.
And one of my other roles was in the loss/deficiency area.
That meant dealing with total losses, collecting total-loss and repossession deficiency balances, and handling post-repossession calls after the lender had taken possession of the collateral.
So when I read:
“Cars are seized by the bank and resold at the price that the customer owe to the bank.”
I don't just see questionable grammar.
I see an explanation of automotive finance that doesn't match the process I spent years working with.
There's Another Problem: “Bank Repossessed” Doesn't Explain a Huge Discount
This matters because the account uses the repossession story to explain prices that appear dramatically below normal market values.
If someone tells me:
“It's cheap because it's bank repossessed.”
That's not enough.
Repossession doesn't erase the market value of an automobile.
Neither does the word auction.
Wholesale values are generally lower than retail values—that's how dealers can acquire inventory, recondition it, cover overhead, and hopefully earn a profit.
But wholesale isn't synonymous with whatever the previous borrower owed.
Those are completely different concepts.
That's why I've been comparing these TikTok prices with KBB retail values and, when reliable vehicle-specific information is available, wholesale/MMR-type benchmarks.
And About That $15,000 F-250...
The video containing this comment shows a Ford F-250 advertised at:
Price: $15,000
Down payment: $950
The TikTok search prompt even asks:
“where is this ford f250 located”
Before anybody sends $950, I'd want a lot more information.
What's the year?
Trim?
Engine?
Mileage?
VIN?
Title status?
Accident history?
Physical location?
Dealer's legal business name?
Dealer license number?
Who actually owns the truck?
What are the complete financing terms?
And if this vehicle was supposedly repossessed by a bank, I'd especially like to know how the seller obtained it and why its current price is what it is.
“Because that's what the previous customer owed” isn't a satisfactory explanation.
A Reputable Lender Has Another Obligation: Commercial Reasonableness
This part shouldn't be overlooked.
A lender can't necessarily dump repossessed collateral for an arbitrary amount and then simply hand the enormous difference to the former borrower as a deficiency.
The disposition must meet applicable legal requirements, including the UCC's requirement that it be commercially reasonable. Legal Information Institute
That protects more than the lender.
It matters to the borrower, too.
Imagine owing $30,000 on a vehicle worth $28,000.
If the lender could arbitrarily sell it to somebody for $5,000 and then demand approximately $25,000 from the borrower, that would create an obvious problem.
That's one reason the manner in which repossessed collateral is disposed of matters.
Be Careful When the Explanation Is Part of the Sales Pitch
I want to make an important distinction.
A questionable explanation in a TikTok comment doesn't, by itself, establish every fact about the person or account behind it.
But I can evaluate the statement they published.
And the statement that repossessed cars are simply resold “at the price that the customer owes to the bank” is materially inconsistent with how reputable lenders generally dispose of repossessed vehicles.
That's significant when that very explanation is being offered to people asking about unusually inexpensive automobiles.
It's one more reason I would verify everything independently before sending a deposit.
Don't rely on the seller to explain why the seller's incredible deal is legitimate.
Check the VIN.
Check the title.
Check the dealer.
Check the physical address.
Check the dealer license.
Check the market value.
Check the financing.
And if the explanation of how repossession works doesn't make sense?
Ask more questions—not fewer.
I've actually worked this process from collections through repossession deficiencies.
So this time, the TikTok algorithm wandered directly into my old office.
Have a question about repossessions, deficiency balances, automotive financing, or one of these suspicious social-media car offers? Reach out by DM or email me at niel@nielflamm.com.
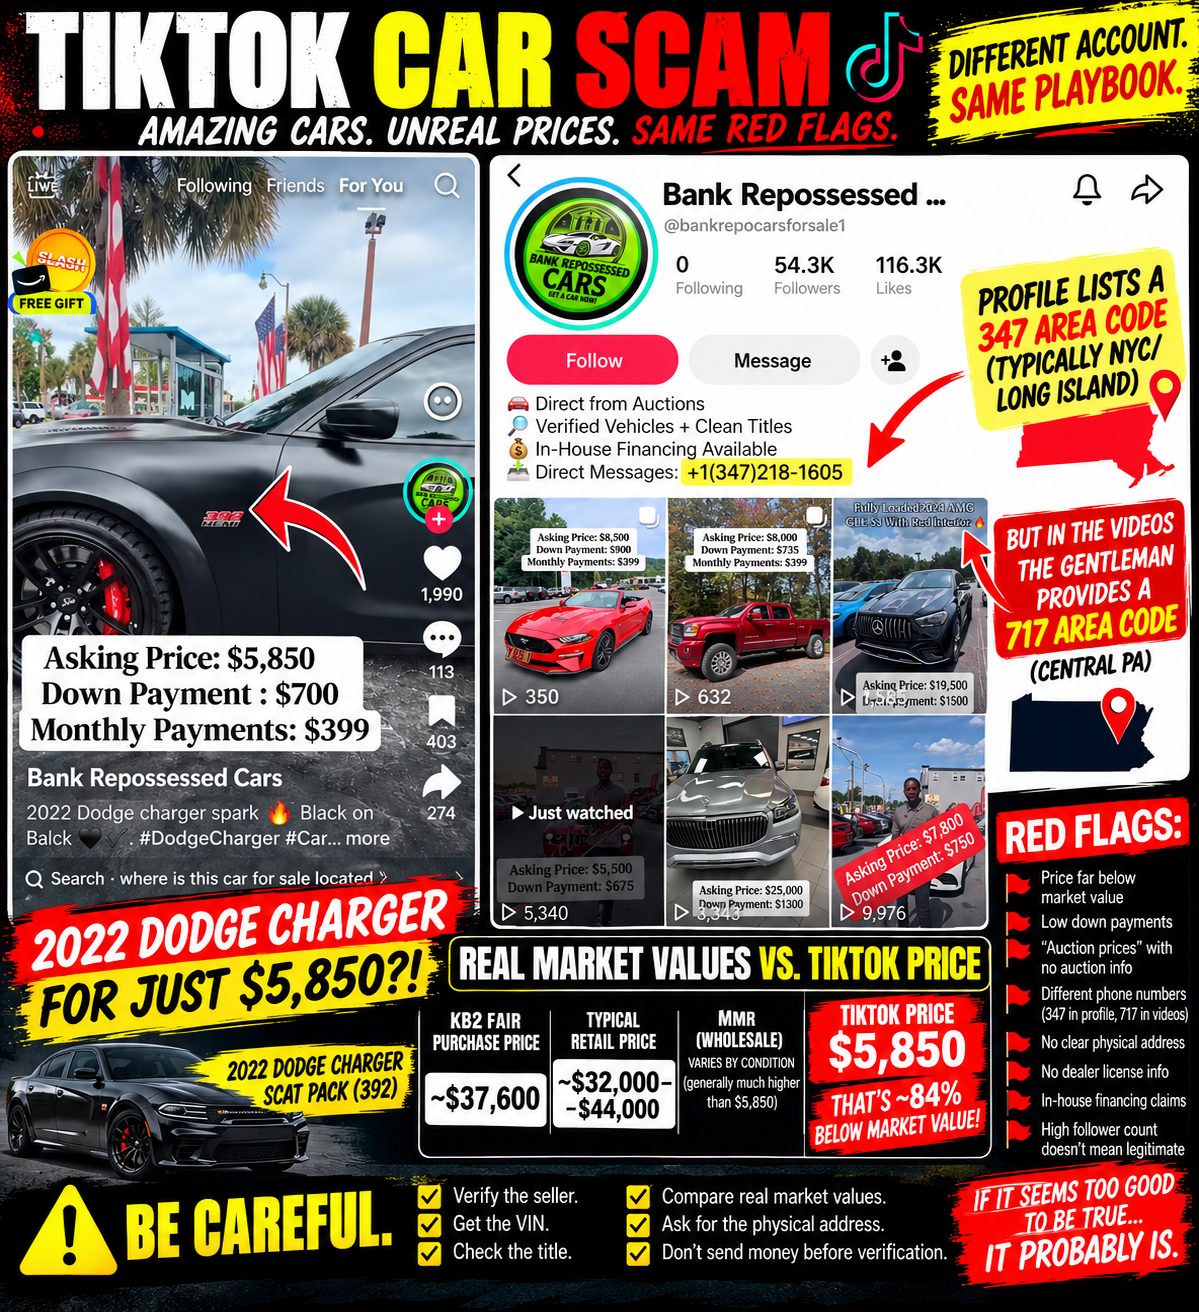
Another “Bank Repossessed” TikTok Car Deal — And the Phone Numbers Don’t Even Match
TikTok apparently still thinks I need a ridiculously inexpensive performance car.
The latest account to appear in my feed calls itself “Bank Repossessed Cars” and uses the handle @bankrepocarsforsale1.
At the time of my screenshot, the account had:
54,300 followers.
116,300 likes.
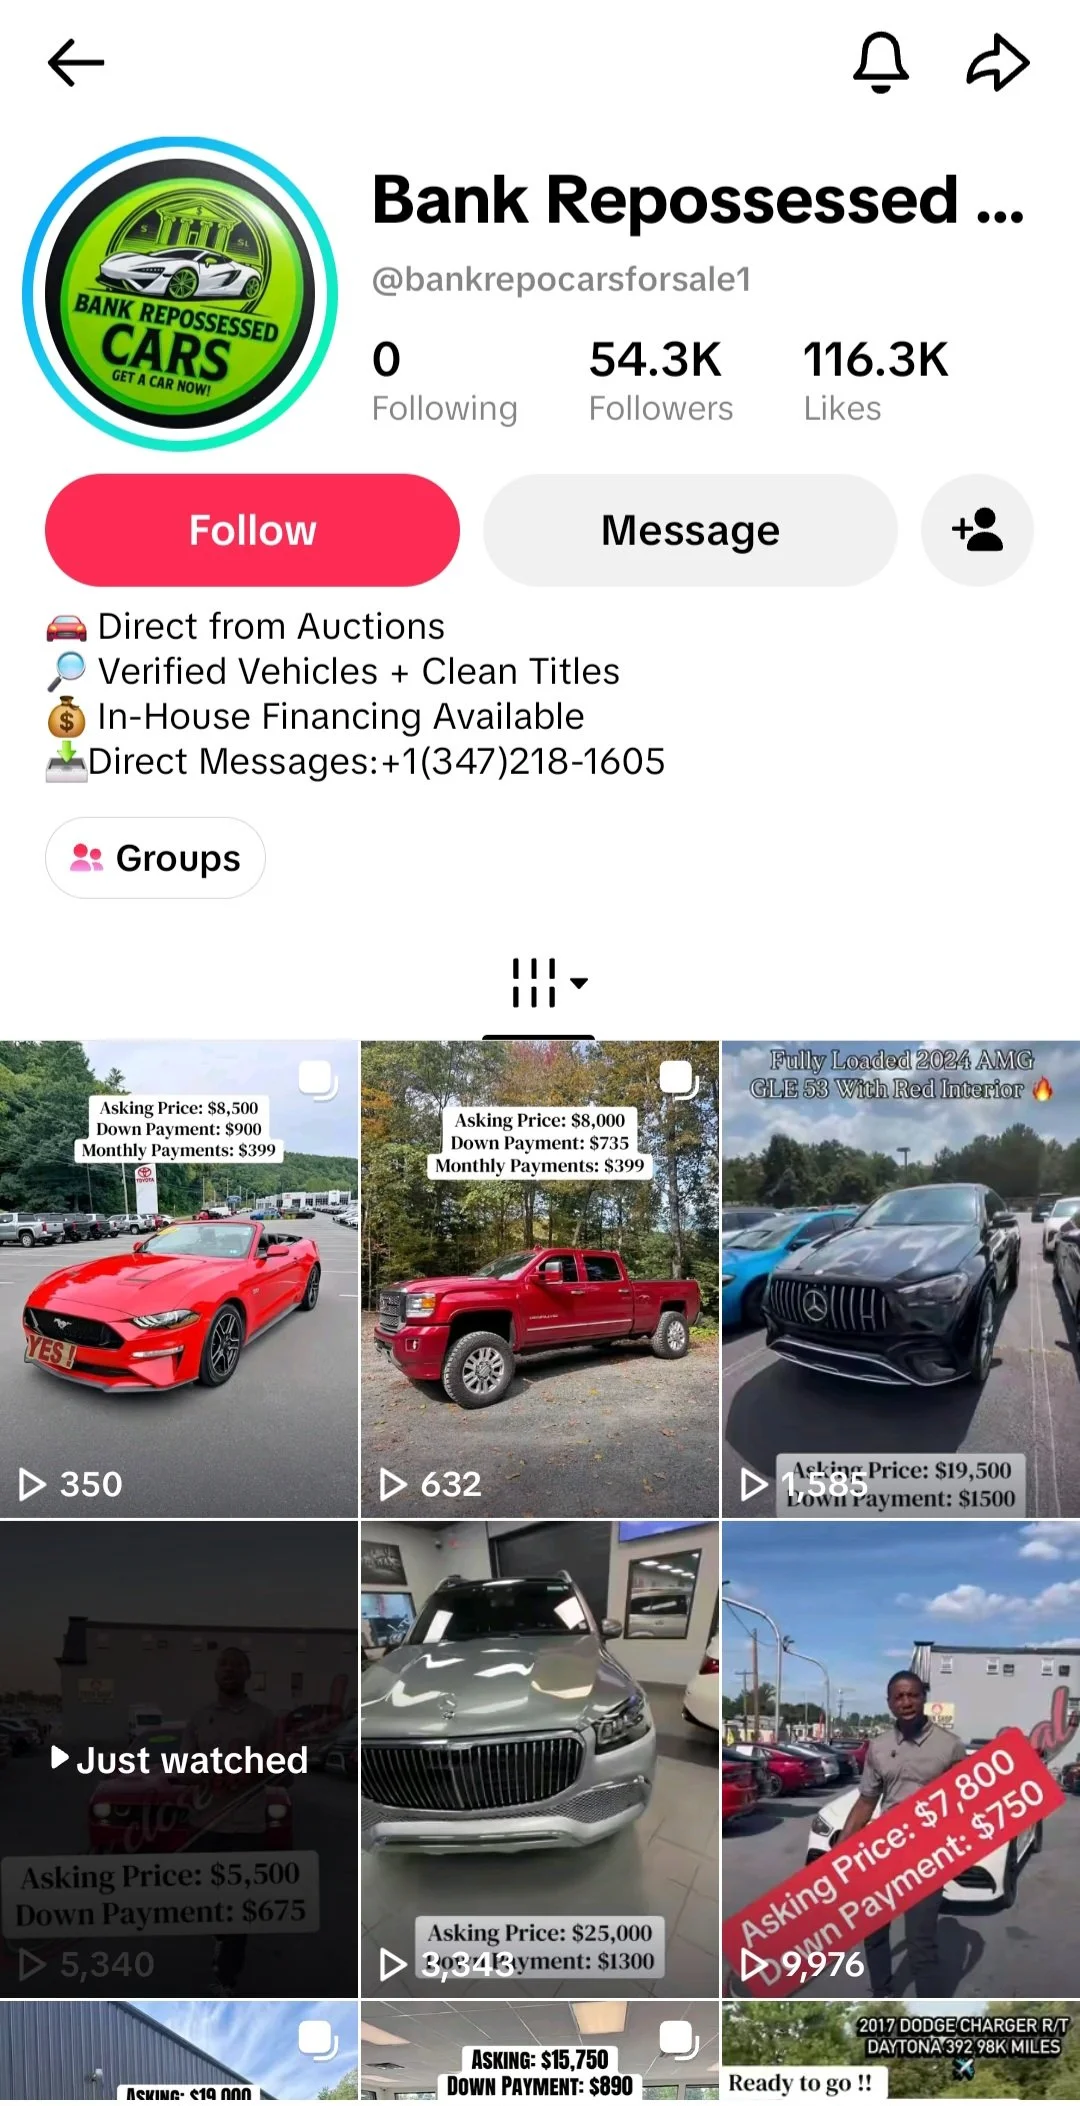
That's substantially larger than several of the questionable car accounts I've written about before.
The profile says:
🚗 Direct from Auctions
🔎 Verified Vehicles + Clean Titles
💰 In-House Financing Available
And then there's a telephone number for direct messages:
+1 (347) 218-1605
Sounds impressive.
Then I started watching the videos.
And once again, I have questions.
🚗 Today's Deal: A 2022 Dodge Charger for $5,850
The video that caught my attention shows what is described as a 2022 Dodge Charger with the following offer:
Asking Price: $5,850
Down Payment: $700
Monthly Payments: $399
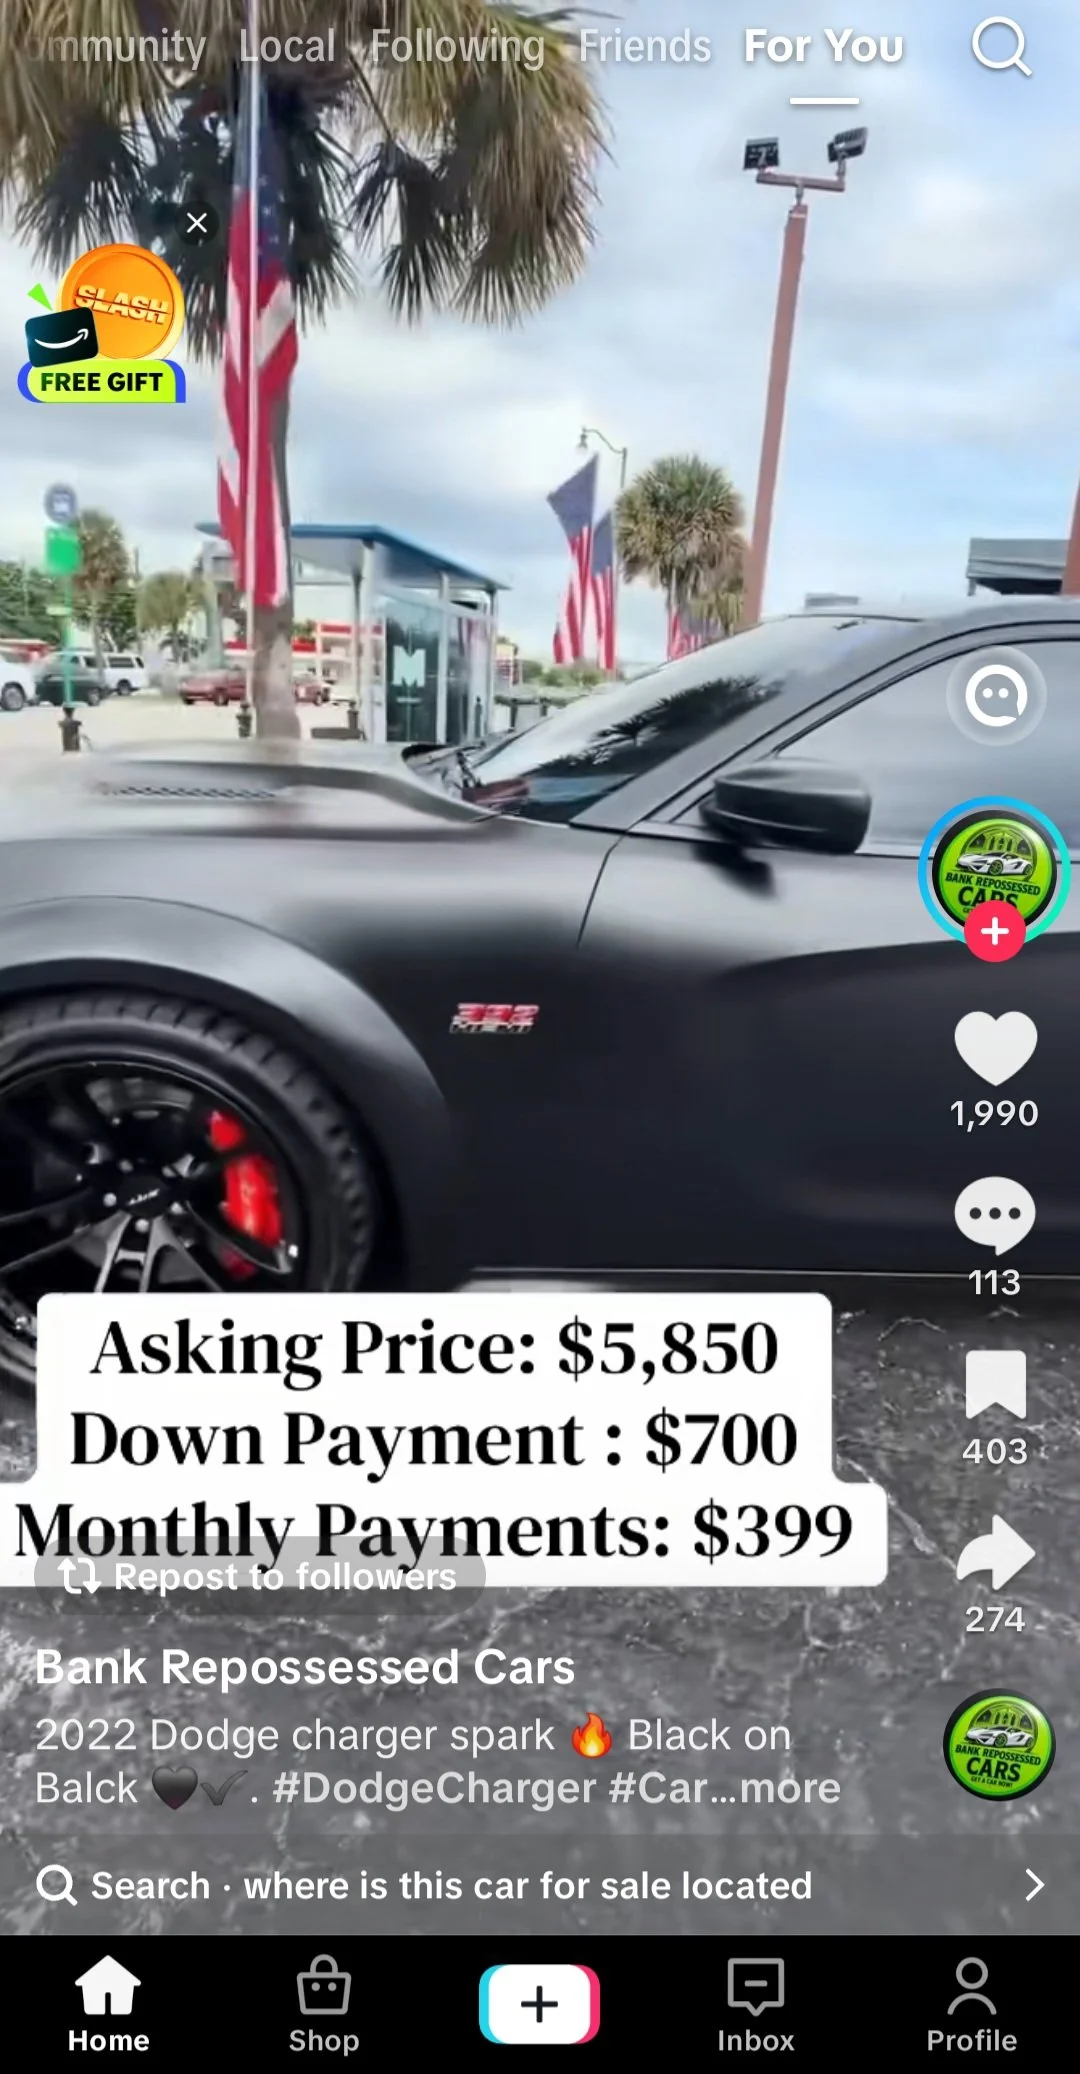
The caption describes it as a “2022 Dodge Charger spark”, although the vehicle shown appears to carry a 392 badge.
If this is actually a 2022 Charger Scat Pack/392, that $5,850 advertised price deserves a very close look.
Why?
Because the market numbers aren't even in the same neighborhood.
💰 Kelley Blue Book Says About $37,000 — Not $5,850
Kelley Blue Book currently puts the national Fair Purchase Price of a 2022 Dodge Charger Scat Pack around $37,600. KBB lists roughly $31,900 trade-in, $34,800 private-party, and $37,600 Fair Purchase Price for a good-condition example, while a Scat Pack Widebody is higher still at about $44,100 Fair Purchase Price. Exact values vary with mileage, condition, options, and location. Kbb.com
Edmunds tells a similar story: its current dealer-retail estimate for a regular 2022 Scat Pack ranges from roughly $32,300 in rough condition to $39,500 in outstanding condition. Edmunds
CARFAX's current listings put 2022 Charger Scat Packs at an average listing price of about $44,347, with its displayed range running roughly $36,747–$52,950. Carfax
TikTok?
$5,850.
That's roughly 84% below KBB's $37,600 Fair Purchase Price.
Maybe there's an explanation.
Fantastic.
I'd like to hear it.
🔨 But What About MMR and “Auction Prices”?
This account specifically promotes the vehicles as coming “Direct from Auctions.”
That's where the Manheim Market Report—or MMR—comes in.
MMR isn't the same thing as KBB retail value. Manheim describes MMR as a wholesale-market valuation based on actual vehicles sold through Manheim, with values that can be adjusted for factors such as odometer reading, selling region, condition grade and even color. Manheim
That's why I'm not going to invent an exact MMR for the Charger in this video.
I don't have its VIN.
I don't have verified mileage.
I don't have its condition report.
I don't have its auction location.
I don't have a current vehicle-specific Manheim report.
Without those things, saying, “The MMR is exactly $XX,XXX,” would be pretending to know something I don't.
But here's what we can compare.
KBB puts the Scat Pack's trade-in value around $31,900. JD Power estimates a trade-in base of around $31,250–$33,250, depending on condition. Those aren't MMR, but they're useful wholesale-side reference points. Kbb.com
So if this really is a clean-title 2022 Scat Pack being sold for $5,850, the question isn't simply:
“Is it cheaper because it came from an auction?”
The question is:
How did someone acquire a vehicle worth tens of thousands of dollars cheaply enough to retail it for $5,850?
“Auction” isn't a magic word that makes vehicle economics disappear.
📞 Then I Noticed the Phone Numbers
Here's where things became even more interesting.
The TikTok profile lists:
+1 (347) 218-1605
The 347 area code is associated with New York City, including the boroughs of Brooklyn, Queens, the Bronx and Staten Island. It's commonly encountered around the broader NYC/Long Island market, although an area code obviously doesn't establish where somebody currently lives or operates a business.
But I watched several of the account's videos.
The gentleman appearing in those videos provides a different telephone number—with a 717 area code.
The 717 area code serves south-central Pennsylvania, including Harrisburg, Lancaster, and York.
Again, people keep phone numbers after moving. Businesses can have multiple telephone numbers. VOIP numbers exist. None of this, by itself, proves anything improper.
But when I'm supposedly dealing with a business selling cars online, it's another question I'd want answered:
Why does the profile give me one phone number while the person in the videos gives me another?
And, more importantly:
What's the actual dealership?
Where is it physically located?
Which number belongs to that dealership?
Those should be remarkably easy questions for a legitimate automobile dealer to answer.
👀 And Look at the Rest of the Inventory
The Charger isn't alone.
The profile shows a Mustang advertised for:
$8,500 — $900 down — $399/month
A GMC pickup:
$8,000 — $735 down — $399/month
A Mercedes-AMG GLE 53 appears to be advertised around:
$19,500 — $1,500 down
Another vehicle:
$5,500 — $500 down
Another:
$7,800 — $750 down
There's even a vehicle shown around $25,000 with $1,300 down.
The scenery changes.
The dealerships and lots visible in the videos appear to change.
The vehicles range from ordinary transportation to expensive luxury and performance models.
Yet the formula remains remarkably familiar.
🚩 “Verified Vehicles + Clean Titles”
Great.
Verified by whom?
That's not sarcasm. That's an actual question I'd ask before buying.
If I'm buying one of these cars, give me the VIN.
Then I can verify the vehicle myself.
If it has a clean title, provide the documentation I need to confirm it independently.
If it came from an auction, tell me which auction.
If you're a licensed dealer, give me the legal business name, physical address, and dealer-license information.
If you're offering in-house financing, give me the written financing terms.
I don't need a green checkmark emoji.
I need documentation.
💳 $700 Down and $399 a Month — What's the Loan?
There's another mathematical problem worth examining.
The Charger is advertised at:
$5,850 purchase price
minus
$700 down
which leaves:
$5,150
If the payments really are $399 per month, $5,150 divided by $399 is only about 12.9 payments, before interest, taxes, fees, or anything else.
So what's the actual term?
What's the APR?
What's the amount financed?
What's the total of payments?
Who's extending the credit?
Are there additional fees?
If the actual vehicle costs $5,850, those should be straightforward questions.
If $5,850 isn't actually the total cash price, then I'd like to know what that number represents.
🚩 54,000 Followers Don't Answer Any of This
This account is bigger than many I've previously documented.
54,300 followers.
That's meaningful social proof.
Someone encountering the account might reasonably think:
They have 54,000 followers. They must be legitimate.
But we've been through this before.
Followers aren't a dealer license.
Likes aren't a title.
Views aren't a VIN.
A green checkmark emoji isn't vehicle verification.
And a real person standing beside a real automobile doesn't establish that the TikTok account displaying the footage owns that automobile or is authorized to sell it under the advertised terms.
🚗 A Real Car Still Doesn't Automatically Make the Offer Real
This has become a recurring theme in this series.
Some of these videos clearly contain actual cars.
Some appear to have been filmed at actual dealerships.
There are real salespeople.
Real parking lots.
Real transporters.
Real dealership signs.
That's persuasive imagery.
But the question isn't:
“Does the car in this video exist?”
It's:
“Does this TikTok account own or have authority to sell this exact vehicle for this exact price under these exact terms?”
Those are very different questions.
I'm not claiming the footage on this account was copied from somewhere else. I haven't established that.
But before sending a $700 deposit, I'd want to establish where the footage came from and whether the seller I'm communicating with is actually connected to that vehicle.
🏡 Be Careful — and Be a Good Neighbor
This is the part that matters most.
Imagine someone who has terrible credit.
Their car just died.
They need transportation Monday morning, or they risk losing their job.
Traditional dealerships have turned them down.
Then TikTok serves them:
2022 Dodge Charger
$5,850
$700 down
$399/month
In-house financing available
That doesn't necessarily look suspicious to someone in that situation.
It looks like hope.
That's why, if somebody you know is considering one of these deals, don't ridicule them.
Help them investigate.
Before sending money, get the VIN. Verify the title. Find the dealership's legal name and physical address independently. Verify the dealer license with the appropriate state regulator. Call a publicly listed number—not simply the number supplied in a TikTok profile. Get the complete financing agreement. Have the vehicle independently inspected. And compare the asking price with retail and realistic wholesale values.
If the seller won't let you do those things before sending a deposit?
Keep your $700.
Different Account. Same Questions.
I'm seeing this pattern often enough that I can practically write the checklist before opening the profile.
Extremely inexpensive desirable car.
Small down payment.
Low monthly payment.
“Direct from auction.”
“Clean title.”
“In-house financing.”
Private messages.
Phone numbers that raise additional questions.
And prices that appear wildly disconnected from ordinary retail values.
Maybe this account has a perfectly reasonable explanation for it all.
I'd be interested in hearing it.
Because based on the screenshot, a $5,850 2022 Charger that appears to be a 392, compared with a KBB Fair Purchase Price around $37,600 for a Scat Pack, is one heck of an explanation. Kbb.com
Until then:
Be careful. Verify everything. And don't let a $700 down payment make a $30,000 question disappear.
Follow the continuing series at NielFlamm.com/blog.
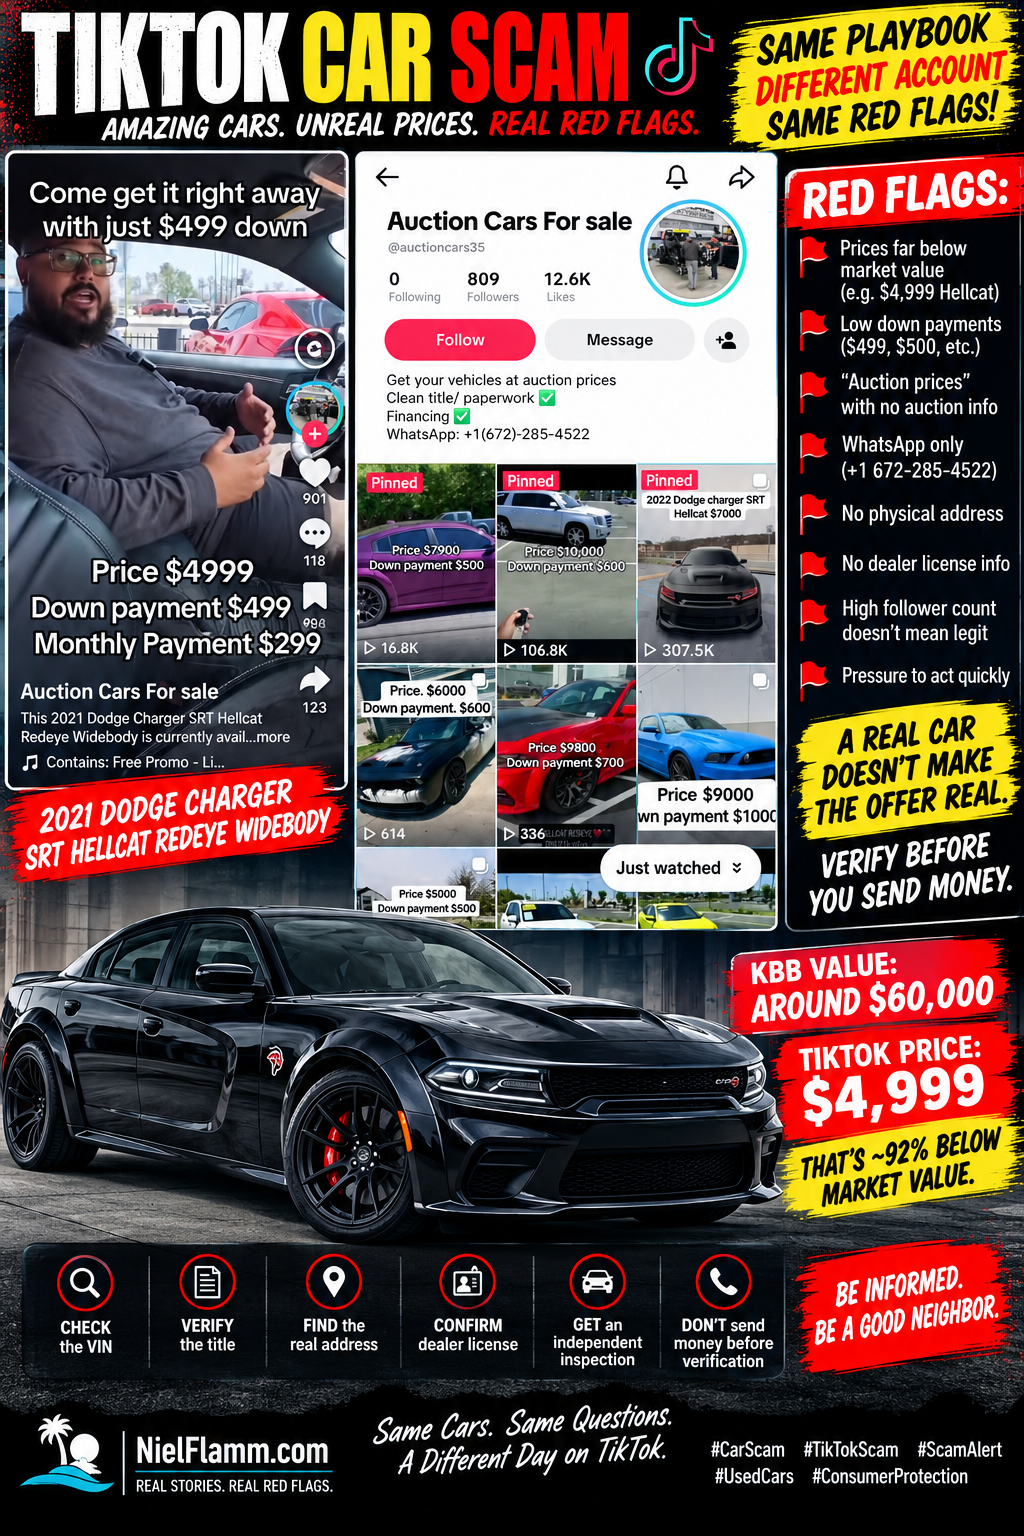
Another TikTok “Auction Car” Deal: A $60,000 Hellcat for $4,999? Here We Go Again
Apparently TikTok has decided I need another car.
Actually, based on what keeps showing up in my feed, TikTok apparently thinks I need an entire dealership.
After documenting accounts advertising $4,000 Scat Packs, $7,000 Camrys, $10,000 BMW M3S, and other remarkably inexpensive vehicles, another account landed in my “For You” feed.
This one calls itself:
Auction Cars For Sale — @auctioncars35
And we've got another Hellcat.
According to the video:
2021 Dodge Charger SRT Hellcat Redeye Widebody
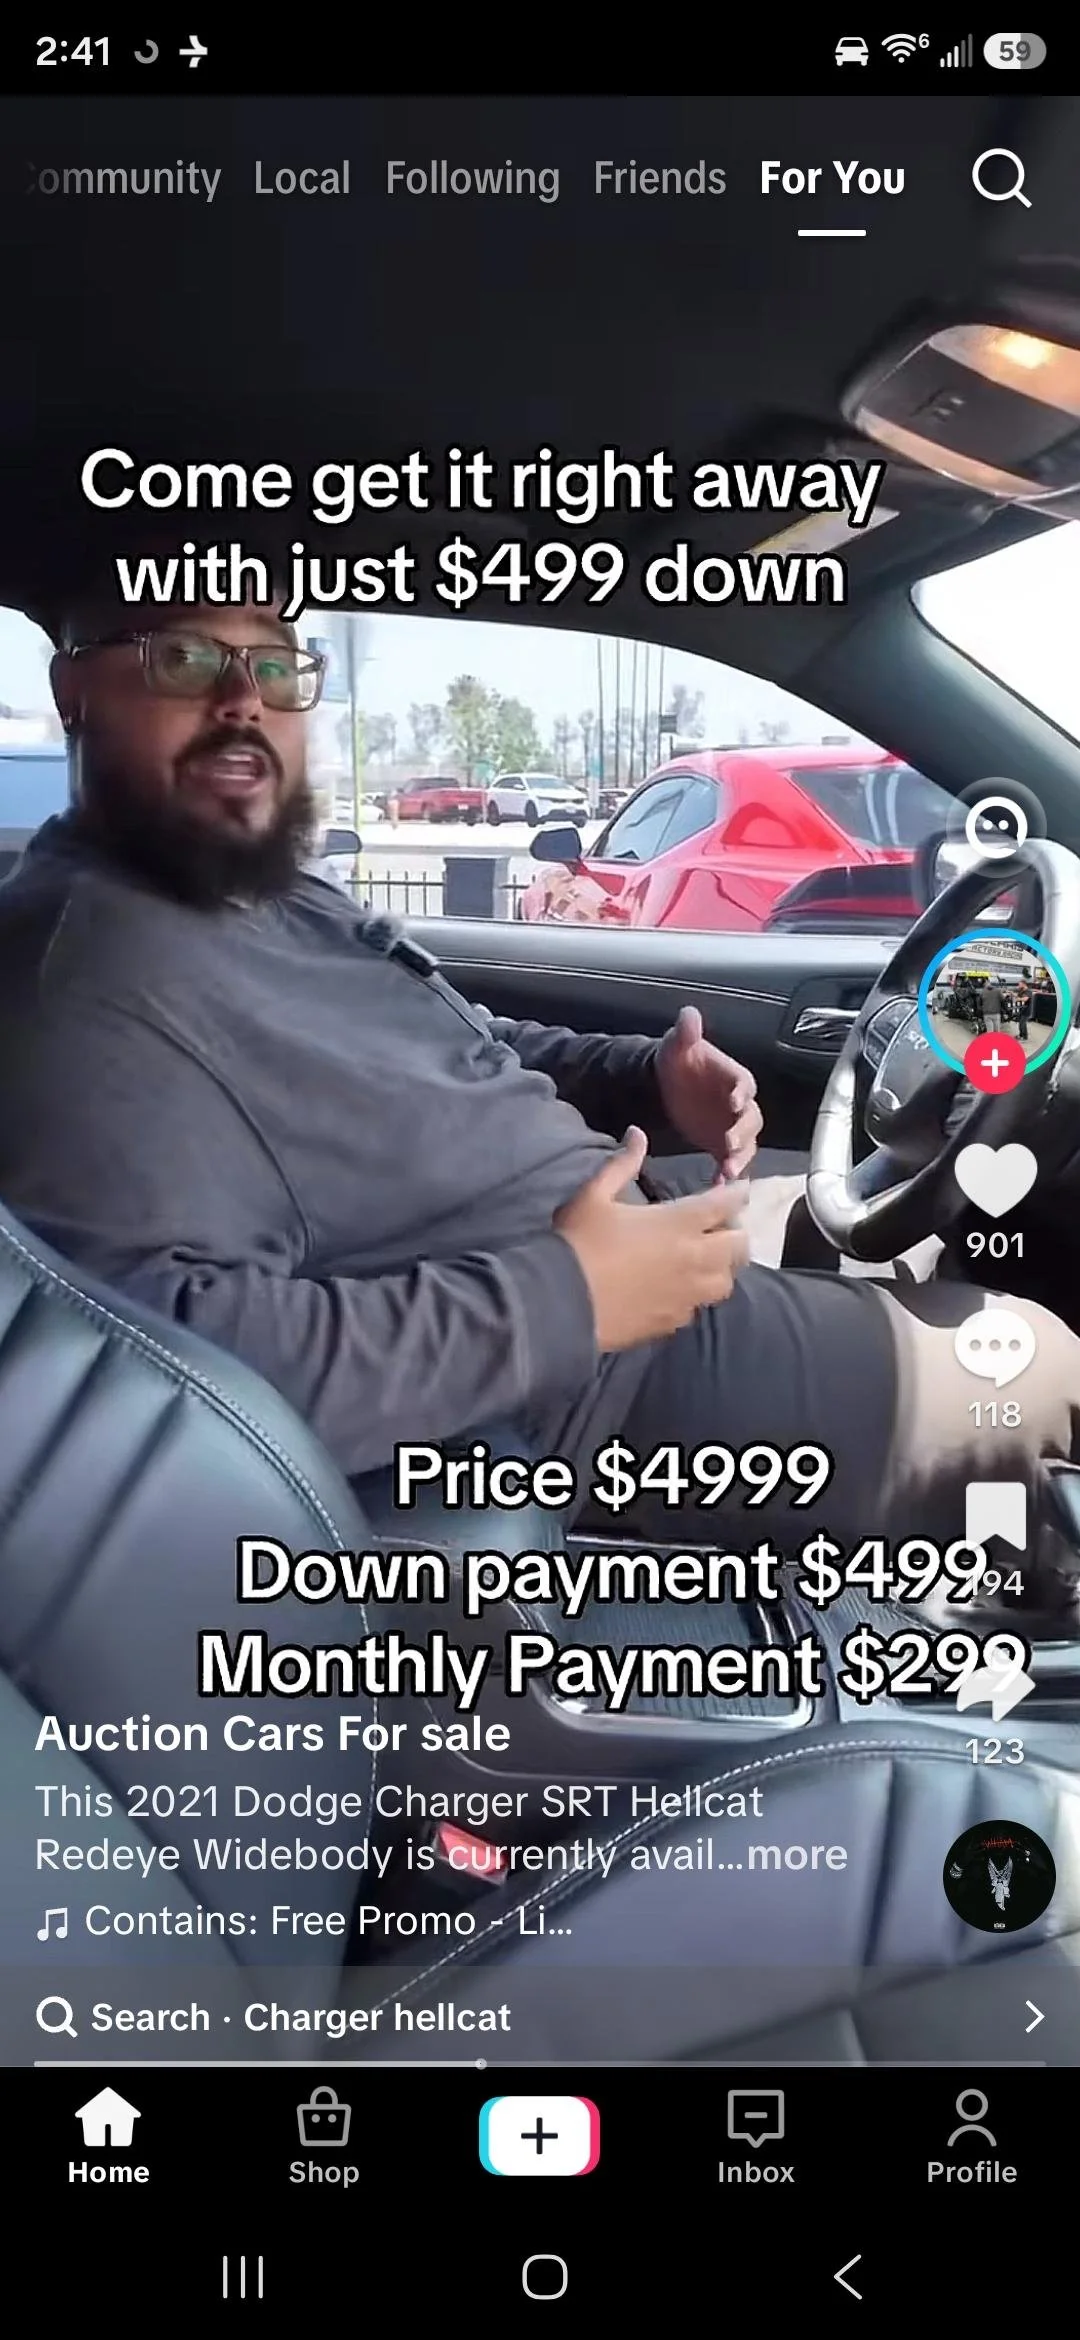
Price: $4,999
Down payment: $499
Monthly payment: $299
Come get it right away!
Well, hold on.
🚩 A $4,999 Hellcat Redeye?
This isn't just an inexpensive used Dodge Charger.
The post specifically identifies it as a 2021 Dodge Charger SRT Hellcat Redeye Widebody.
Kelley Blue Book currently puts the Fair Purchase Price for that model around $60,500, with estimated private-party values ranging roughly from $52,000 to $60,000, depending on condition. KBB also notes that mileage, condition, location, and equipment can significantly affect an individual vehicle's value. Kelley Blue Book
The TikTok price?
$4,999
That's roughly 92% below KBB's $60,500 Fair Purchase Price.
Now, could an extraordinarily cheap Hellcat exist?
Absolutely.
It could have major damage. It could have mechanical problems. It could have a branded title. There could be circumstances we can't see from a TikTok video.
But if you're asking me to believe a vehicle worth tens of thousands of dollars is available for less than $5,000, I need an explanation.
And documentation.
Lots of documentation.
💰 $499 Down, $299 a Month... For How Long?
Then we have the financing.
Price: $4,999
Down payment: $499
Monthly payment: $299
Okay.
If $4,999 is truly the purchase price, subtracting the $499 down payment leaves $4,500.
At $299 per month, ignoring interest, taxes, and every other fee, that would pay off the remaining balance in only about 15 months.
But where are the complete financing terms?
What's the APR?
What's the loan term?
Who's the lender?
What are the taxes and fees?
What credit qualifications apply?
Is $4,999 actually the cash selling price?
Those details matter considerably more than the giant $499 DOWN floating across the TikTok video.
👀 Then I Looked at the Profile
The account had 809 followers and 12,600 likes when I took the screenshot.
Its profile says:
“Get your vehicles at auction prices”
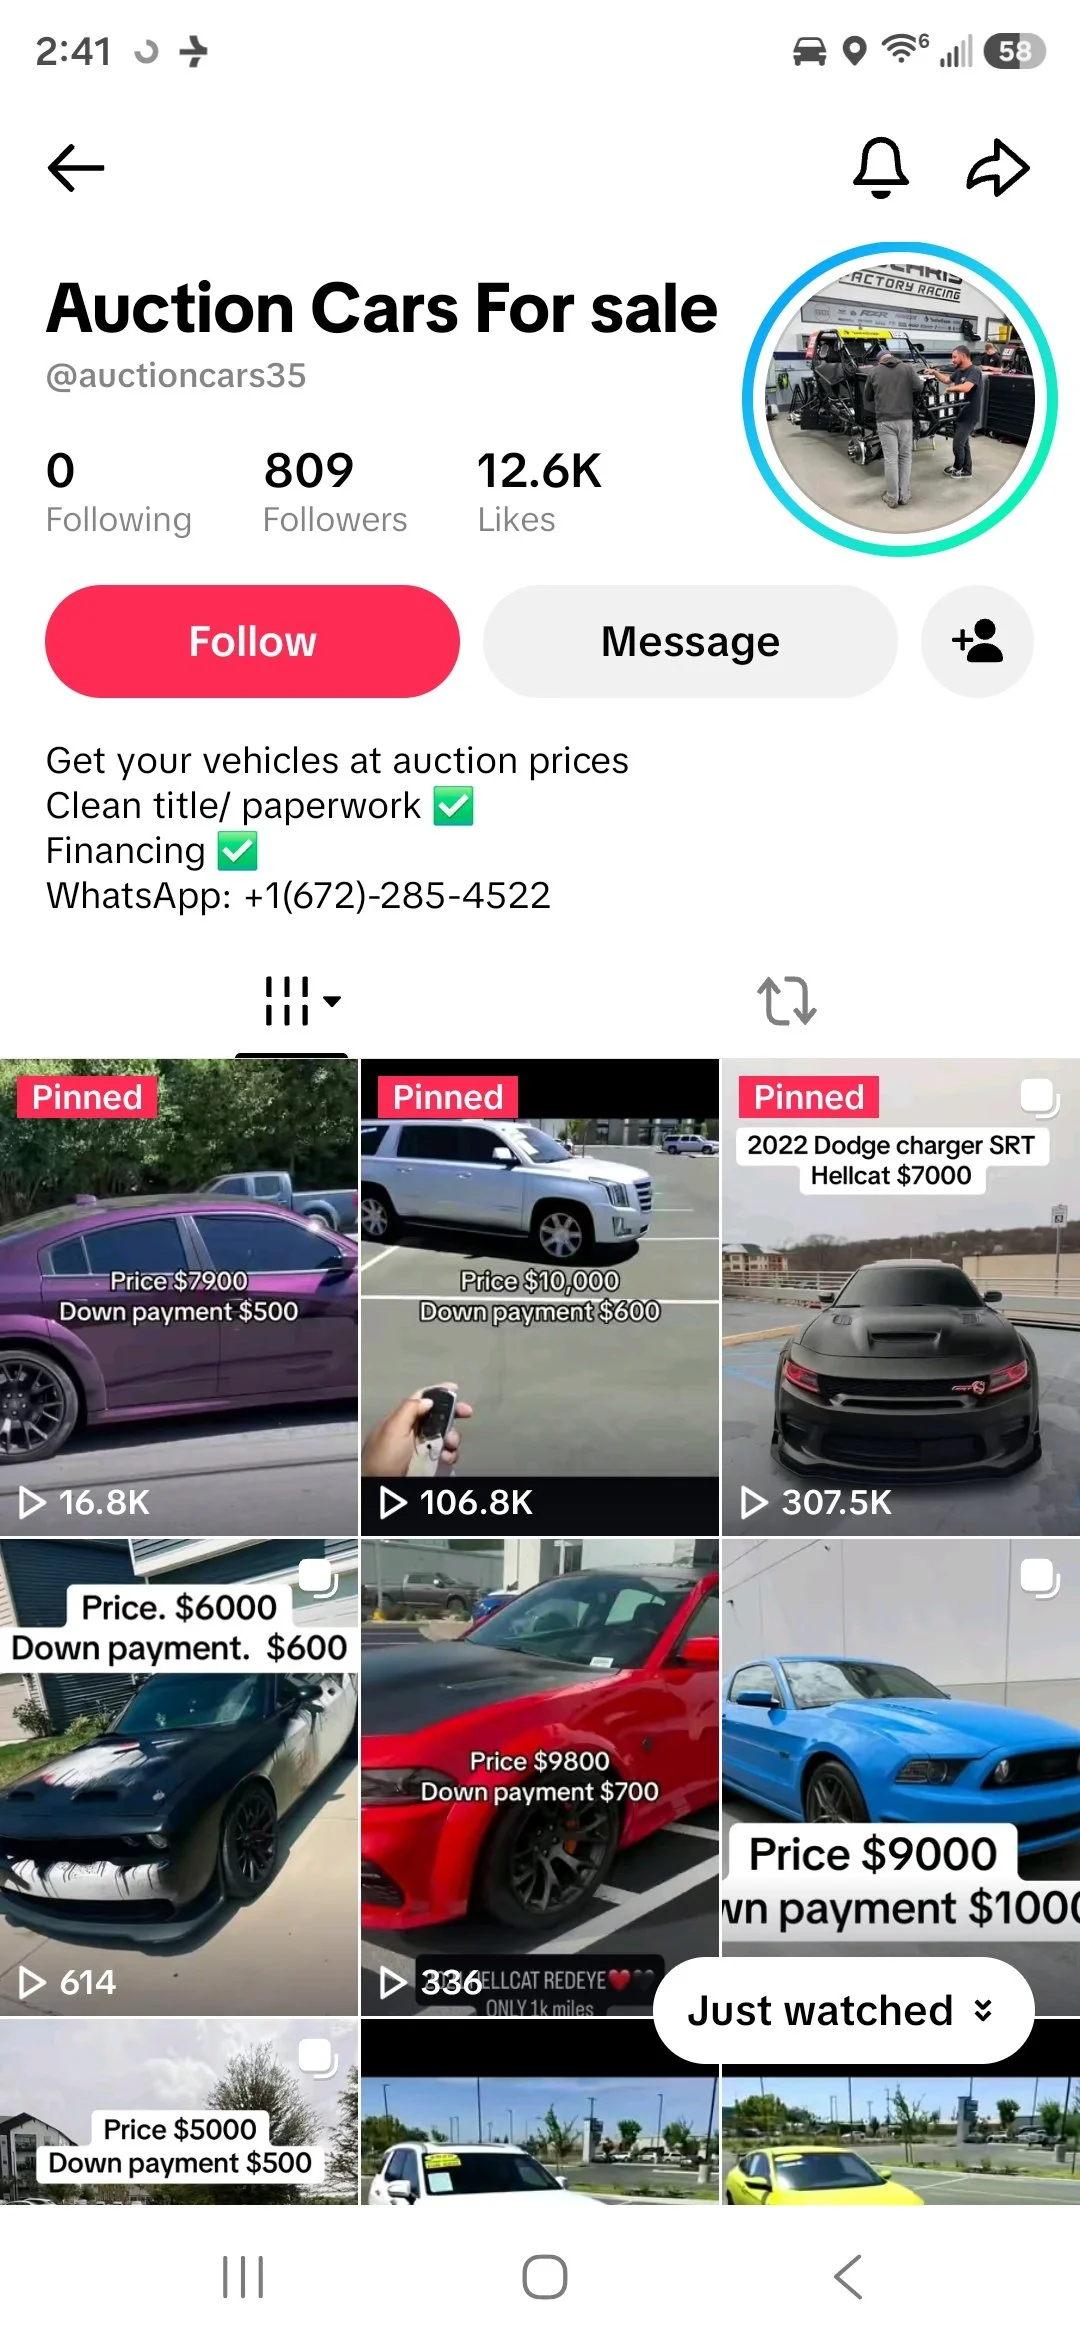
“Clean title/paperwork ✅”
“Financing ✅”
And then:
WhatsApp: +1 (672)-285-4522
There's that familiar move to WhatsApp again.
WhatsApp itself isn't evidence of a scam. Legitimate businesses use it every day.
But if I'm buying a $60,000-class performance car, I want a little more than a TikTok profile and a WhatsApp number.
Where is the business?
What's the legal company name?
What's the physical address?
What's the dealer license number?
What auction is supplying these vehicles?
What's the VIN?
Who's providing the financing?
Can I see the title?
Can I have an independent mechanic inspect the car?
Those questions aren't unreasonable.
They're called buying a car.
😂 Apparently Hellcats Are Having a Clearance Sale
Then I looked at the rest of the profile.
This isn't a one-car phenomenon.
One pinned video appears to advertise a vehicle for:
$7,900 — $500 down
Another:
$10,000 — $600 down
And another pinned video says:
“2022 Dodge Charger SRT Hellcat $7000”
Seven thousand dollars.
For another Hellcat.
Elsewhere, I can see vehicles advertised at:
$6,000 with $600 down
$9,800 with $700 down
$9,000 with $1,000 down
$5,000 with $500 down
Once again, we're seeing the same basic formula I've been documenting across multiple TikTok accounts:
Desirable vehicle.
Extraordinarily low advertised price.
Small down payment.
Financing.
WhatsApp.
Act now.
Different account.
Same questions.
📊 For Perspective: Even Ordinary Chargers Cost More
KBB's current national averages illustrate just how unusual these numbers are.
A regular 2021 Charger SXT has a Fair Purchase Price around $18,500. A Scat Pack is around $32,300, a Scat Pack Widebody around $38,000, and a Hellcat Redeye Widebody around $62,300 on KBB's broader 2021 Charger pricing page. Kelley Blue Book
So the $4,999 TikTok asking price isn't merely inexpensive compared with another Redeye.
It's dramatically below KBB's current Fair Purchase Price for even the least expensive 2021 Charger trim.
That doesn't independently prove anything about this particular vehicle.
It does give me an excellent reason to investigate before reaching for my wallet.
🏷️ But They're “Auction Cars”
That's presumably supposed to explain the prices.
Auctions absolutely can produce vehicles below retail value.
I've discussed the Manheim Market Report (MMR) in previous posts because wholesale value and retail value aren't the same thing.
Dealers buy at wholesale and try to sell at retail. Condition, mileage, title history, location, demand, and vehicle configuration all matter.
But “auction price” isn't a magic phrase that makes market economics disappear.
If a supposedly clean-title Hellcat has a retail value around $60,000 and someone is selling it for $4,999, I'd still like to know:
What did the seller pay for it?
Which auction did it come from?
What's the VIN?
What's the title status?
What's wrong with it?
Why is it being sold for a fraction of its market value?
A legitimate explanation can be checked.
🚗 And Yes, That's a Real Car in the Video
We've encountered this issue repeatedly in this series.
A man sits inside a Charger.
We can see the interior.
There's another vehicle outside.
It looks like a real dealership or automotive environment.
That's visually persuasive.
But here's the line I'm going to keep repeating:
A real car doesn't automatically make the offer real.
A TikTok account showing footage of an actual automobile doesn't, by itself, establish that the account owns the vehicle, has authority to sell it, or can deliver it under the advertised terms.
Videos can be reposted.
Dealer footage can be reused.
Auction footage can be copied.
Customer-delivery videos can be repurposed.
I'm not saying that's necessarily what happened here. I haven't established where this particular footage originated.
I'm saying the video itself isn't proof of ownership.
🚩 Followers and Views Aren't Verification Either
One of this account's pinned videos shows more than 300,000 views.
Another has more than 100,000.
That creates powerful social proof.
If 300,000 people watched it, it may feel legitimate.
If hundreds of people liked it, it may feel legitimate.
If other people are commenting that they're interested, maybe it feels legitimate.
But we've learned this lesson already:
Followers aren't a dealer license.
Likes aren't a vehicle title.
Views aren't a VIN.
And 300,000 views don't transform a $60,000 vehicle into a $4,999 vehicle.
🧮 Show Me the Economics
This remains one of my favorite tests.
Forget TikTok for a moment.
Forget the music.
Forget the guy sitting inside the car.
Forget the giant $499 DOWN text.
Explain the transaction economically.
If a dealer can legitimately acquire a clean-title 2021 Hellcat Redeye Widebody cheaply enough to sell it for $4,999 and make money, I want to understand how.
Maybe there's an explanation.
Great.
Show me.
Give me the VIN.
Show me the title.
Tell me the auction.
Give me the physical location.
Show me the purchase agreement.
Let me independently verify the dealership.
Let me arrange an independent inspection.
Give me the financing disclosures.
Those things interest me far more than a TikTok follower count.
🚨 Don't Let the Deposit Become the Decision
This is where these advertisements concern me most.
The headline isn't:
“Please conduct a comprehensive examination of this vehicle's ownership, title history, and financing.”
It's:
$499 DOWN
That's a psychologically manageable number.
Someone who can't afford a $60,000 Hellcat might be able to find $499.
And once someone sends that first $499, the psychology changes.
They've committed.
That's why verification needs to happen before money changes hands.
The FTC has repeatedly warned consumers about online vehicle-related scams and emphasizes caution when someone online asks you to send money in transactions that can't be independently verified. Consumer Advice
🏡 Be a Good Neighbor
This is also why I keep posting these.
Someone looking at this advertisement might not see what I see.
They might see:
2021 Hellcat Redeye.
$4,999.
$499 down.
$299 a month.
And think:
“I can actually afford my dream car.”
Don't make fun of that person.
Help them.
Before they send $499, ask for 15 minutes.
Check the VIN.
Check KBB.
Check the title.
Find the business independently.
Verify the dealer license.
Call a telephone number obtained independently.
Ask for the physical address.
Arrange an inspection.
Read the financing agreement.
And if the seller starts creating urgency because somebody else is supposedly about to buy the car?
Let the other imaginary customer have it.
Different Account. Same Playbook?
That's what I'm trying to document.
I've now encountered multiple social-media accounts advertising remarkably inexpensive cars with tiny down payments.
The names change.
The cars change.
The phone numbers change.
The prices change.
But I keep seeing familiar ingredients.
Unusually cheap vehicles.
Tiny deposits.
Social-media storefronts.
Private messaging.
WhatsApp.
Financing claims.
Shipping or delivery.
And vehicles priced far below ordinary retail values.
Does that automatically prove this particular TikTok account is fraudulent?
No.
But $4,999 for a vehicle KBB values at around $60,000 is more than enough reason for me to start asking questions. Kelley Blue Book
And judging by my recent experiences, I seem to be getting pretty good at making TikTok car sellers uncomfortable with one particularly difficult question:
What's the address?
Follow the continuing investigation at NielFlamm.com/blog.
Update: The “Totally Legitimate” TikTok Car Seller Blocked Me
Well, that escalated quickly.
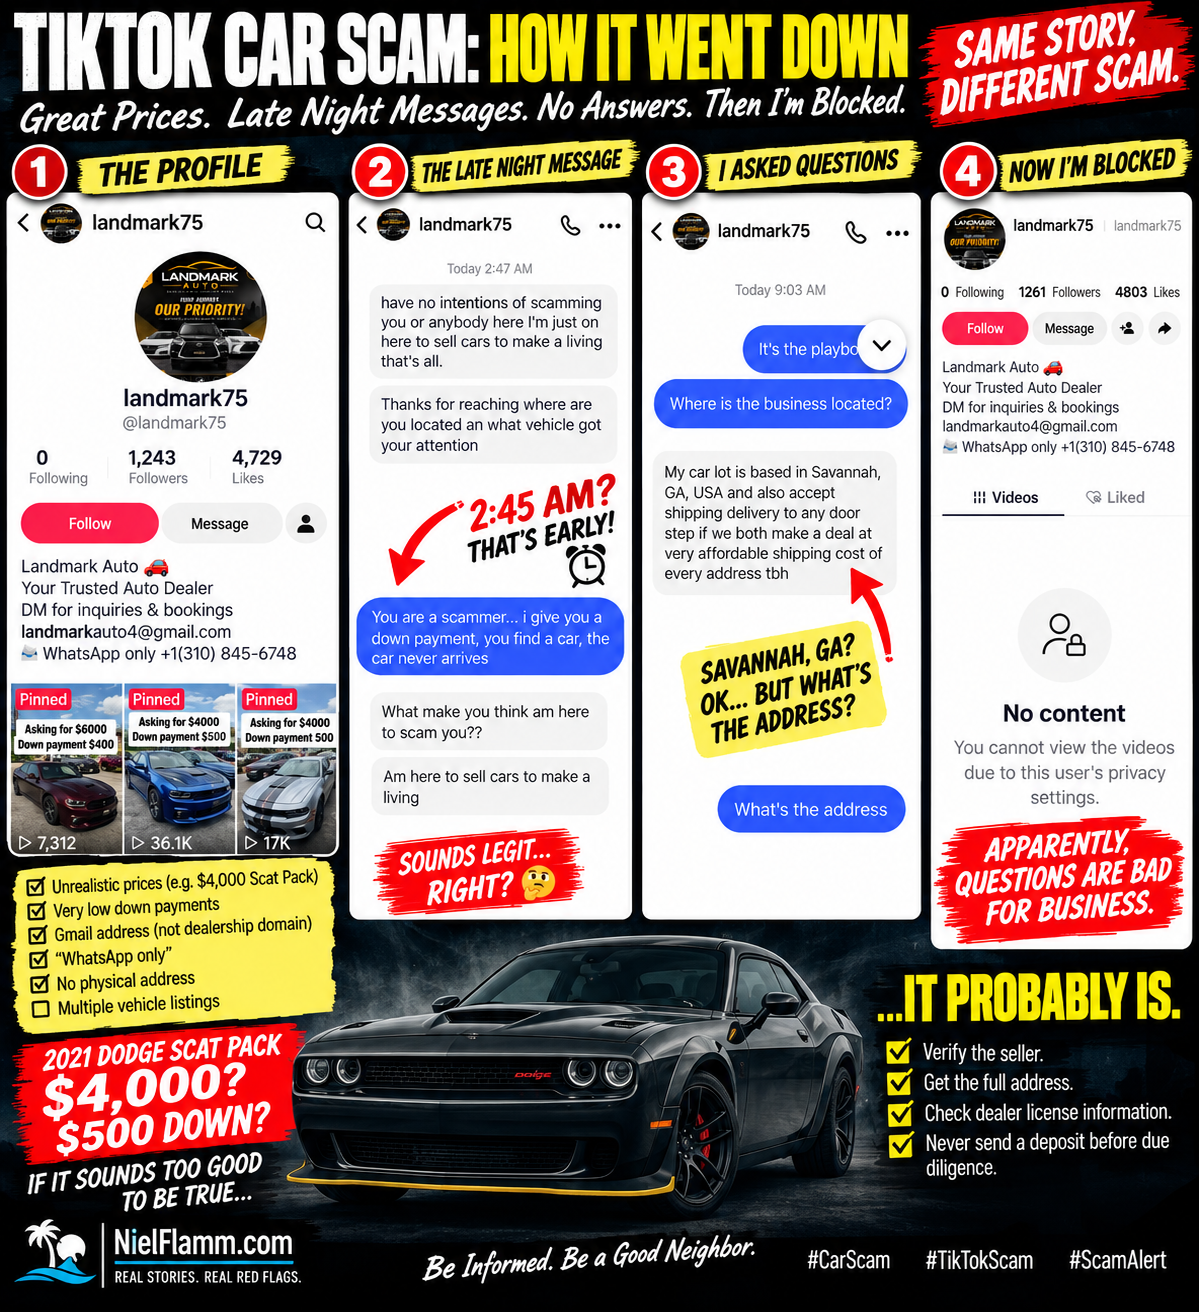
I've been documenting the TikTok account landmark75, which describes itself as “Landmark Auto” and has been advertising vehicles at prices that raised plenty of questions—including a supposed 2021 Dodge Scat Pack with 45,000 miles for $4,000 with $500 down.
Then they contacted me.
At 2:45 in the morning.
They assured me:
“have no intentions of scamming you or anybody here I'm just on here to sell cars to make a living that's all.”
Great.
So I started asking questions.
Apparently, that was the problem.
🚗 I Asked Where the Dealership Was Located
This shouldn't have been difficult.
They told me:
Savannah, Georgia.
Okay.
I asked:
What's the address?
Not exactly an interrogation worthy of the FBI.
If you're operating a car lot and offering to sell and ship vehicles to customers, asking where the car lot is located seems like a fairly reasonable question.
I wanted information I could independently verify.
Then something interesting happened.
😂 Apparently I Asked One Question Too Many
Today I went back to the TikTok account.
The profile is still there.
At the time of my latest screenshot, it showed:
1,261 followers
4,803 likes
The bio still says:
“Landmark Auto 🚗”
“Your Trusted Auto Dealer”
It still lists a Gmail address.
It still says:
“WhatsApp only”
But now the videos are gone—from my view.
TikTok tells me:
“No content”
and:
“You cannot view the videos due to this user's privacy settings.”
Well, that's convenient.
The account that contacted me in the middle of the night and wanted to discuss selling me a vehicle apparently no longer wants me looking at its vehicle listings.
🚩 Let's Review the Timeline
This is what makes the progression interesting.
I saw vehicles advertised at unusually low prices and down payments.
I started documenting them.
The account contacted me.
I openly questioned whether the operation was legitimate.
They told me they had no intention of scamming anybody and were simply trying to make a living selling cars.
I asked where the business was located.
They gave me a city and state:
Savannah, GA.
I asked for the actual street address.
And now I can no longer view their TikTok content.
That's what I can document from my screenshots.
Whether TikTok's restriction reflects a block or another privacy setting, I can't determine that independently from this screen alone. But the result for me is the same:
I can't see their videos anymore.
🤔 That's an Interesting Way to Build Customer Confidence
Remember, their profile calls them:
“Your Trusted Auto Dealer”
Trust generally works better when customers can verify things.
If I were considering sending hundreds of dollars to an online vehicle seller, I'd want some pretty basic information:
Where is your dealership?
What's the street address?
What's your legal business name?
What's your dealer license number?
What's the VIN?
Can I inspect the vehicle?
Can someone I choose inspect it?
Can I call the dealership using a number I find independently?
Can you provide the complete purchase and financing terms?
Those aren't hostile questions.
Those are car-buying questions.
🚩 Blocking Questions Doesn't Answer Questions
Here's the important part.
Not being able to view the account's videos doesn't, by itself, prove that every listing was fraudulent.
But it also doesn't resolve a single concern I raised.
The $4,000 Scat Pack doesn't suddenly make more sense.
The $500 down payments don't become independently verified.
“WhatsApp only” doesn't establish a dealership.
“Savannah, GA” still isn't a street address.
And preventing a skeptical viewer from seeing the listings doesn't provide any of the documentation that could establish the seller's legitimacy.
It simply prevents that viewer from continuing to examine the content.
😂 Apparently Due Diligence Is Bad for Business
Maybe my mistake was asking too many questions.
Perhaps I should have said:
“$500 down? Fantastic! Where do I send it?”
Instead, I committed the unforgivable sin of online car shopping.
I asked:
“What's the address?”
Oops.
🏡 This Is Exactly Why I Say: Be a Good Neighbor
Someone else might see a beautiful car and an affordable down payment and think they've finally found a solution.
Maybe their credit isn't great.
Maybe their current vehicle just died.
Maybe they desperately need transportation to keep their job.
That person doesn't need ridicule.
They need someone willing to say:
“Before you send that money, let's verify this.”
Check the dealership.
Check the address.
Check the VIN.
Check the dealer license.
Check the title.
Check the vehicle's market value.
Call a phone number obtained independently.
And never let someone rush you into sending a deposit before you've verified who you're dealing with.
I'll Keep Asking Questions
I said I'd continue engaging with this account for as long as I was able.
Apparently, “as long as I was able” didn't last very long.
😂
But there's a useful lesson here.
When you're considering sending money to someone online, don't judge legitimacy by how confidently they tell you they're legitimate.
Judge it by how easily you can independently verify their claims.
And if asking ordinary questions suddenly ends the conversation?
Don't stop asking questions.
Just stop sending money.
Follow the continuing scam series at NielFlamm.com/blog.