

The PayPal Scam That Apparently Scheduled Its Own Reminder on My Phone
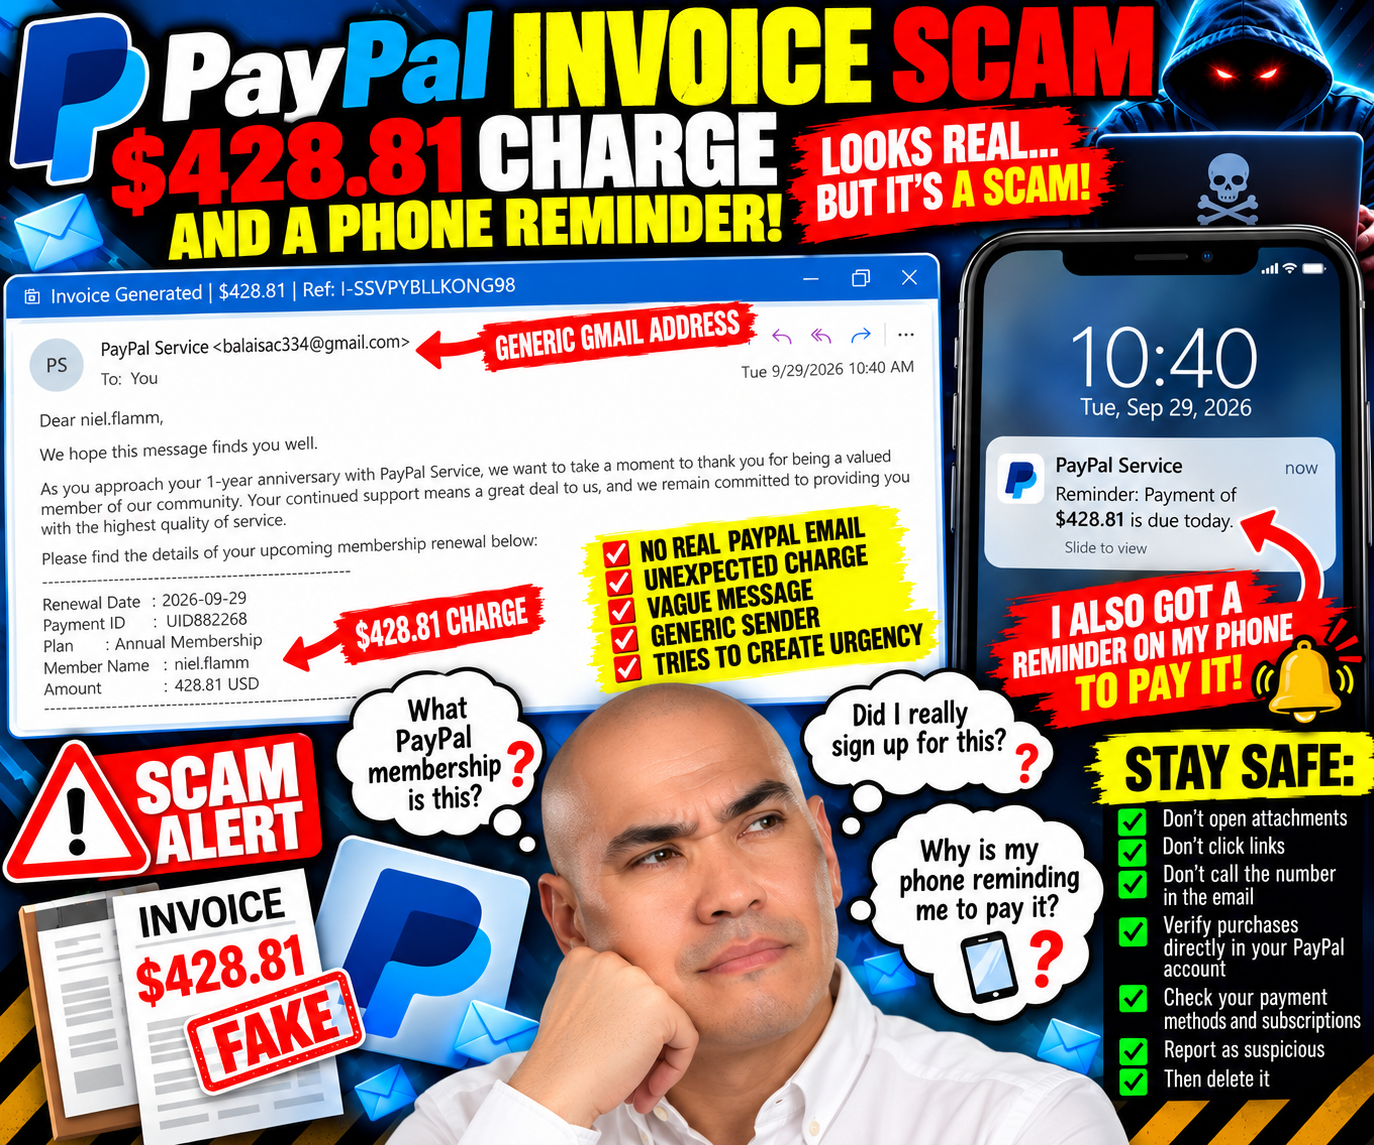
The scammers are getting ambitious.
Lately, I’ve been getting mystery order emails with almost no information. Apparently, somebody decided those weren't convincing enough.
This time, I received what looks like a much more complete invoice.
And then something happened that made this one especially interesting:
I also got a reminder on my phone telling me to pay it.
That will get my attention.
Apparently, I Have a $428.81 “PayPal Service” Membership
The subject line reads:
“Invoice Generated | $428.81 | Ref: I-SSVPYBLLKONG98”
Right away, the email gives me something the previous mystery emails didn't: a specific dollar amount.
$428.81.
The sender's display name says “PayPal Service.”
Sounds official.
Except the actual email address shown next to it is:
There's my first rather large red flag.
If someone is going to impersonate a major financial company, using a random Gmail account while displaying “PayPal Service” isn't exactly subtle.
Happy Anniversary to Me!
According to the email, I'm approaching my one-year anniversary with “PayPal Service.”
How thoughtful.
It thanks me for being a “valued member” and tells me about my upcoming membership renewal.
The supposed details include:
Renewal Date: September 29, 2026
Plan: Annual Membership
Member Name: niel.flamm
Amount: $428.81 USD
The message claims the membership will automatically renew using my saved payment method.
There's just one little problem:
What PayPal annual membership?
That question matters more to me than the email's professional appearance.
🚩 Then Comes the Phone Number
The message tells me that if I want to update my billing information, change my plan, or ask questions, I should call:
1 (816) 372-4805
And there it is.
The email creates the problem:
You're about to be charged $428.81!
Then it conveniently provides the solution:
Call us!
That's exactly when I don't call the number in the email.
If I were concerned about an actual PayPal transaction, I'd open PayPal independently—not use contact information supplied by the message that created the emergency.
But This One Had an Extra Trick
What really got my attention wasn't just the email.
I also got a reminder on my phone to pay it.
That makes the experience considerably more convincing.
Now I'm not simply looking at an unsolicited email.
My phone is also reminding me about the supposed payment.
For a moment, that can create an entirely different psychological reaction:
Wait. Did I actually schedule this?
Did I forget about something?
Did my phone pull this from somewhere legitimate?
That's precisely why I found this one worth documenting.
A reminder appearing on my phone doesn't independently authenticate the underlying invoice. Depending on the phone, email, calendar, assistant, and account settings involved, information from messages can sometimes surface elsewhere automatically.
The reminder made the claim feel more legitimate.
It didn't make the sender's Gmail address disappear.
This Is Why I Look at the Actual Sender
A familiar logo can be copied.
A company name can be typed into an email.
“PayPal Service” can appear as a display name.
A professional-looking invoice number can be invented.
An amount like $428.81 feels specific enough to seem real.
Even a reminder appearing on my phone can make the situation feel more urgent.
But I keep coming back to the basics.
Who actually sent this?
In this case, the screenshot shows:
PayPal Service balaisac334@gmail.com
That's enough for me to stop interacting with the message and verify everything independently.
The Weird Details Keep Coming
Other things make me skeptical.
The email refers repeatedly to “PayPal Service” as though I'm paying for an annual membership.
There's also some mangled text:
“we’re here to help.”
Then the signature lists:
PayPal Service
12014 Copernicus Ave
Bakersfield Ca 93312 Usa
Again, you don't need to investigate those details through the email itself.
That's an important distinction.
I don't have to prove every element is fake before deciding not to trust an unsolicited message.
I can independently verify the account that is said to owe the money.
Don't Let a $428.81 Charge Create Panic
This type of message depends on urgency.
Four hundred twenty-eight dollars and eighty-one cents isn't pocket change.
Someone sees that amount and thinks:
Please stop this charge now.
That's when judgment can disappear.
Instead, I'd do the boring thing.
Open PayPal independently.
Check my activity.
Check automatic payments and subscriptions.
Check the payment methods attached to the account.
If necessary, contact PayPal using contact information obtained independently from PayPal—not the telephone number in the suspicious email.
If the $428.81 transaction isn't there, I'm certainly not going to call a stranger and give them account information so they can “cancel” it.
The Phone Reminder Is the Best Part of This One
Not because it's funny—although something is amusing about a suspicious invoice apparently getting promoted to my personal to-do list.
It matters because it shows how context can influence trust.
An email alone?
Suspicious.
An email plus a phone reminder?
Suddenly my brain gets another signal suggesting that maybe this is something I previously knew about.
That's when I have to separate familiarity from verification.
My phone displaying information doesn't prove it’s legitimate.
A professional-looking invoice doesn't prove it's legitimate.
The exact amount doesn't prove it's legitimate.
The reference number doesn't prove it's legitimate.
And putting “PayPal Service” next to a Gmail address certainly doesn't prove it's PayPal.
Be a Good Neighbor
This is another one worth showing to someone who isn't as comfortable spotting suspicious messages.
Don't just tell them:
“That's obviously fake.”
Show them why you're suspicious.
Point to the sender address.
Ask whether they actually have the membership being described.
Show them how to open the real company's app or website on their own.
Explain why they shouldn't call the telephone number supplied by the same message claiming there's a problem.
And if their phone generates a reminder from the message, explain something else:
A reminder is a reminder. It isn't authentication.
The scammers don't need everybody to believe their story.
They need one person to see $428.81, panic, and make that phone call.
As for my alleged PayPal Service anniversary?
I don't think I'll be celebrating.
I won’t be sending a card.

Apparently, the Scammers Still Haven’t Started Writing Emails
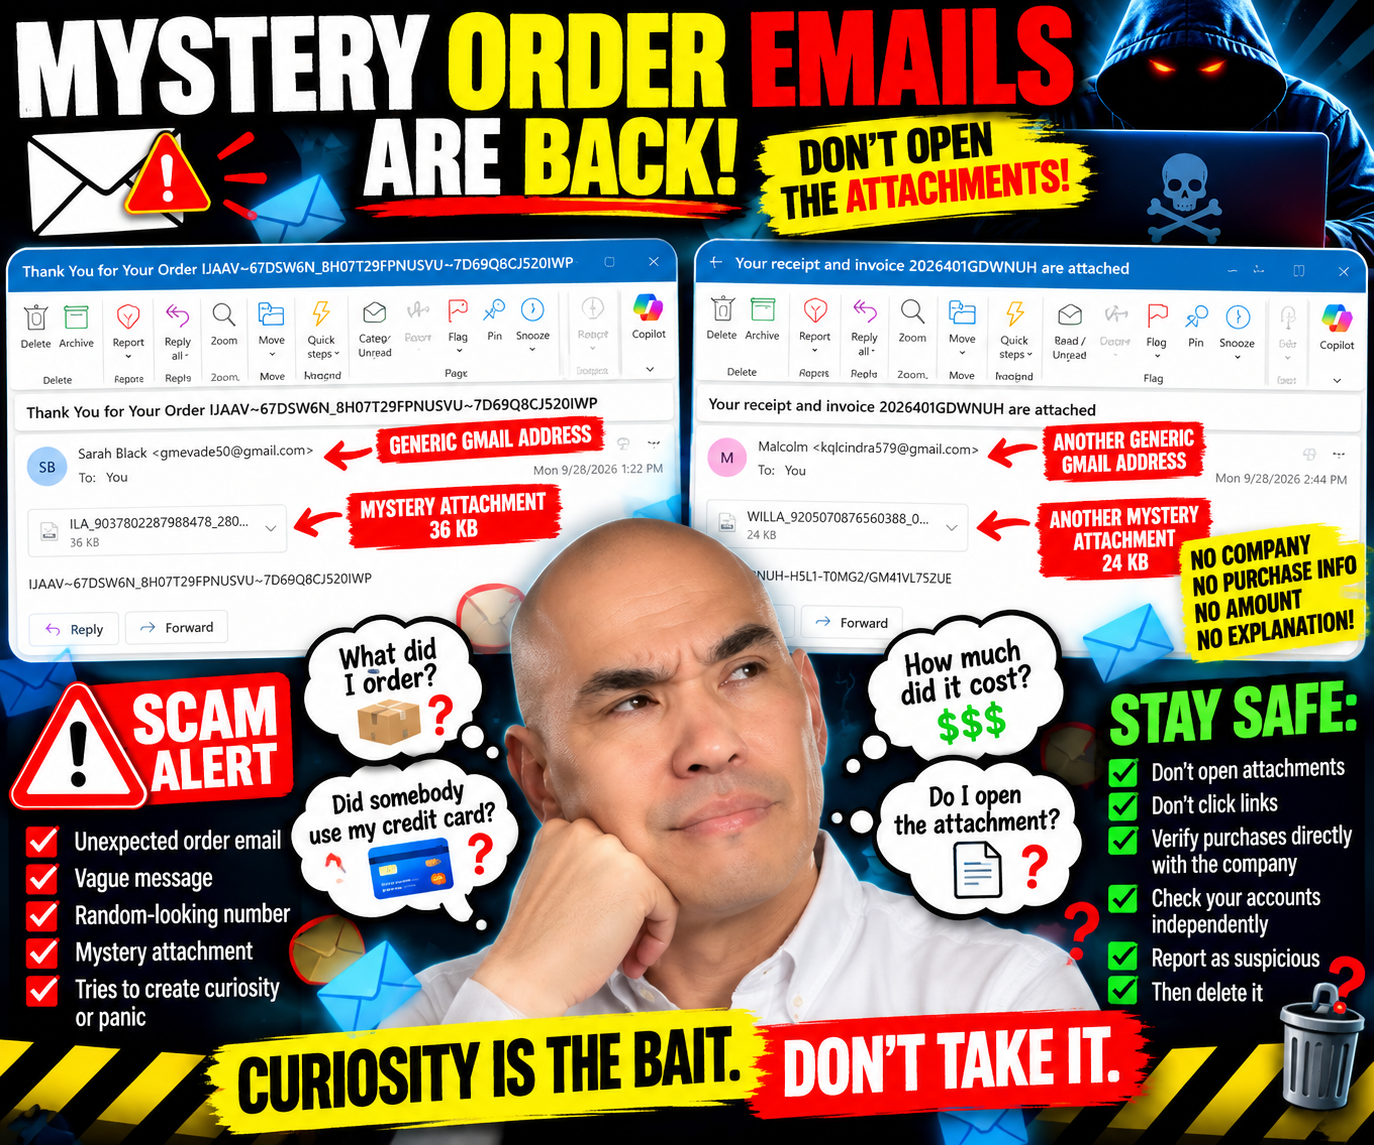
Just when I thought the mystery-order-email department might have run out of ideas, two more showed up.
Apparently, writing an actual email is still too much work.
No company introduction. No explanation of what I supposedly purchased. No recognizable merchant. No dollar amount. No useful order details.
Just a mysterious attachment and the digital equivalent of:
“You bought something. Trust me. Open this.”
Yeah, I’ll get right on that.
Mystery Order #1: Thank You for…Whatever I Ordered
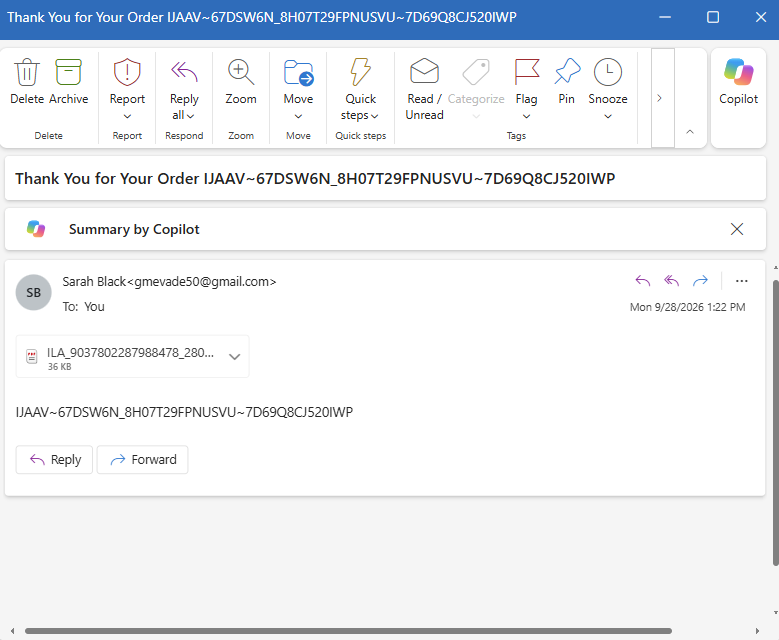
The first email arrived with this rather catchy subject line:
“Thank You for Your Order IJAAV~67DSW6N_8H07T29FPNUSVU~7D69Q8CJ520IWP”
Well, that certainly clears things up.
It came from someone named Sarah Black, using a Gmail address.
Inside the email?
Almost nothing.
There's another long collection of letters and numbers and a 36 KB attachment.
That's it.
No store.
No product.
No purchase price.
No credit card information.
No shipping address.
No customer-service information.
Nothing explaining what this alleged order actually is.
To see what I bought, I need to open the attachment.
Nope.
Mystery Order #2 Arrives the Next Day
Then another one arrived.
This time the subject was:
“Your receipt and invoice 2026401GDWNUH are attached”
Now we're getting fancy.
We've upgraded from a mysterious “order” to a mysterious receipt AND invoice.
This one came from someone named Malcolm, also using a Gmail address.
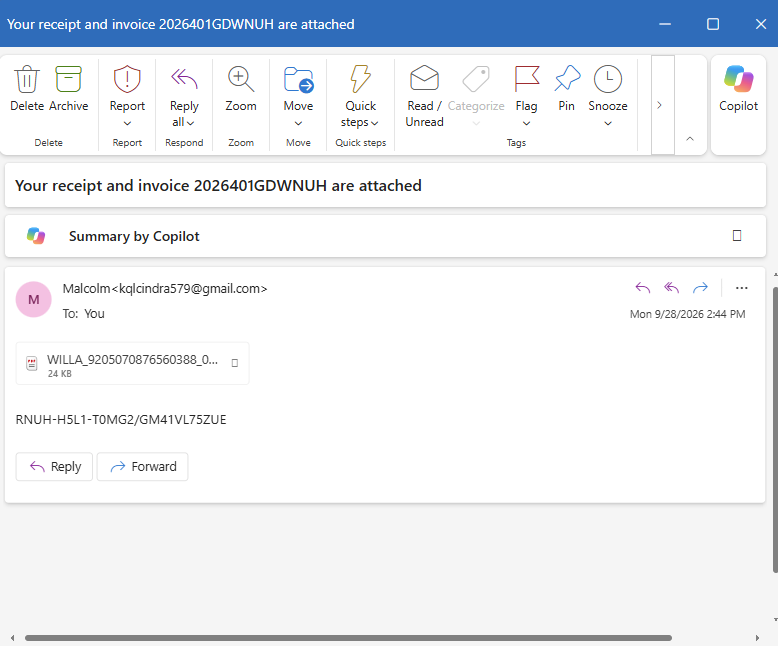
The body of the email contains another random-looking code:
RNUH-H5L1-I0MG2/GM41VL75ZUE
And, naturally, there's another attachment—this one is 24 KB.
Again, the message doesn’t identify a recognizable business.
No explanation of what I purchased.
No price.
No payment information.
No description.
Just an attachment.
🚩 The Attachment Is Still the Email
I've written about this before, and apparently somebody out there wants to provide me with additional examples.
These messages aren't really trying to communicate anything useful.
The attachment is the email.
Everything surrounding it seems designed to create just enough curiosity or concern to make me open it.
Maybe my first reaction is:
What did I order?
Then:
Did somebody use my credit card?
Then:
How much did they charge me?
And finally:
I’d better open this invoice and find out.
That's precisely the reaction I don't want to have.
If I don't recognize a purchase, my first move isn't to open a mystery attachment from an unfamiliar Gmail account.
I'm going directly to my bank, credit-card company, retailer account, or whatever legitimate service supposedly processed the transaction.
Curiosity Can Be the Bait
I haven't opened either attachment, so I don't know what's inside them.
I can't claim they're malware without examining them.
And that's really the point.
I don't need to know what's inside.
Neither message gives me a reason to take that risk.
If I really made a purchase, I can verify it independently.
If there's an unauthorized charge, I can see it through my financial institution.
If a legitimate company needs to contact me about an order, I can go directly to that company's website or app rather than following instructions contained in an unsolicited email.
Opening a mystery file shouldn't cost me to find out whether I supposedly spent money.
Two Emails, Same Basic Formula
These arrived on consecutive days from different Gmail addresses with different names, different order numbers, and different attachments.
But look at the structure:
Unexpected purchase notification → vague message → meaningless-looking number → attachment → curiosity.
That's what catches my attention.
They don't need me to believe the email for very long.
They need me to think:
“What the heck did I buy?”
…and click.
Don't Let the Email Create the Emergency
That's another lesson I've learned from documenting these messages.
A suspicious email shouldn't create a problem and then dictate how I investigate it.
If an email tells me there's an order I don't recognize, I'll check my accounts independently.
If it says there's a PayPal charge, I'll log in to PayPal independently.
If it says there's a credit-card transaction, I'll check that card myself.
If it claims there's an Amazon order, I'll open Amazon myself.
I don't need the mystery attachment.
Be a Good Neighbor
These emails may look ridiculous to someone who's seen hundreds of them.
Not everyone has.
Someone else might see “Thank You for Your Order” and immediately panic.
Maybe they're worried someone stole their credit card.
Maybe they're afraid hundreds of dollars just disappeared from their checking account.
Maybe they can't remember whether they ordered something.
That's when it's worth saying:
Don't open the attachment yet. Let's verify the supposed purchase another way.
Help someone check the real account.
Show them how to inspect the sender.
Explain why an unexpected attachment deserves caution.
Report suspicious messages.
Then delete them.
Because apparently the scammers still haven't started writing emails.
But they certainly haven't stopped sending attachments.

The “Bank Repo” Story Falls Apart: That’s Not How Vehicle Repossession Works
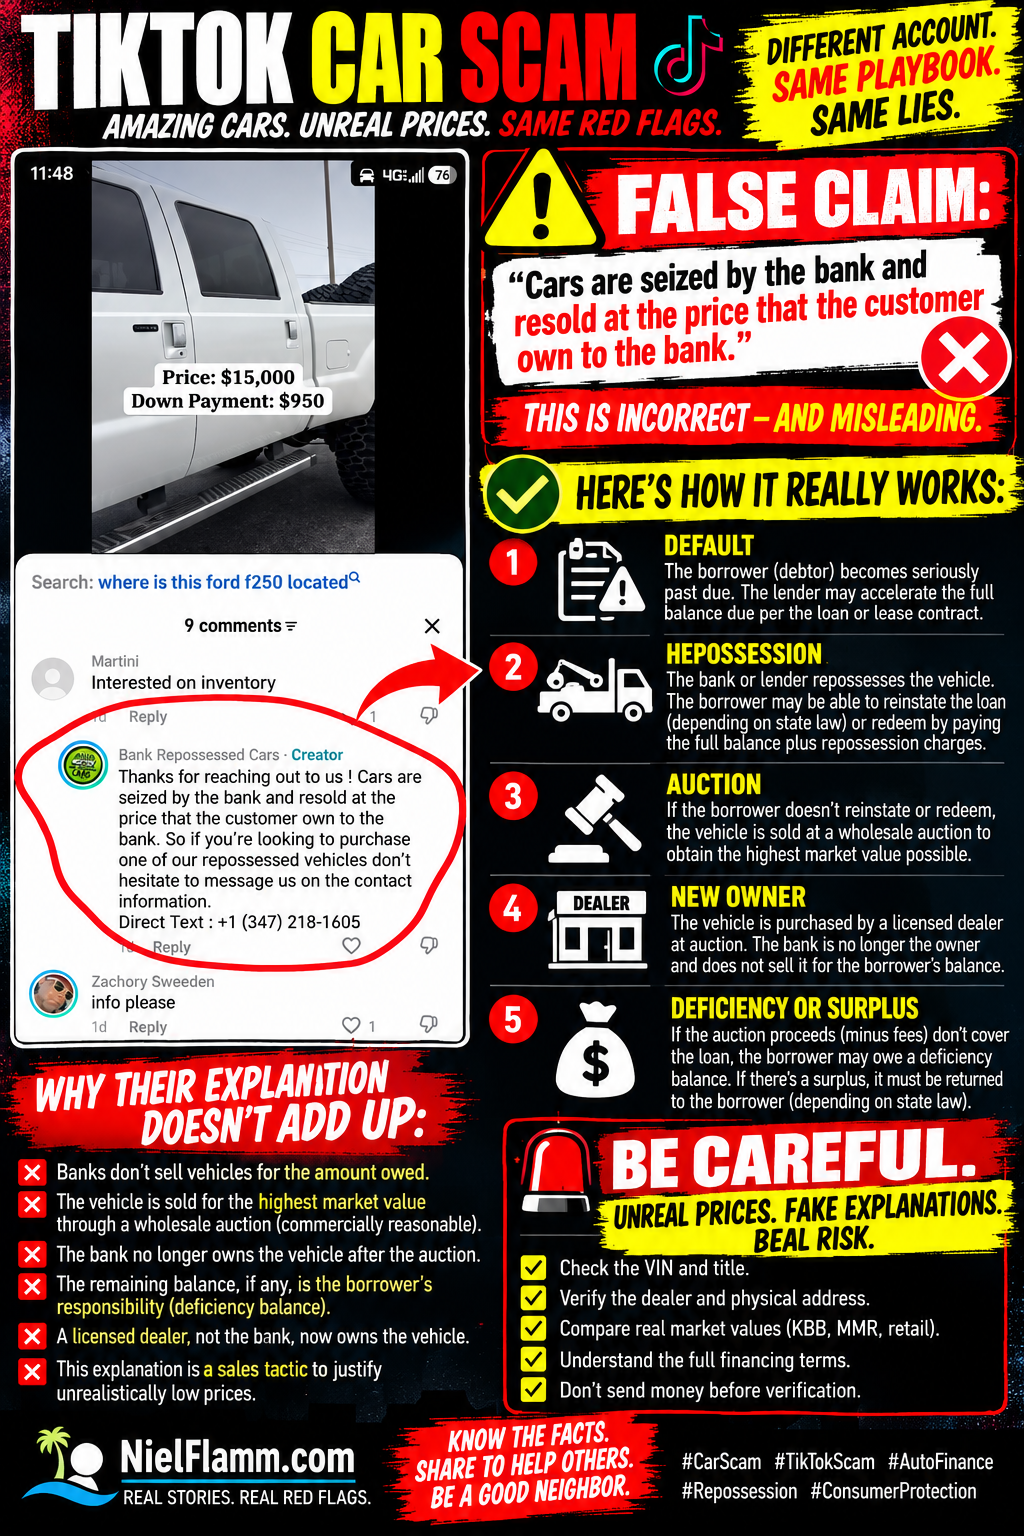
I've been following another TikTok account advertising remarkably inexpensive “bank repossessed” vehicles. This time, I noticed something in the comments that deserves its own post.
The account responded to someone interested in a vehicle with this explanation:
“Cars are seized by the bank and resold at the price that the customer own to the bank.”
In other words, the account appears to be telling potential buyers that banks repossess vehicles and then sell those vehicles for whatever balance the previous customer owed.
That's not an accurate description of the normal repossession and disposition process.
This is an area where I have quite a bit of professional experience.
First, Let's Talk About What Repossession Actually Is
A bank, credit union, captive automotive finance company or other lender doesn't generally repossess a vehicle because it suddenly wants to become a discount used-car dealership.
The vehicle is collateral securing a financial obligation.
When a borrower—often called the debtor—defaults under the retail installment contract or lease, the lender may have the contractual and legal right to repossess the vehicle. Exactly when that can happen and what notices are required depend on the contract and state law. The FTC notes that in many states, a lender may repossess once the borrower defaults, and missed payments are a common form of default. Consumer Advice
State laws vary significantly, so I'm not presenting one procedure as universal across all 50 states.
But the TikTok explanation isn't how the basic economics work.
Reinstatement and Redemption Come Before the Sale
After repossession, the borrower may still have rights.
Depending upon state law and the contract, a borrower may have an opportunity to reinstate the loan by bringing the delinquency current and paying allowable repossession-related expenses.
In other circumstances, the borrower may have the right to redeem the vehicle by paying the full amount required, along with applicable repossession expenses.
The CFPB specifically distinguishes these concepts. Some states permit curing or reinstating a loan after repossession, while redemption generally involves paying the full loan amount plus repossession costs before the vehicle is sold. Consumer Financial Protection Bureau
So repossession doesn't automatically mean:
Bank takes car → bank reviews the remaining balance → a random person gets a screaming deal.
There's a process.
Then Comes the Disposition of the Vehicle
If the borrower doesn't reinstate or redeem where those options apply, the lender may dispose of the collateral.
F
In the automotive finance world, repossessed vehicles commonly move through wholesale channels, including dealer auctions. But to be precise, federal guidance notes that a lender can sell a repossessed vehicle through a public or private sale, depending on applicable law and circumstances. Consumer Advice
Under Article 9 of the Uniform Commercial Code, every aspect of a secured creditor's disposition of collateral must be commercially reasonable. A sale may qualify when it's conducted in the usual manner in a recognized market, at the prevailing market price, or in accordance with reasonable commercial practices among dealers in that type of property. Legal Information Institute
That's an extremely important distinction.
The objective isn't:
“Bob owes $5,850, so let's sell Bob's $35,000 car for $5,850.”
The unpaid loan balance and the vehicle's market value are two different numbers.
That's Where the TikTok Explanation Really Falls Apart
Think about the implications of what this account is saying.
Suppose someone financed a $60,000 vehicle.
Years later, the vehicle is still worth $30,000.
But the borrower happens to owe only $6,000 when the vehicle is repossessed.
According to the explanation in this TikTok comment, the bank would essentially resell the vehicle for what the customer owed.
Why would a lender voluntarily turn a $30,000 asset into $6,000?
That's not how a commercially reasonable disposition works.
The vehicle is sold, the proceeds are applied according to the applicable rules, and then the account is reconciled. Under UCC Article 9, reasonable disposition expenses generally come out of the proceeds, followed by satisfaction of the secured obligation and certain other permitted claims. Legal Information Institute
And then we find out whether there's a deficiency or a surplus.
What's a Deficiency Balance?
Here's where my former world comes into play.
Suppose the borrower owes:
$25,000
The vehicle is repossessed and ultimately sells for:
$18,000
There are also allowable repossession, storage, auction or other disposition expenses.
After applying the proceeds, money is still owed.
That's the deficiency balance.
The CFPB defines a deficiency as the difference between the amount remaining on the loan, plus applicable repossession fees, and what the lender receives from selling the vehicle. Depending on state law and whether the lender complied with applicable requirements, the borrower may remain responsible for that balance. Consumer Financial Protection Bureau
The reverse can also happen.
If the disposition produces more money than the debt and allowable expenses, there can be a surplus, which generally must be returned to the debtor. Legal Information Institute
That's another reason the statement in the TikTok comment doesn't make sense.
The balance owed doesn't establish the vehicle's resale price.
How Do I Know This?
This isn't something I learned yesterday from Google.
In a previous professional life, I worked for a captive automotive finance company—the finance subsidiary of a major European import automobile manufacturer.
I held several different roles there.
I started in primary collections, working delinquent retail contracts at different stages and statuses.
I managed an inbound customer-service team.
I helped set up a predictive dialer.
I worked in retail credit, extending credit through franchised dealership partners.
And one of my other roles was in the loss/deficiency area.
That meant dealing with total losses, collecting total-loss and repossession deficiency balances, and handling post-repossession calls after the lender had taken possession of the collateral.
So when I read:
“Cars are seized by the bank and resold at the price that the customer owe to the bank.”
I don't just see questionable grammar.
I see an explanation of automotive finance that doesn't match the process I spent years working with.
There's Another Problem: “Bank Repossessed” Doesn't Explain a Huge Discount
This matters because the account uses the repossession story to explain prices that appear dramatically below normal market values.
If someone tells me:
“It's cheap because it's bank repossessed.”
That's not enough.
Repossession doesn't erase the market value of an automobile.
Neither does the word auction.
Wholesale values are generally lower than retail values—that's how dealers can acquire inventory, recondition it, cover overhead, and hopefully earn a profit.
But wholesale isn't synonymous with whatever the previous borrower owed.
Those are completely different concepts.
That's why I've been comparing these TikTok prices with KBB retail values and, when reliable vehicle-specific information is available, wholesale/MMR-type benchmarks.
And About That $15,000 F-250...
The video containing this comment shows a Ford F-250 advertised at:
Price: $15,000
Down payment: $950
The TikTok search prompt even asks:
“where is this ford f250 located”
Before anybody sends $950, I'd want a lot more information.
What's the year?
Trim?
Engine?
Mileage?
VIN?
Title status?
Accident history?
Physical location?
Dealer's legal business name?
Dealer license number?
Who actually owns the truck?
What are the complete financing terms?
And if this vehicle was supposedly repossessed by a bank, I'd especially like to know how the seller obtained it and why its current price is what it is.
“Because that's what the previous customer owed” isn't a satisfactory explanation.
A Reputable Lender Has Another Obligation: Commercial Reasonableness
This part shouldn't be overlooked.
A lender can't necessarily dump repossessed collateral for an arbitrary amount and then simply hand the enormous difference to the former borrower as a deficiency.
The disposition must meet applicable legal requirements, including the UCC's requirement that it be commercially reasonable. Legal Information Institute
That protects more than the lender.
It matters to the borrower, too.
Imagine owing $30,000 on a vehicle worth $28,000.
If the lender could arbitrarily sell it to somebody for $5,000 and then demand approximately $25,000 from the borrower, that would create an obvious problem.
That's one reason the manner in which repossessed collateral is disposed of matters.
Be Careful When the Explanation Is Part of the Sales Pitch
I want to make an important distinction.
A questionable explanation in a TikTok comment doesn't, by itself, establish every fact about the person or account behind it.
But I can evaluate the statement they published.
And the statement that repossessed cars are simply resold “at the price that the customer owes to the bank” is materially inconsistent with how reputable lenders generally dispose of repossessed vehicles.
That's significant when that very explanation is being offered to people asking about unusually inexpensive automobiles.
It's one more reason I would verify everything independently before sending a deposit.
Don't rely on the seller to explain why the seller's incredible deal is legitimate.
Check the VIN.
Check the title.
Check the dealer.
Check the physical address.
Check the dealer license.
Check the market value.
Check the financing.
And if the explanation of how repossession works doesn't make sense?
Ask more questions—not fewer.
I've actually worked this process from collections through repossession deficiencies.
So this time, the TikTok algorithm wandered directly into my old office.
Have a question about repossessions, deficiency balances, automotive financing, or one of these suspicious social-media car offers? Reach out by DM or email me at niel@nielflamm.com.

Another “Bank Repossessed” TikTok Car Deal — And the Phone Numbers Don’t Even Match
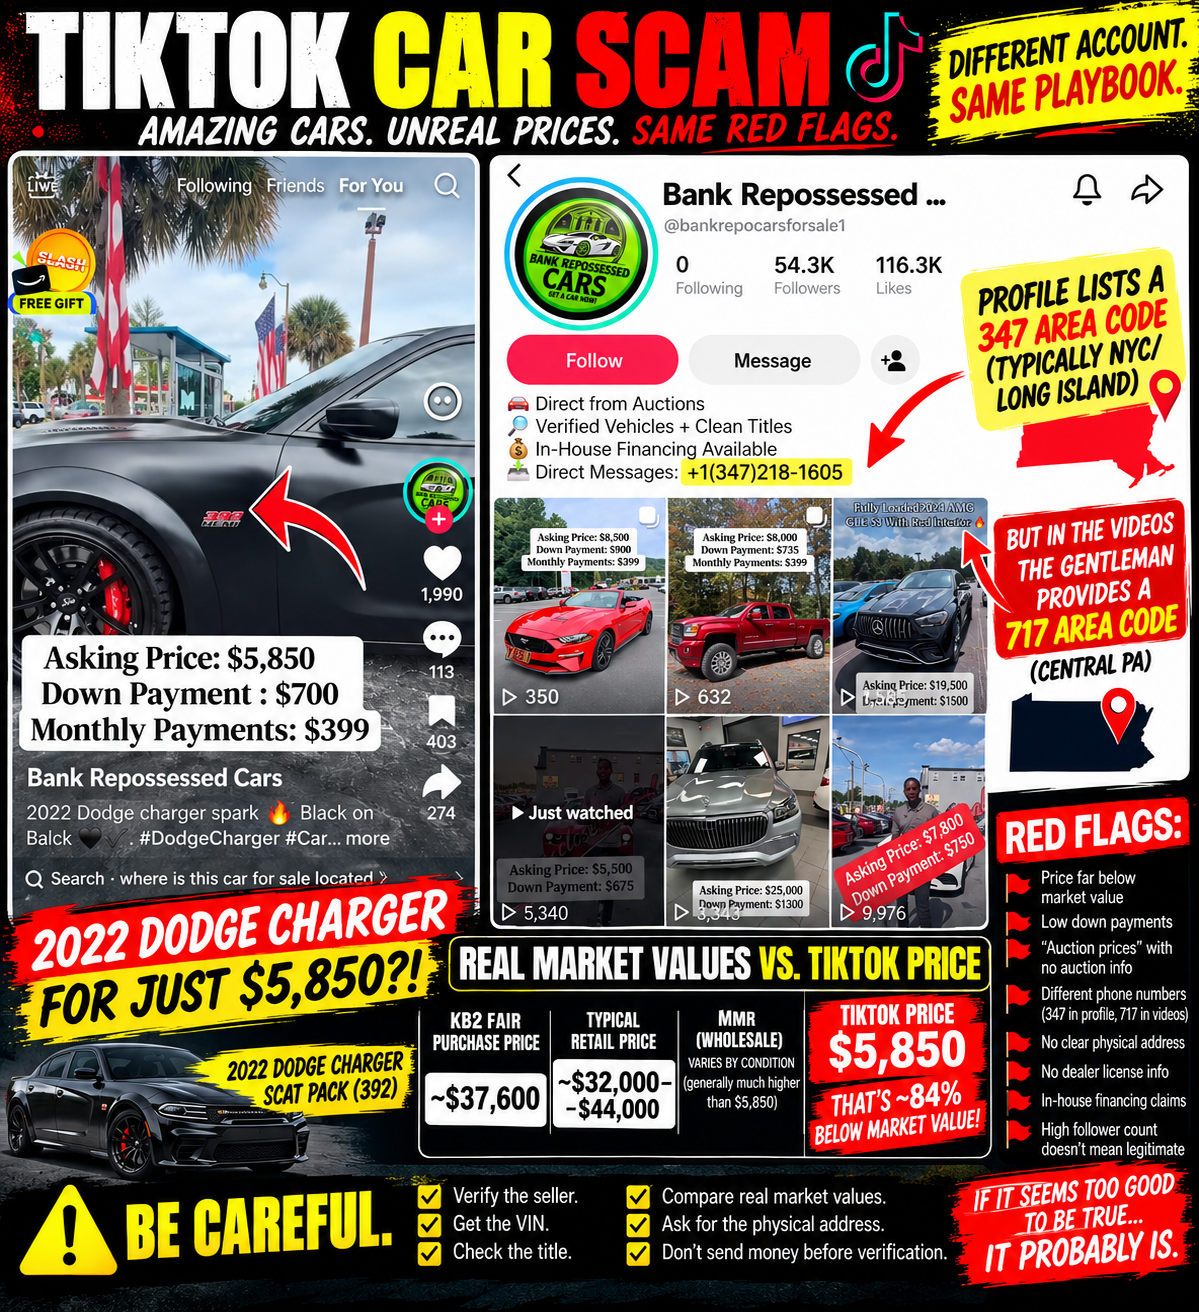
TikTok apparently still thinks I need a ridiculously inexpensive performance car.
The latest account to appear in my feed calls itself “Bank Repossessed Cars” and uses the handle @bankrepocarsforsale1.
At the time of my screenshot, the account had:
54,300 followers.
116,300 likes.
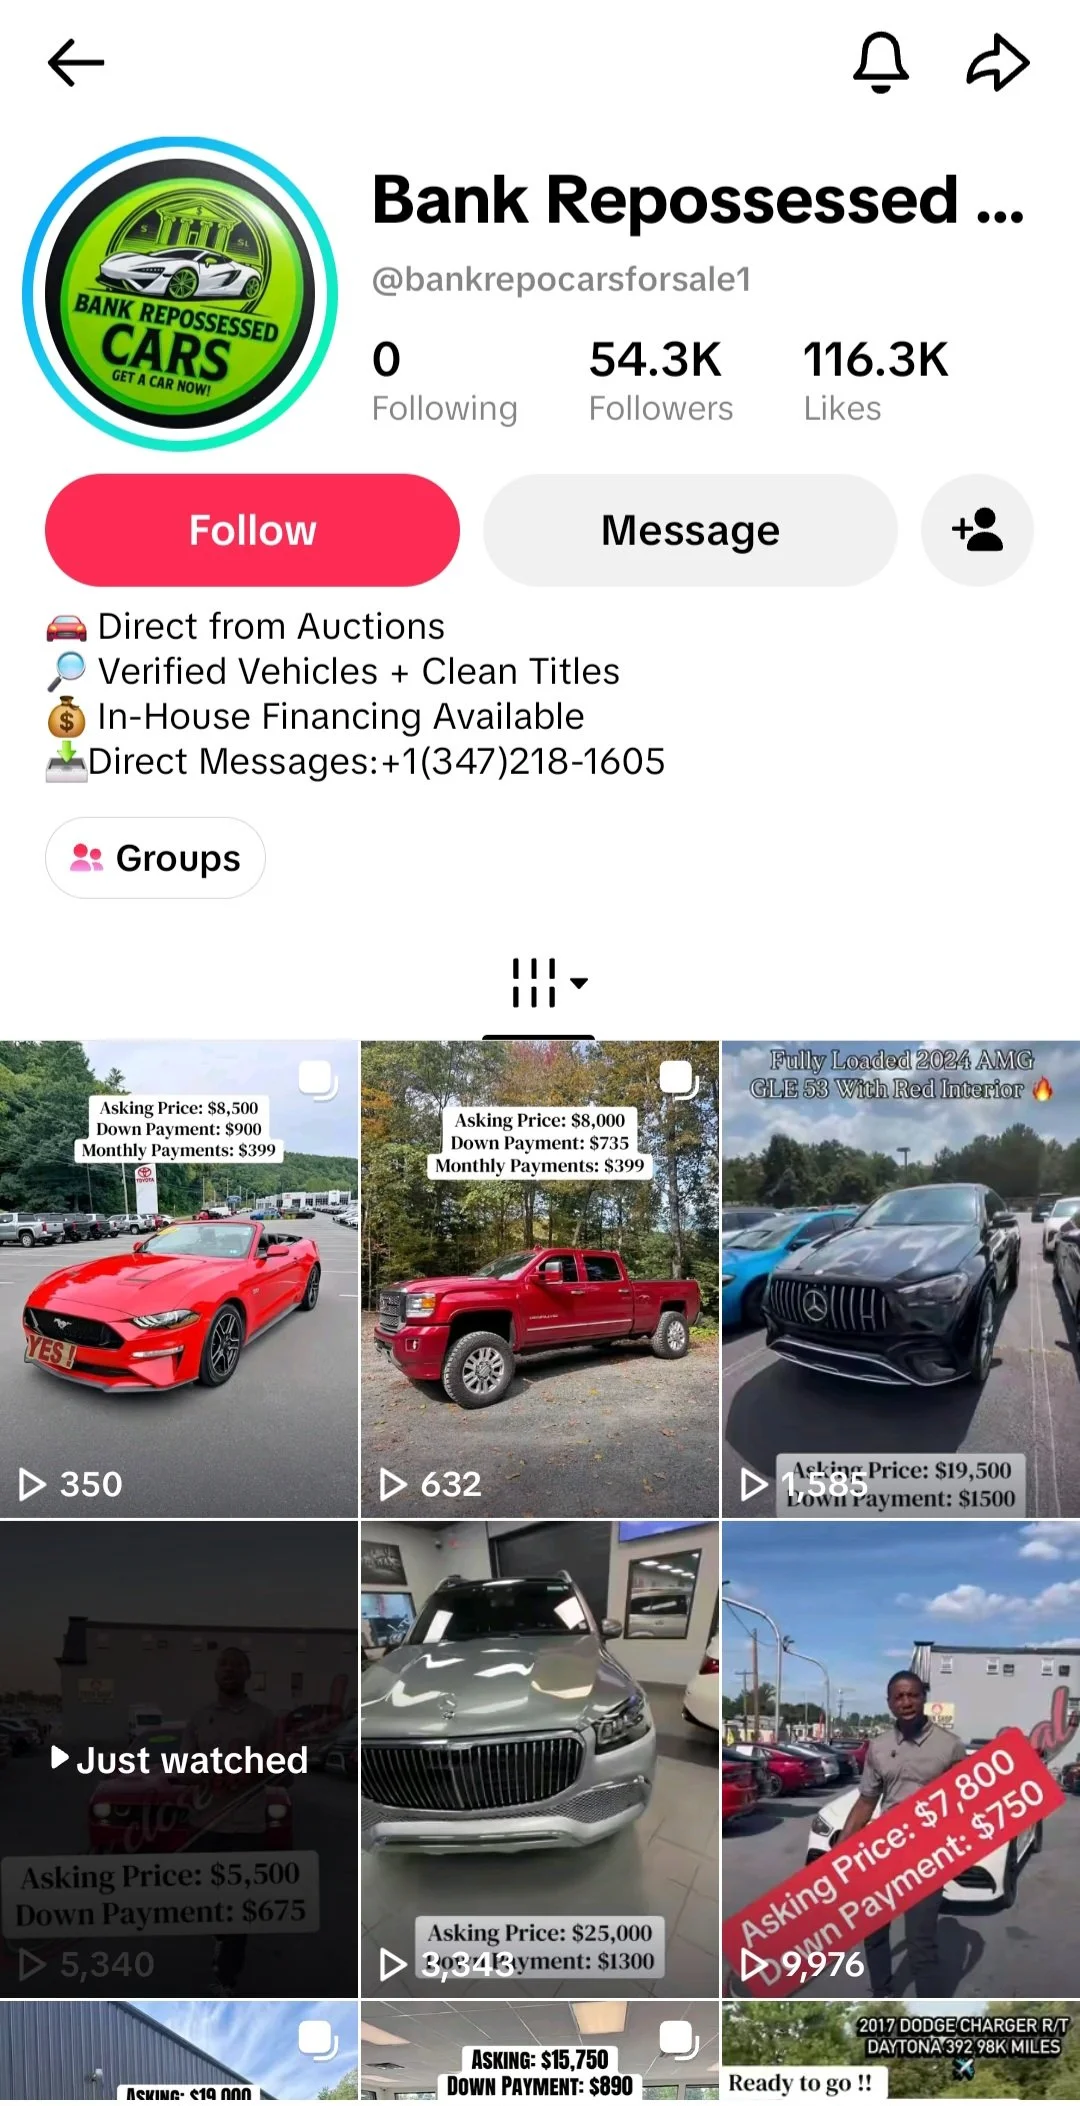
That's substantially larger than several of the questionable car accounts I've written about before.
The profile says:
🚗 Direct from Auctions
🔎 Verified Vehicles + Clean Titles
💰 In-House Financing Available
And then there's a telephone number for direct messages:
+1 (347) 218-1605
Sounds impressive.
Then I started watching the videos.
And once again, I have questions.
🚗 Today's Deal: A 2022 Dodge Charger for $5,850
The video that caught my attention shows what is described as a 2022 Dodge Charger with the following offer:
Asking Price: $5,850
Down Payment: $700
Monthly Payments: $399
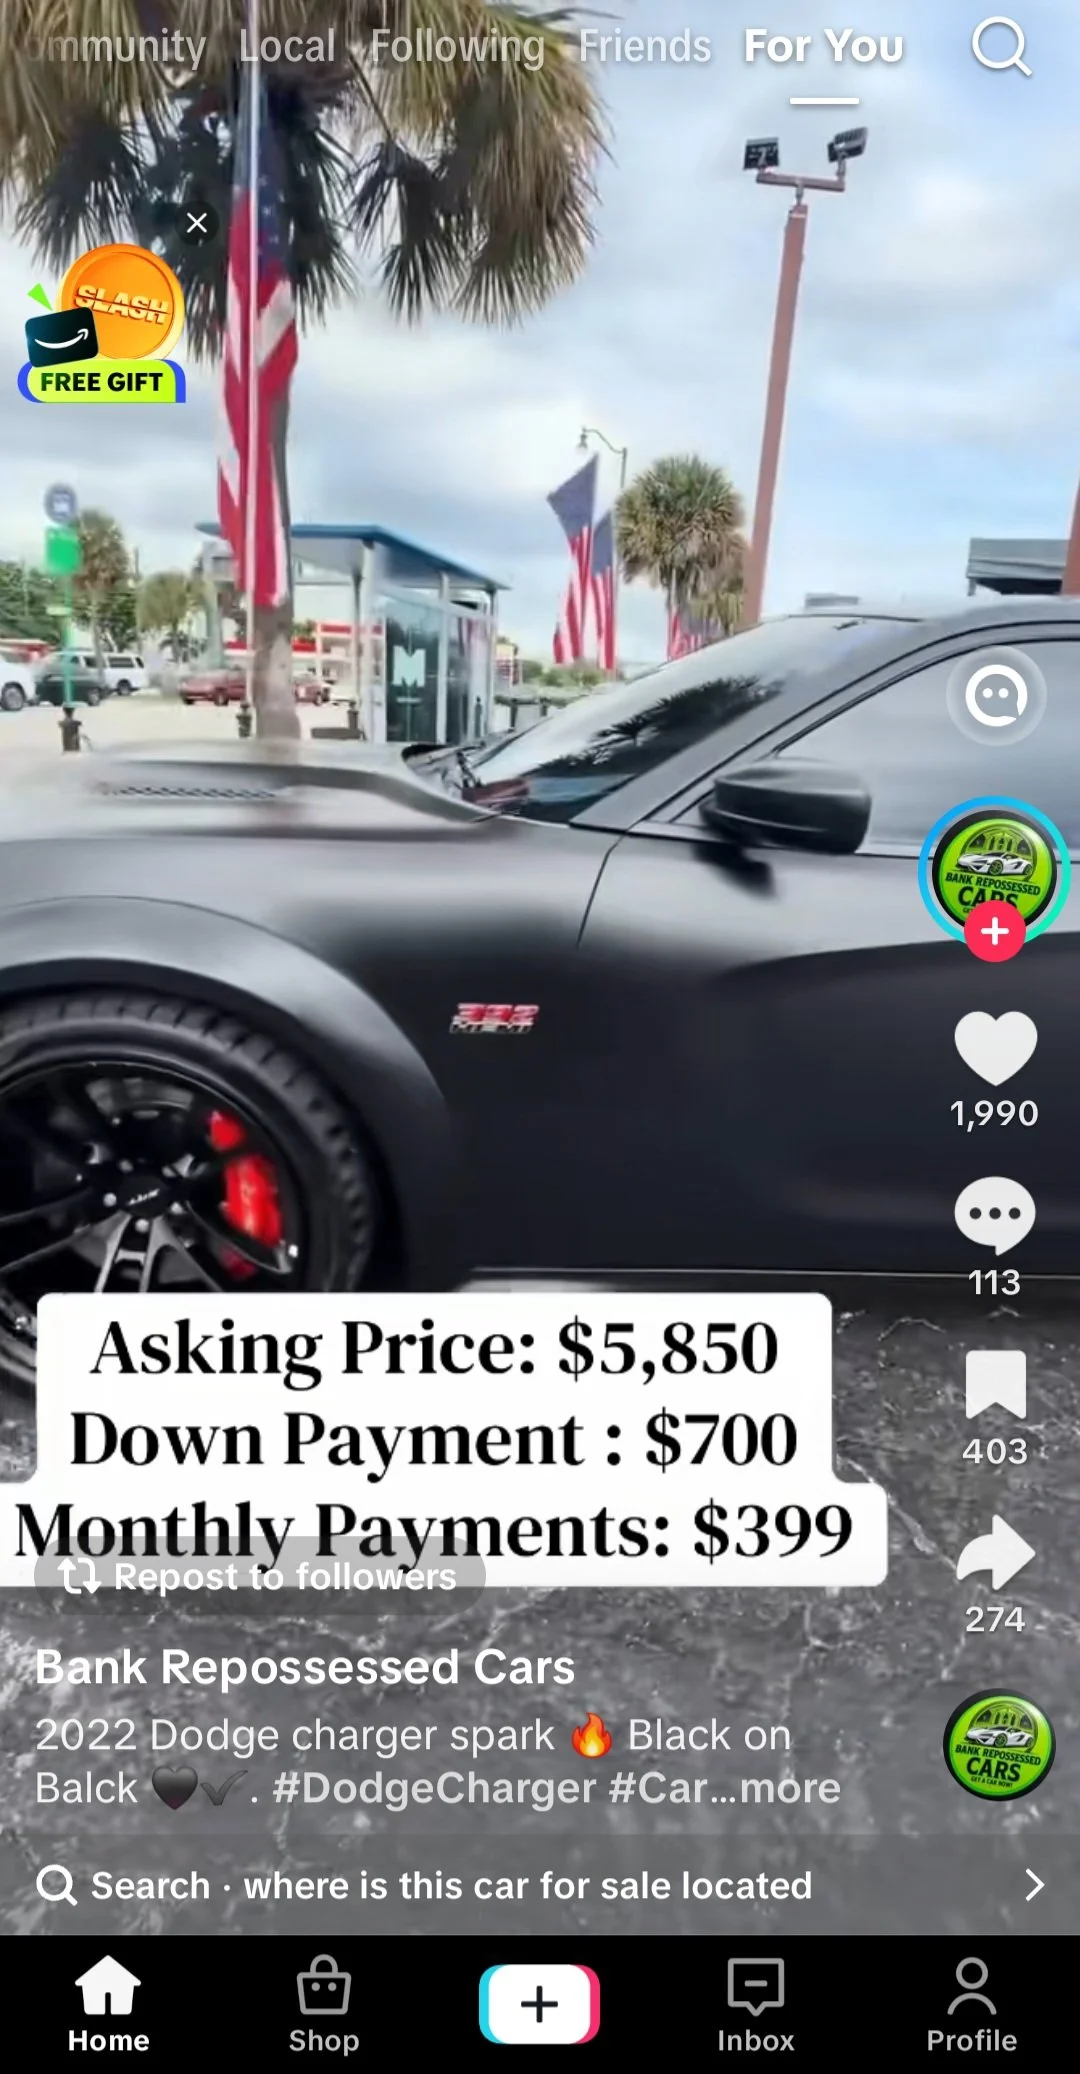
The caption describes it as a “2022 Dodge Charger spark”, although the vehicle shown appears to carry a 392 badge.
If this is actually a 2022 Charger Scat Pack/392, that $5,850 advertised price deserves a very close look.
Why?
Because the market numbers aren't even in the same neighborhood.
💰 Kelley Blue Book Says About $37,000 — Not $5,850
Kelley Blue Book currently puts the national Fair Purchase Price of a 2022 Dodge Charger Scat Pack around $37,600. KBB lists roughly $31,900 trade-in, $34,800 private-party, and $37,600 Fair Purchase Price for a good-condition example, while a Scat Pack Widebody is higher still at about $44,100 Fair Purchase Price. Exact values vary with mileage, condition, options, and location. Kbb.com
Edmunds tells a similar story: its current dealer-retail estimate for a regular 2022 Scat Pack ranges from roughly $32,300 in rough condition to $39,500 in outstanding condition. Edmunds
CARFAX's current listings put 2022 Charger Scat Packs at an average listing price of about $44,347, with its displayed range running roughly $36,747–$52,950. Carfax
TikTok?
$5,850.
That's roughly 84% below KBB's $37,600 Fair Purchase Price.
Maybe there's an explanation.
Fantastic.
I'd like to hear it.
🔨 But What About MMR and “Auction Prices”?
This account specifically promotes the vehicles as coming “Direct from Auctions.”
That's where the Manheim Market Report—or MMR—comes in.
MMR isn't the same thing as KBB retail value. Manheim describes MMR as a wholesale-market valuation based on actual vehicles sold through Manheim, with values that can be adjusted for factors such as odometer reading, selling region, condition grade and even color. Manheim
That's why I'm not going to invent an exact MMR for the Charger in this video.
I don't have its VIN.
I don't have verified mileage.
I don't have its condition report.
I don't have its auction location.
I don't have a current vehicle-specific Manheim report.
Without those things, saying, “The MMR is exactly $XX,XXX,” would be pretending to know something I don't.
But here's what we can compare.
KBB puts the Scat Pack's trade-in value around $31,900. JD Power estimates a trade-in base of around $31,250–$33,250, depending on condition. Those aren't MMR, but they're useful wholesale-side reference points. Kbb.com
So if this really is a clean-title 2022 Scat Pack being sold for $5,850, the question isn't simply:
“Is it cheaper because it came from an auction?”
The question is:
How did someone acquire a vehicle worth tens of thousands of dollars cheaply enough to retail it for $5,850?
“Auction” isn't a magic word that makes vehicle economics disappear.
📞 Then I Noticed the Phone Numbers
Here's where things became even more interesting.
The TikTok profile lists:
+1 (347) 218-1605
The 347 area code is associated with New York City, including the boroughs of Brooklyn, Queens, the Bronx and Staten Island. It's commonly encountered around the broader NYC/Long Island market, although an area code obviously doesn't establish where somebody currently lives or operates a business.
But I watched several of the account's videos.
The gentleman appearing in those videos provides a different telephone number—with a 717 area code.
The 717 area code serves south-central Pennsylvania, including Harrisburg, Lancaster, and York.
Again, people keep phone numbers after moving. Businesses can have multiple telephone numbers. VOIP numbers exist. None of this, by itself, proves anything improper.
But when I'm supposedly dealing with a business selling cars online, it's another question I'd want answered:
Why does the profile give me one phone number while the person in the videos gives me another?
And, more importantly:
What's the actual dealership?
Where is it physically located?
Which number belongs to that dealership?
Those should be remarkably easy questions for a legitimate automobile dealer to answer.
👀 And Look at the Rest of the Inventory
The Charger isn't alone.
The profile shows a Mustang advertised for:
$8,500 — $900 down — $399/month
A GMC pickup:
$8,000 — $735 down — $399/month
A Mercedes-AMG GLE 53 appears to be advertised around:
$19,500 — $1,500 down
Another vehicle:
$5,500 — $500 down
Another:
$7,800 — $750 down
There's even a vehicle shown around $25,000 with $1,300 down.
The scenery changes.
The dealerships and lots visible in the videos appear to change.
The vehicles range from ordinary transportation to expensive luxury and performance models.
Yet the formula remains remarkably familiar.
🚩 “Verified Vehicles + Clean Titles”
Great.
Verified by whom?
That's not sarcasm. That's an actual question I'd ask before buying.
If I'm buying one of these cars, give me the VIN.
Then I can verify the vehicle myself.
If it has a clean title, provide the documentation I need to confirm it independently.
If it came from an auction, tell me which auction.
If you're a licensed dealer, give me the legal business name, physical address, and dealer-license information.
If you're offering in-house financing, give me the written financing terms.
I don't need a green checkmark emoji.
I need documentation.
💳 $700 Down and $399 a Month — What's the Loan?
There's another mathematical problem worth examining.
The Charger is advertised at:
$5,850 purchase price
minus
$700 down
which leaves:
$5,150
If the payments really are $399 per month, $5,150 divided by $399 is only about 12.9 payments, before interest, taxes, fees, or anything else.
So what's the actual term?
What's the APR?
What's the amount financed?
What's the total of payments?
Who's extending the credit?
Are there additional fees?
If the actual vehicle costs $5,850, those should be straightforward questions.
If $5,850 isn't actually the total cash price, then I'd like to know what that number represents.
🚩 54,000 Followers Don't Answer Any of This
This account is bigger than many I've previously documented.
54,300 followers.
That's meaningful social proof.
Someone encountering the account might reasonably think:
They have 54,000 followers. They must be legitimate.
But we've been through this before.
Followers aren't a dealer license.
Likes aren't a title.
Views aren't a VIN.
A green checkmark emoji isn't vehicle verification.
And a real person standing beside a real automobile doesn't establish that the TikTok account displaying the footage owns that automobile or is authorized to sell it under the advertised terms.
🚗 A Real Car Still Doesn't Automatically Make the Offer Real
This has become a recurring theme in this series.
Some of these videos clearly contain actual cars.
Some appear to have been filmed at actual dealerships.
There are real salespeople.
Real parking lots.
Real transporters.
Real dealership signs.
That's persuasive imagery.
But the question isn't:
“Does the car in this video exist?”
It's:
“Does this TikTok account own or have authority to sell this exact vehicle for this exact price under these exact terms?”
Those are very different questions.
I'm not claiming the footage on this account was copied from somewhere else. I haven't established that.
But before sending a $700 deposit, I'd want to establish where the footage came from and whether the seller I'm communicating with is actually connected to that vehicle.
🏡 Be Careful — and Be a Good Neighbor
This is the part that matters most.
Imagine someone who has terrible credit.
Their car just died.
They need transportation Monday morning, or they risk losing their job.
Traditional dealerships have turned them down.
Then TikTok serves them:
2022 Dodge Charger
$5,850
$700 down
$399/month
In-house financing available
That doesn't necessarily look suspicious to someone in that situation.
It looks like hope.
That's why, if somebody you know is considering one of these deals, don't ridicule them.
Help them investigate.
Before sending money, get the VIN. Verify the title. Find the dealership's legal name and physical address independently. Verify the dealer license with the appropriate state regulator. Call a publicly listed number—not simply the number supplied in a TikTok profile. Get the complete financing agreement. Have the vehicle independently inspected. And compare the asking price with retail and realistic wholesale values.
If the seller won't let you do those things before sending a deposit?
Keep your $700.
Different Account. Same Questions.
I'm seeing this pattern often enough that I can practically write the checklist before opening the profile.
Extremely inexpensive desirable car.
Small down payment.
Low monthly payment.
“Direct from auction.”
“Clean title.”
“In-house financing.”
Private messages.
Phone numbers that raise additional questions.
And prices that appear wildly disconnected from ordinary retail values.
Maybe this account has a perfectly reasonable explanation for it all.
I'd be interested in hearing it.
Because based on the screenshot, a $5,850 2022 Charger that appears to be a 392, compared with a KBB Fair Purchase Price around $37,600 for a Scat Pack, is one heck of an explanation. Kbb.com
Until then:
Be careful. Verify everything. And don't let a $700 down payment make a $30,000 question disappear.
Follow the continuing series at NielFlamm.com/blog.

The Scam Emails Are Getting Lazy: “Thanks for Your Order”… What Order?
Apparently, my imaginary shopping spree continues.
After Bitcoin purchases, mystery subscriptions, Geek Squad renewals, Facebook event invitations, and even a watch repair I never requested, the scammers have apparently decided they were working too hard.
Why bother creating an elaborate fake invoice when you can simply send:
“Thank You for Your Order.”
What order?
Excellent question.
Two Days, Two Mystery Orders
Yesterday, I received an email from “Manthan Williams” with the subject:
“Re: Thank You for Your Order 1KJBO6SYBRM6TJBQLEDV”
There was an attachment.
And almost nothing else.
Today, “Elizabeth Lewis” joined the party with:
“Thank You for Your Order 0RQKQA6198JOMD57P”
Another random order number.
Another attachment.
Another email with practically no explanation.
Apparently, customer service has embraced minimalism.
At Least Tell Me What I Bought
This is what makes these emails almost funny.
No recognizable retailer.
No product description.
No price prominently displayed.
No useful explanation of what I supposedly ordered.
Just:
Thank you for your order. Here's an attachment.
Oh, sure. Let me immediately open a mystery attachment from a random Gmail account to discover what I supposedly purchased.
What could possibly go wrong?
I'm not opening it.
That's an important point. I don't need to open an unsolicited attachment to investigate a purchase I don't recognize.
If I actually ordered something, I can check the retailer or payment account independently.
The Random Gmail Addresses Aren't Helping
One email claims to be from Elizabeth Lewis but arrives from a seemingly unrelated Gmail address.
The other claims to be from Manthan Williams and also comes from an unrelated Gmail address.
Could legitimate people use Gmail?
Of course.
But when an unexpected “order” email arrives from a random Gmail account, provides virtually no information, and wants me to open an attachment to learn more, my curiosity isn't winning this battle.
Delete beats double-click.
The Attachment Is the Bait
These messages use a slightly different approach than the fake PayPal and Facebook invitation scams I've been documenting.
Those messages tried to scare me with a large dollar amount and get me to call a telephone number.
These appear designed to create curiosity:
What did I order?
How much did they charge me?
Did somebody use my credit card?
What's in that attachment?
And that's exactly why I'm leaving the attachment alone.
Fear can make people click.
But so can curiosity.
My Imaginary Self Has Quite the Lifestyle
According to my inbox, imaginary Niel has been busy.
Bitcoin.
Geek Squad.
Mystery subscriptions.
Watch repairs.
More mystery subscriptions.
And now two mystery orders in two days.
The only thing missing is knowing what I actually bought.
Come on, scammers.
If you're going to invent purchases for me, at least make them interesting.
Tell me I bought a Ferrari.
A beachfront condo.
A private jet.
Maybe a lifetime supply of Coke Zero.
Give me something worth accidentally ordering.
Instead, I get:
ORDER 0RQKQA6198JOMD57P.
I'm underwhelmed.
Have a Scam Email? Send It to Me
I'm still collecting these because the tactics keep changing, even though the objective remains the same: get us to react before we stop and think.
If you've received a suspicious email, fake invoice, mystery order, phishing text, social media scam, or another creative attempt to separate you from your money, send it my way:
Tell me what happened and send a screenshot if you have one. Please remove or cover sensitive personal or financial information before sending anything.
Maybe I'll feature it in a future post.
Until then, Elizabeth and Manthan:
Thanks for thanking me for my orders.
Whatever they are.