
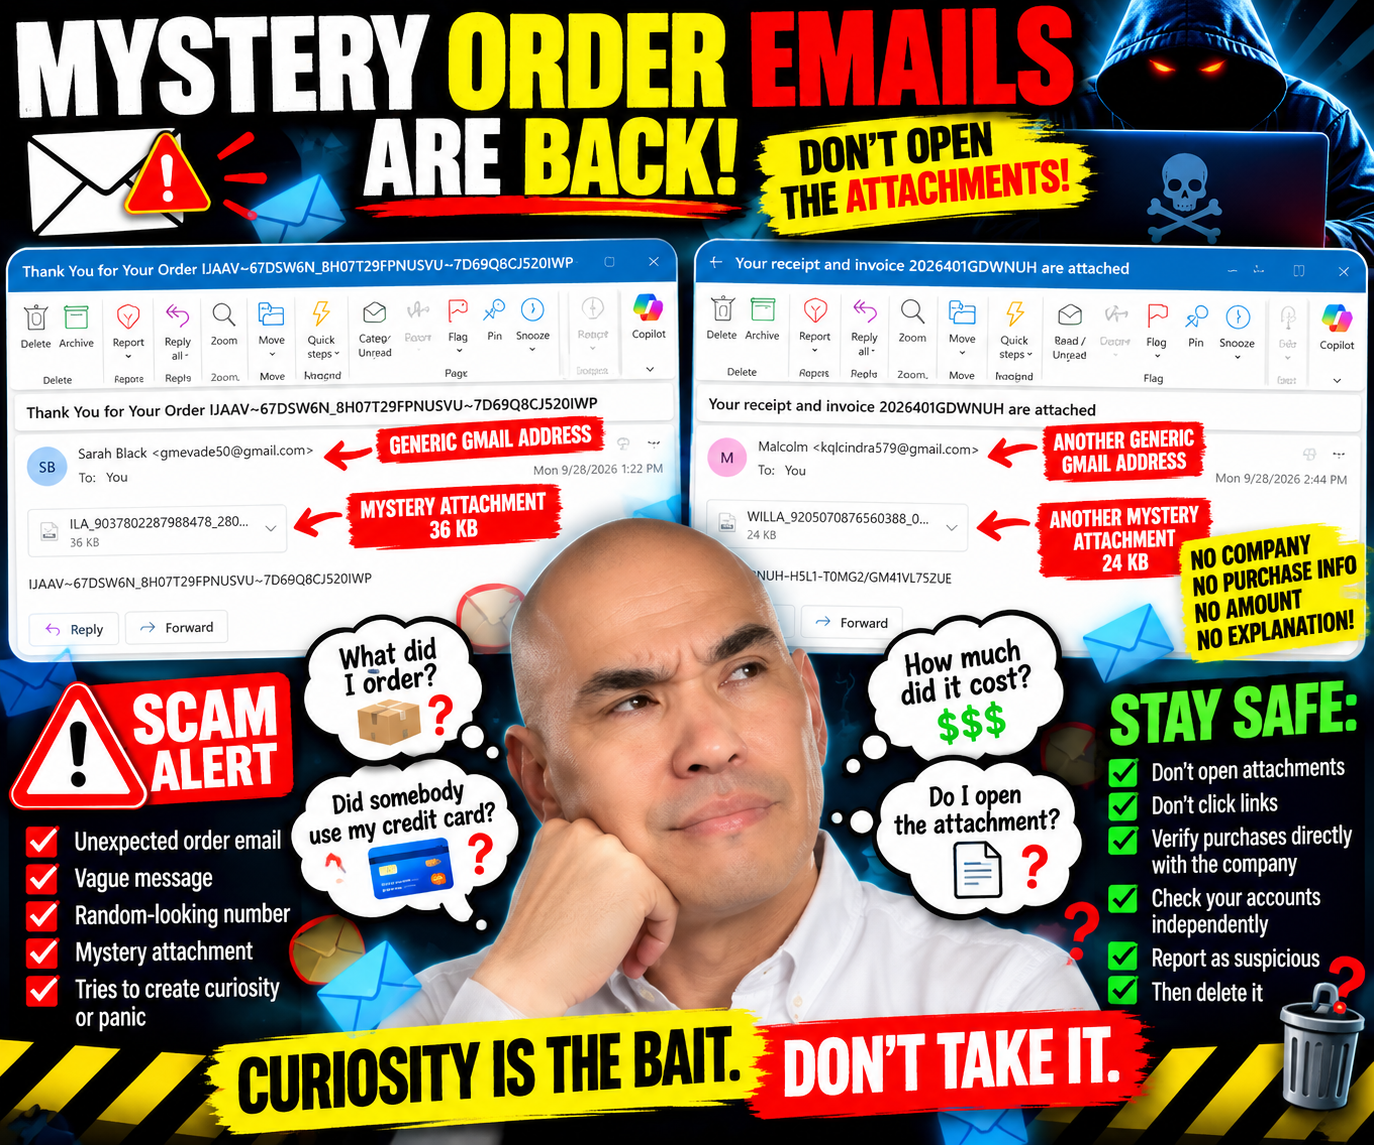
Apparently, the Scammers Still Haven’t Started Writing Emails
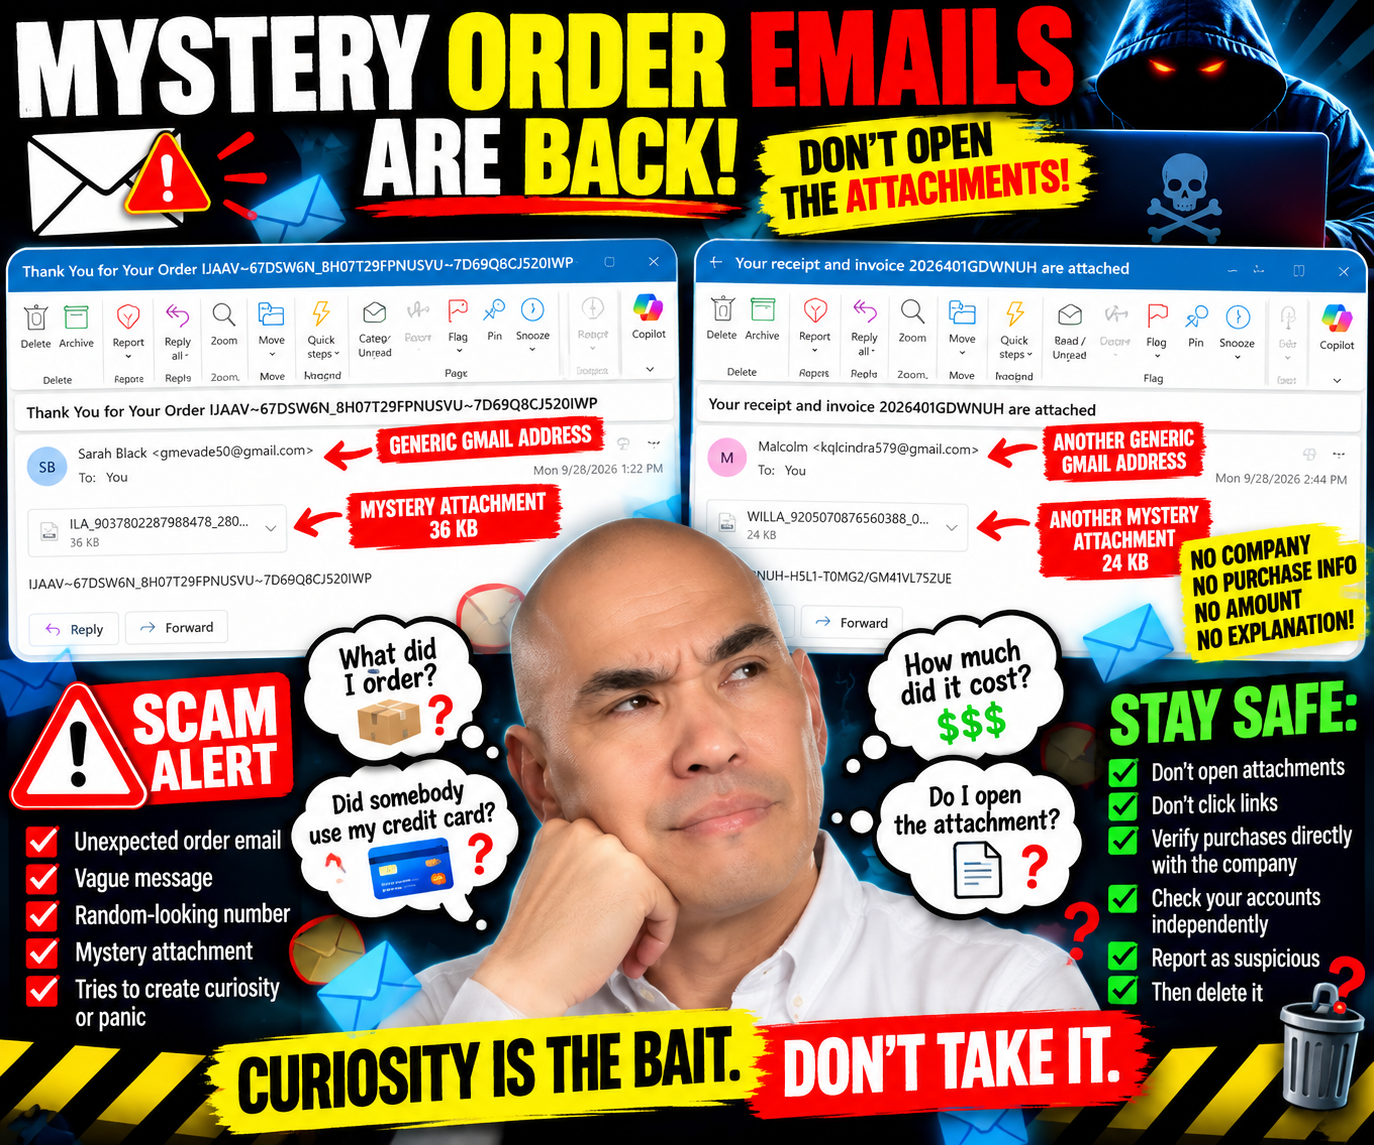
Just when I thought the mystery-order-email department might have run out of ideas, two more showed up.
Apparently, writing an actual email is still too much work.
No company introduction. No explanation of what I supposedly purchased. No recognizable merchant. No dollar amount. No useful order details.
Just a mysterious attachment and the digital equivalent of:
“You bought something. Trust me. Open this.”
Yeah, I’ll get right on that.
Mystery Order #1: Thank You for…Whatever I Ordered
The first email arrived with this rather catchy subject line:
“Thank You for Your Order IJAAV~67DSW6N_8H07T29FPNUSVU~7D69Q8CJ520IWP”
Well, that certainly clears things up.
It came from someone named Sarah Black, using a Gmail address.
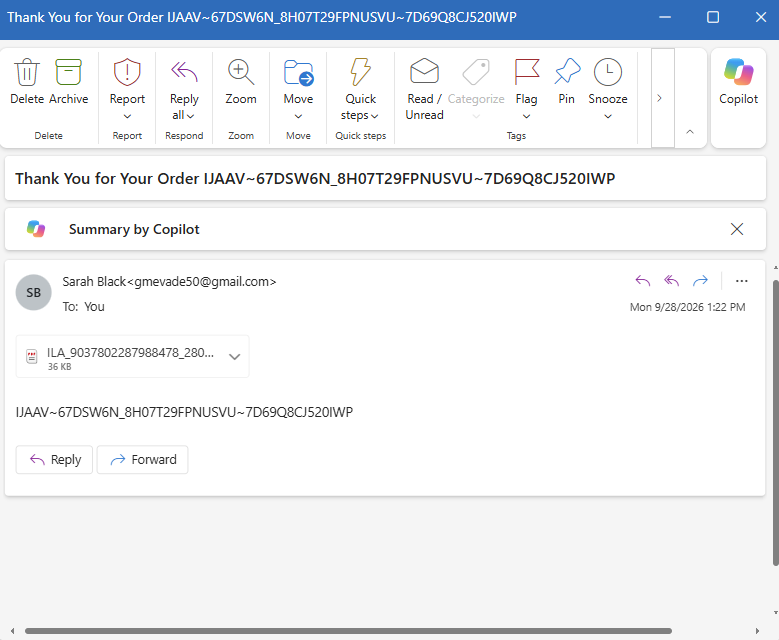
Inside the email?
Almost nothing.
There's another long collection of letters and numbers and a 36 KB attachment.
That's it.
No store.
No product.
No purchase price.
No credit card information.
No shipping address.
No customer-service information.
Nothing explaining what this alleged order actually is.
To see what I bought, I need to open the attachment.
Nope.
Mystery Order #2 Arrives the Next Day
Then another one arrived.
This time the subject was:
“Your receipt and invoice 2026401GDWNUH are attached”
Now we're getting fancy.
We've upgraded from a mysterious “order” to a mysterious receipt AND invoice.
This one came from someone named Malcolm, also using a Gmail address.
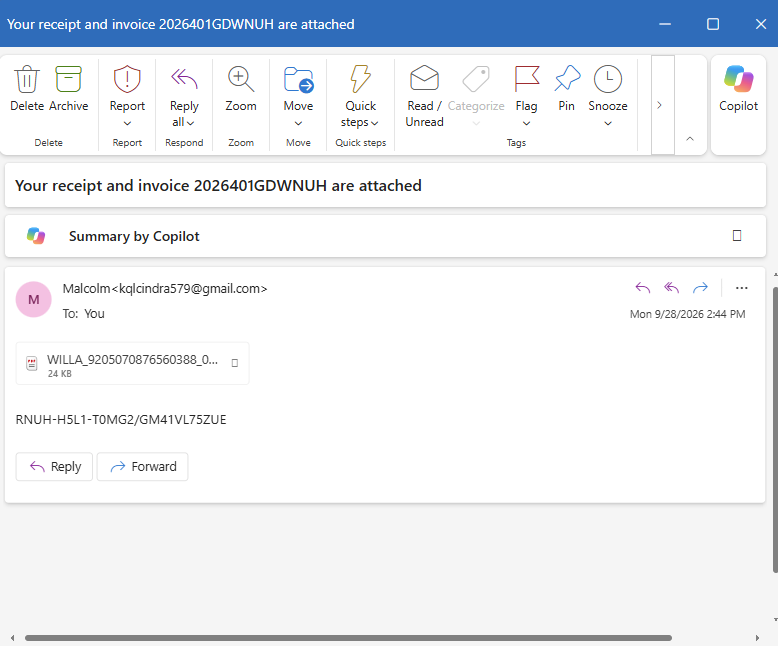
The body of the email contains another random-looking code:
RNUH-H5L1-I0MG2/GM41VL75ZUE
And, naturally, there's another attachment—this one is 24 KB.
Again, the message doesn’t identify a recognizable business.
No explanation of what I purchased.
No price.
No payment information.
No description.
Just an attachment.
🚩 The Attachment Is Still the Email
I've written about this before, and apparently somebody out there wants to provide me with additional examples.
These messages aren't really trying to communicate anything useful.
The attachment is the email.
Everything surrounding it seems designed to create just enough curiosity or concern to make me open it.
Maybe my first reaction is:
What did I order?
Then:
Did somebody use my credit card?
Then:
How much did they charge me?
And finally:
I’d better open this invoice and find out.
That's precisely the reaction I don't want to have.
If I don't recognize a purchase, my first move isn't to open a mystery attachment from an unfamiliar Gmail account.
I'm going directly to my bank, credit-card company, retailer account, or whatever legitimate service supposedly processed the transaction.
Curiosity Can Be the Bait
I haven't opened either attachment, so I don't know what's inside them.
I can't claim they're malware without examining them.
And that's really the point.
I don't need to know what's inside.
Neither message gives me a reason to take that risk.
If I really made a purchase, I can verify it independently.
If there's an unauthorized charge, I can see it through my financial institution.
If a legitimate company needs to contact me about an order, I can go directly to that company's website or app rather than following instructions contained in an unsolicited email.
Opening a mystery file shouldn't cost me to find out whether I supposedly spent money.
Two Emails, Same Basic Formula
These arrived on consecutive days from different Gmail addresses with different names, different order numbers, and different attachments.
But look at the structure:
Unexpected purchase notification → vague message → meaningless-looking number → attachment → curiosity.
That's what catches my attention.
They don't need me to believe the email for very long.
They need me to think:
“What the heck did I buy?”
…and click.
Don't Let the Email Create the Emergency
That's another lesson I've learned from documenting these messages.
A suspicious email shouldn't create a problem and then dictate how I investigate it.
If an email tells me there's an order I don't recognize, I'll check my accounts independently.
If it says there's a PayPal charge, I'll log in to PayPal independently.
If it says there's a credit-card transaction, I'll check that card myself.
If it claims there's an Amazon order, I'll open Amazon myself.
I don't need the mystery attachment.
Be a Good Neighbor
These emails may look ridiculous to someone who's seen hundreds of them.
Not everyone has.
Someone else might see “Thank You for Your Order” and immediately panic.
Maybe they're worried someone stole their credit card.
Maybe they're afraid hundreds of dollars just disappeared from their checking account.
Maybe they can't remember whether they ordered something.
That's when it's worth saying:
Don't open the attachment yet. Let's verify the supposed purchase another way.
Help someone check the real account.
Show them how to inspect the sender.
Explain why an unexpected attachment deserves caution.
Report suspicious messages.
Then delete them.
Because apparently the scammers still haven't started writing emails.
But they certainly haven't stopped sending attachments.
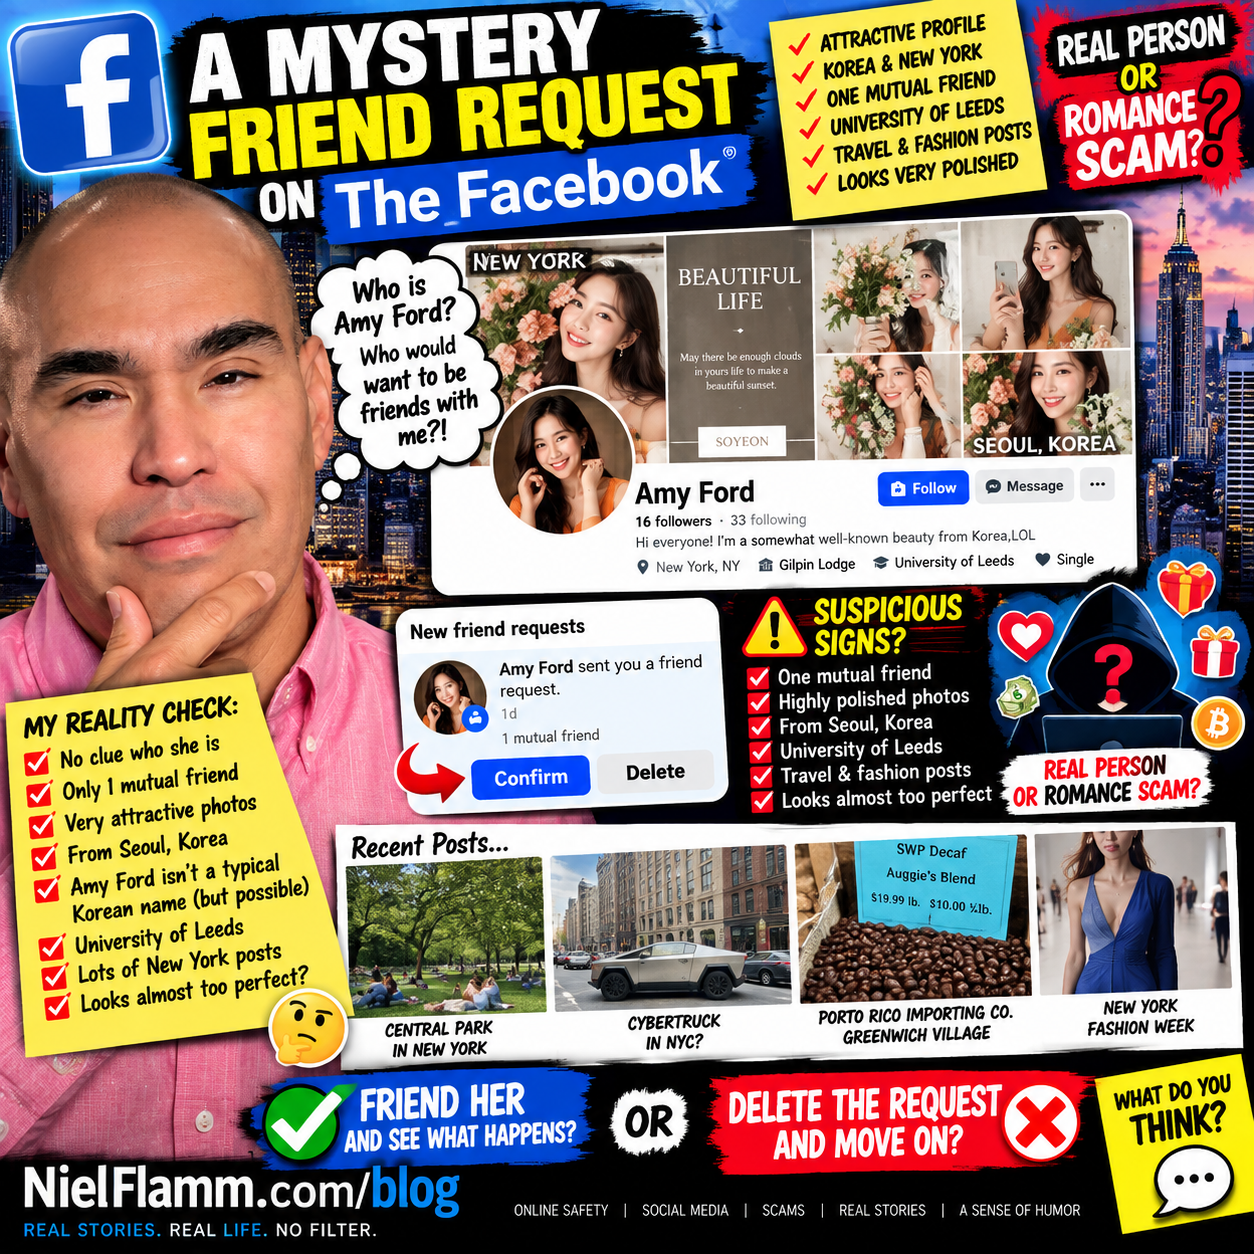
A Mystery Friend Request on The Facebook: Friend Her or Hit Delete?
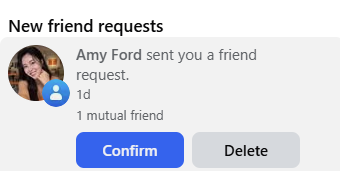
A few days ago, I received a friend request on The Facebook.
Yes, I’m calling it The Facebook.
The request came from Amy Ford.
My immediate reaction was pretty simple:
Who is Amy Ford?
I have absolutely no clue.
Then the second thought kicked in:
Who would randomly want to be friends with me?
And that's when a little insecurity started creeping in. I'm old. My kidneys are failing. I have one fully intact leg. My eyes aren't exactly operating at 4K resolution. I'm a little chubby.
Yet here comes this attractive stranger wanting to be my friend on The Facebook.
Okay.
What could go wrong?
One Mutual Friend
Before immediately hitting delete, I looked at the profile.
We have one mutual friend.
One.
That's enough to make me curious, but certainly not enough to make me think, Oh, of course! Amy!
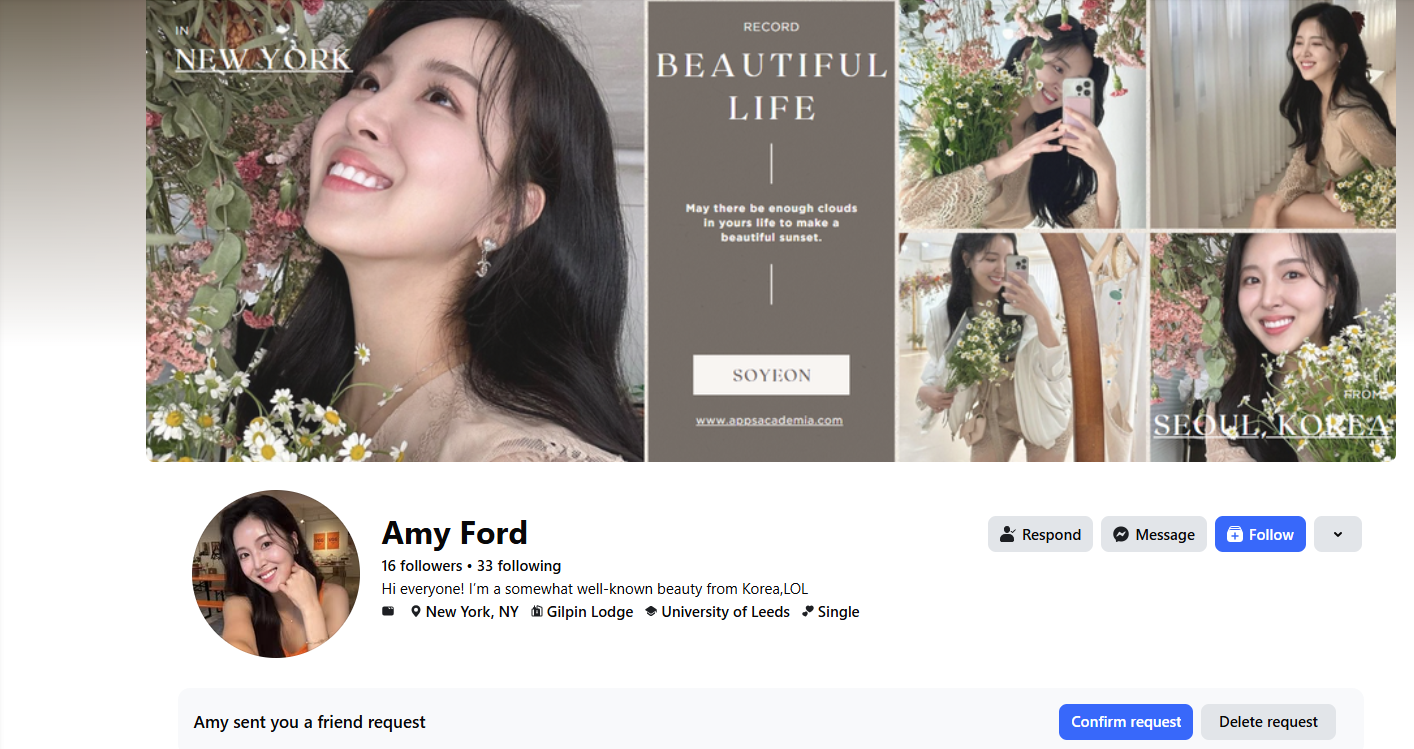
Her profile says she's in New York and references Korea, along with the University of Leeds. Her bio says:
“Hi everyone! I’m a somewhat well-known beauty from Korea, LOL.”
That's an interesting introduction.
And yes, the name Amy Ford initially caught my attention, along with the Korean references. Of course, someone from Korea can have an English or Western name, so the name by itself proves absolutely nothing.
But combined with everything else?
My curiosity started winning.
So I Started Digging
I looked through her public posts.
There are posts about New York.
Central Park.
Ballet.
A Cybertruck driving through Manhattan.
Porto Rico Importing Co. in Greenwich Village.
New York Fashion Week.
Plenty of photographs, locations, and little slices of New York life.
At first glance, it looks like someone documenting life in the city.
But then I started looking at the profile as a whole.
The account shows 16 followers and 33 following.
We share only that one mutual connection.
There are highly polished profile and cover images featuring the same woman, including a collage labeled “NEW YORK,” “BEAUTIFUL LIFE,” “SOYEON,” and “SEOUL, KOREA.”
Then there's the University of Leeds reference.
Maybe every bit of it is legitimate.
Maybe Amy is exactly who the profile says she is.
Or maybe this will become another chapter in my growing collection of strange things people send me online.
I don't know.
And that's precisely why I haven't hit Confirm.
I've Seen This Movie Before
After documenting recruiter scams, suspicious social media accounts, fake car sellers, PayPal scams, Geek Squad scams, mystery invoices, and the other nonsense that seems to find its way to me, I've learned something:
Curiosity is powerful.
It's also exactly what questionable accounts can rely on.
The temptation is obvious.
Accept the request.
Don't volunteer any personal information.
Don't click anything.
Don't send money.
And see what happens.
Will “Amy” send a perfectly normal message?
Will she never contact me at all?
Will we suddenly move from Hello to cryptocurrency investing in 14 minutes?
Will an uncle show up with an incredible investment opportunity?
Will WhatsApp or Telegram show up?
Maybe none of that happens.
That's what makes this interesting.
So I'm Putting It to You
I'm genuinely undecided.
There isn't enough here for me to declare that the person behind this account is a scammer. A profile that looks unusual to me isn't proof of anything, and neither is someone's name, appearance, nationality, school, number of friends, or posting style.
But there are enough things that don't immediately add up for me that I'm hesitant to click Confirm.
So, readers, I'm handing you the mouse.
What should I do?
👍 Accept the friend request and see what happens?
🗑️ Delete it and move along?
And more importantly: What do you look for when a stranger sends you a friend request on The Facebook?
I have a feeling the comments on this one could be more entertaining than the friend request.
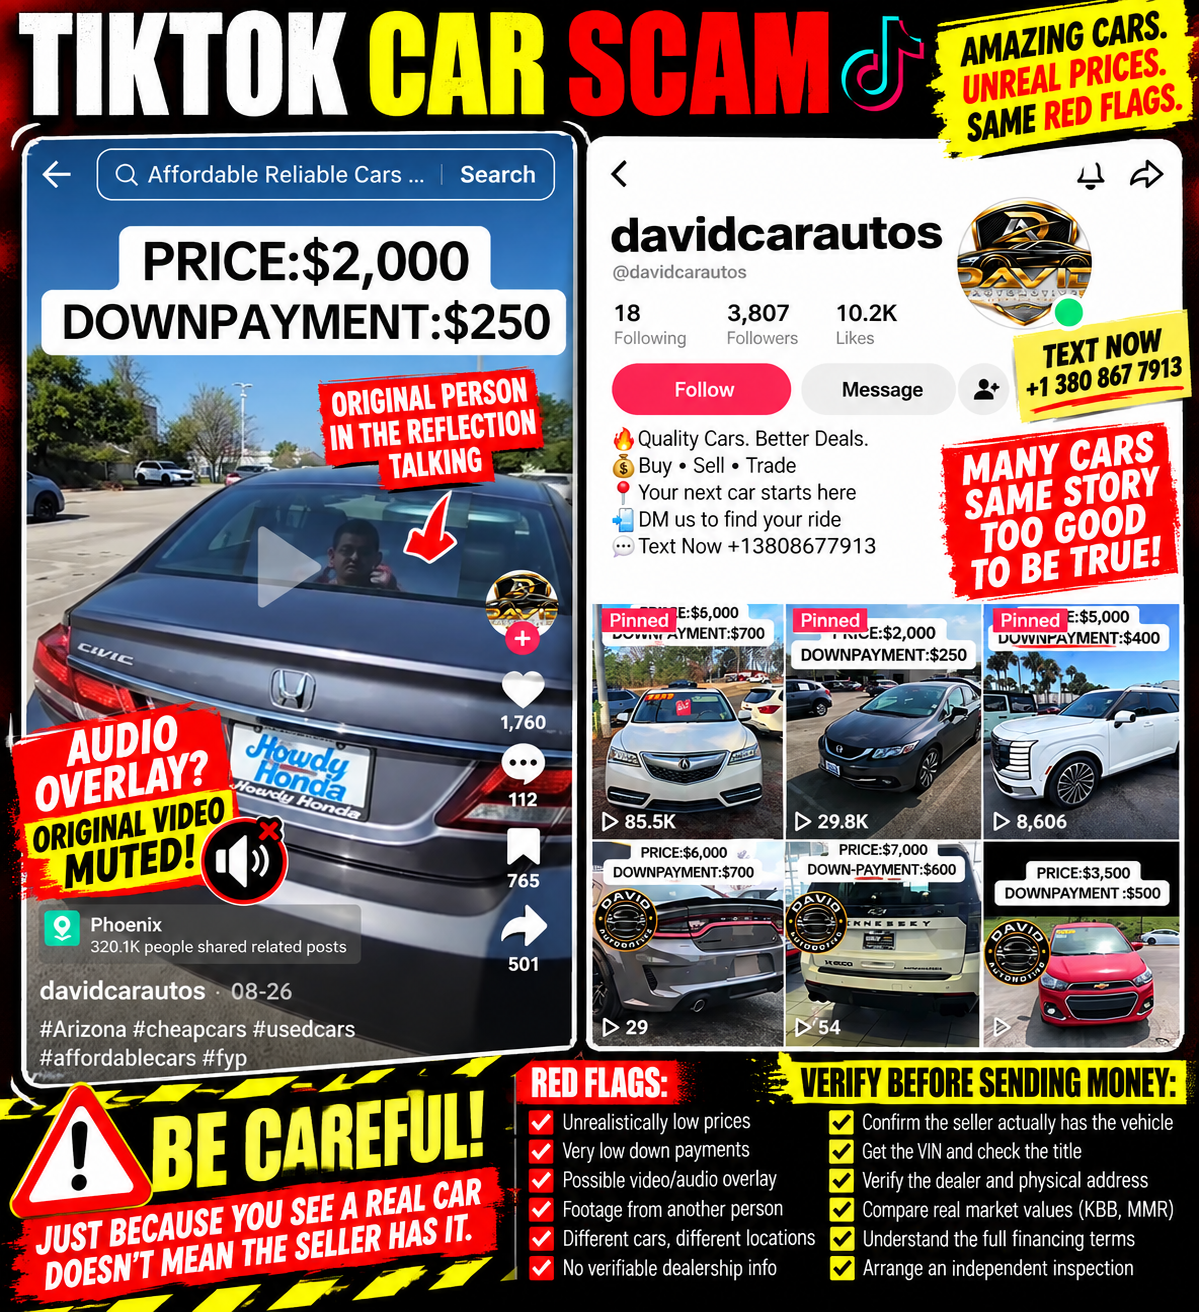
Another TikTok Car Deal — But Who Actually Has the Car?
At this point, TikTok may know my viewing habits a little too well.
Another extremely inexpensive vehicle landed in my feed. This time, it's from an account called davidcarautos, and the featured vehicle looks like a Honda Civic.
The advertisement couldn't be much simpler:
PRICE: $2,000
DOWN PAYMENT: $250
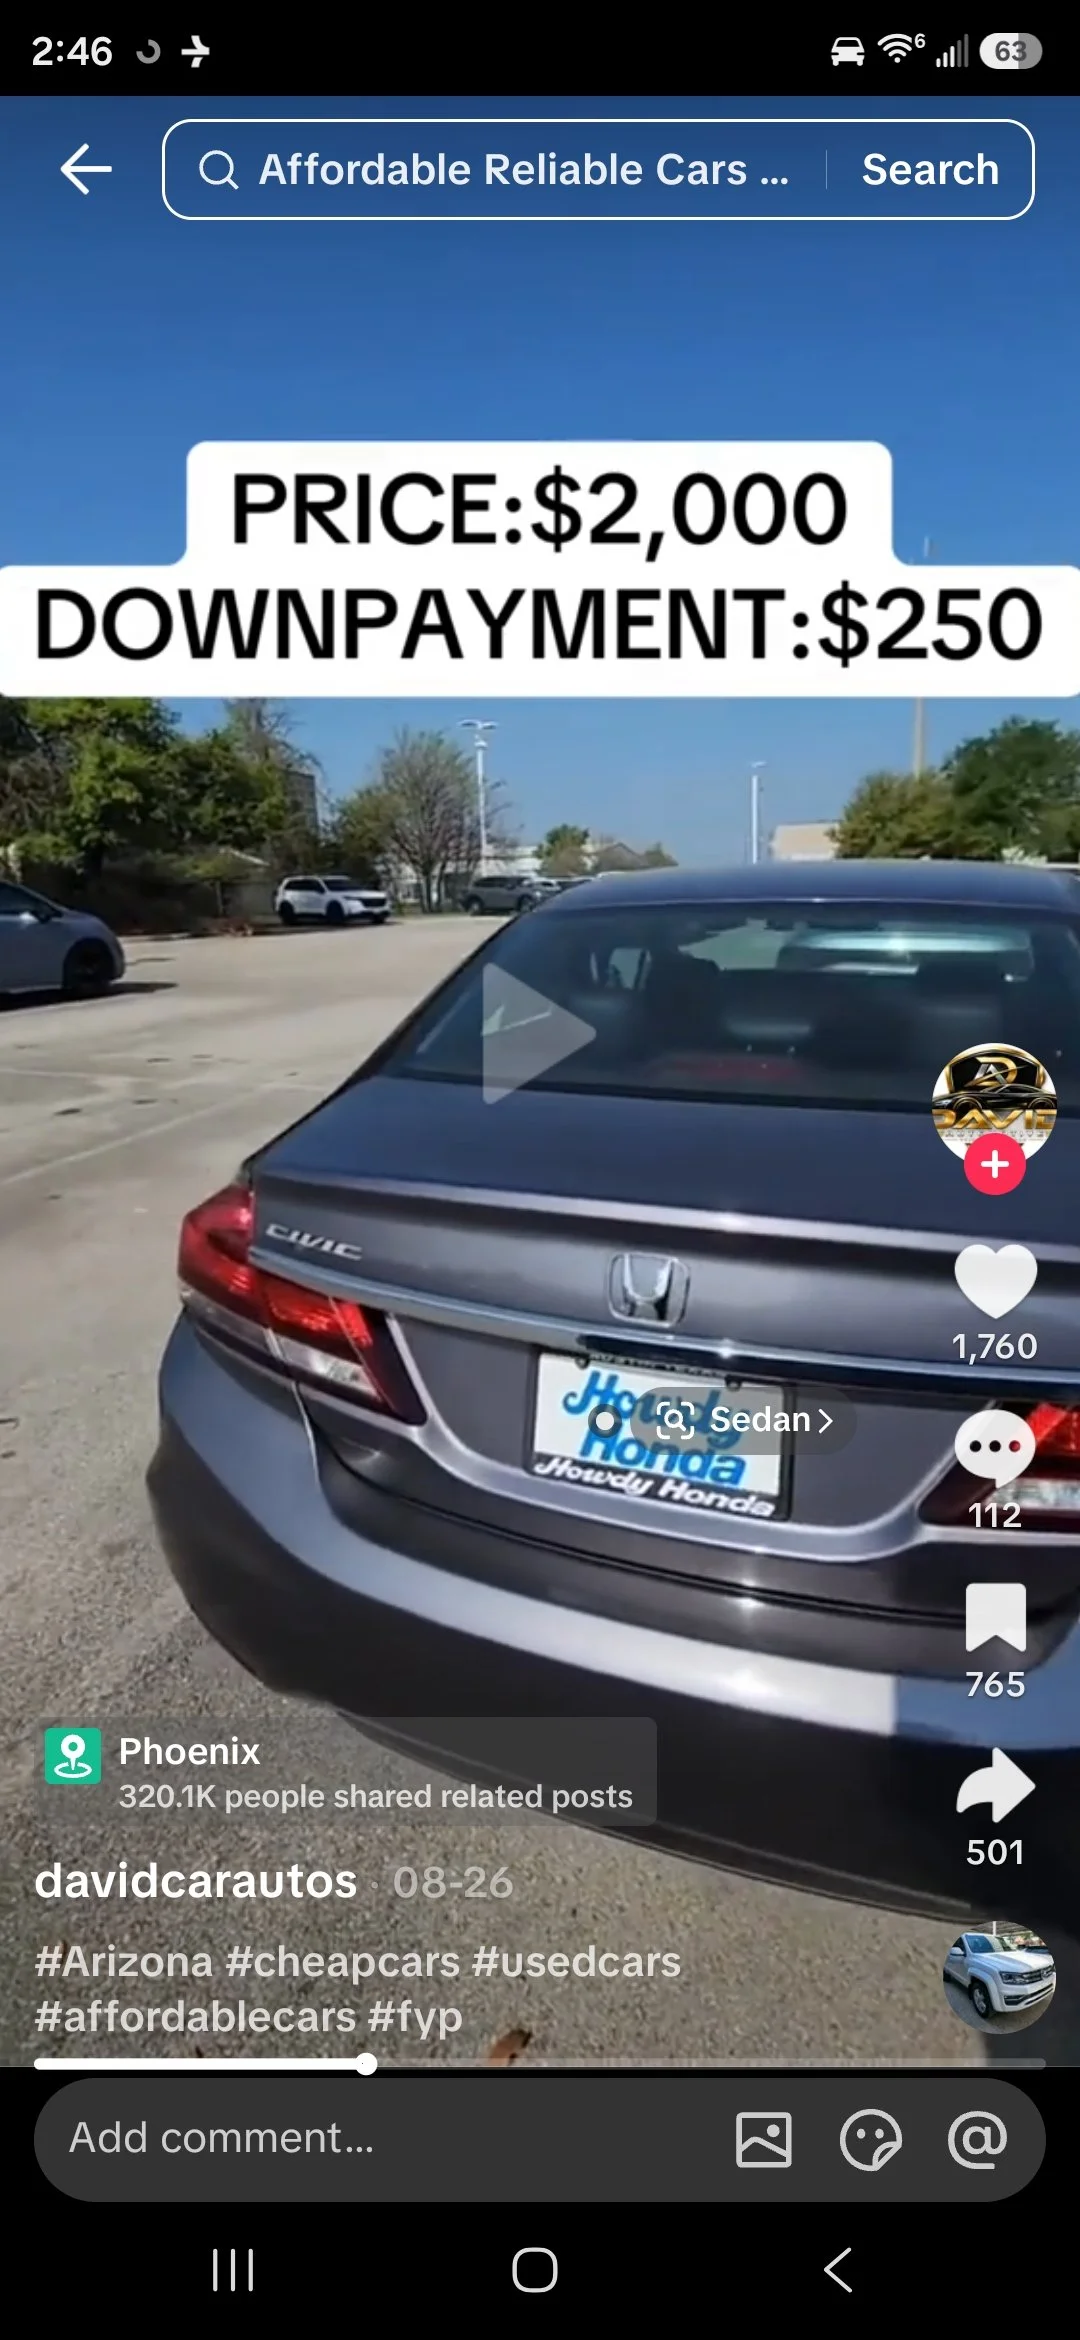
Two thousand dollars for the car, and apparently I can get started for $250.
But this video caught my attention for a reason beyond the price.
Wait—Whose Video Am I Watching?
I watched the video instead of just looking at the price.
That's when something looked odd.
The video appears to have been overlaid with new audio while the original video's audio is muted. As the camera moves around the Honda, I can see what appears to be the original person recording or speaking reflected in the car's window.
Meanwhile, the narration I'm hearing doesn't seem to match what's happening in the original footage.
The new narration makes a particularly interesting pitch: you don't have to go to a dealership to purchase a car.
That's supposed to make the transaction sound easier.
To me, it raises the opposite question:
Does the person posting this TikTok actually possess this car?
I can't establish from these screenshots alone who originally recorded the video or whether the TikTok account has permission to use it. So I'm not going to claim I've proven the footage was stolen.
But an apparently repurposed video combined with a new sales narration is absolutely something I would investigate before sending $250 to anybody.
🚗 A Real Honda in a Video Doesn't Prove the Seller Owns It
This is becoming one of the recurring lessons in my TikTok car series:
A real car doesn't automatically make the offer real.
That's especially important here.
The Honda clearly exists.
A license-plate frame is visible that appears to say Howdy Honda. There's a parking lot. A person is reflected in the vehicle.
All of that makes the video look authentic.
But those things establish the existence of a car and a video.
They don't establish that @davidcarautos owns the car, possesses the car, represents the owner, or has authority to sell it for $2,000.
That's a huge distinction.
The FTC issued a consumer warning this month specifically about scammers impersonating dealerships. It says scammers can copy legitimate dealerships' branding, vehicle listings, and photos, then collect money for cars the supposed seller doesn't actually have. The FTC recommends independently verifying the dealership and, when you can't visit the vehicle yourself, arranging an independent inspection. Consumer Advice
The FBI has also warned about fraudulent online vehicle advertisements involving cars that aren't—and sometimes never were—in the advertiser's possession. Internet Crime Complaint Center
That's why this video's altered presentation matters to me.
“You Don't Have to Go to a Dealer”
Technically, that's true.
People legitimately purchase vehicles remotely every day.
Dealerships deliver cars. Buyers purchase vehicles from other states. Documents can be signed electronically. Independent inspections can be arranged.
Remote car buying isn't inherently suspicious.
But there's a big difference between:
“You don't have to physically visit our dealership.”
and:
“You don't need to independently establish that we actually have the car.”
That second part is non-negotiable for me.
If someone wants my money for a vehicle, I want to know exactly where that vehicle is sitting.
👀 Then I Looked at the Profile
The account had approximately:
3,807 followers
10,200 likes
Its bio says:
🔥 Quality Cars. Better Deals.
💰 Buy • Sell • Trade
📍 Your next car starts here
➡️ DM us to find your ride
💬 Text Now +1 380-867-7913
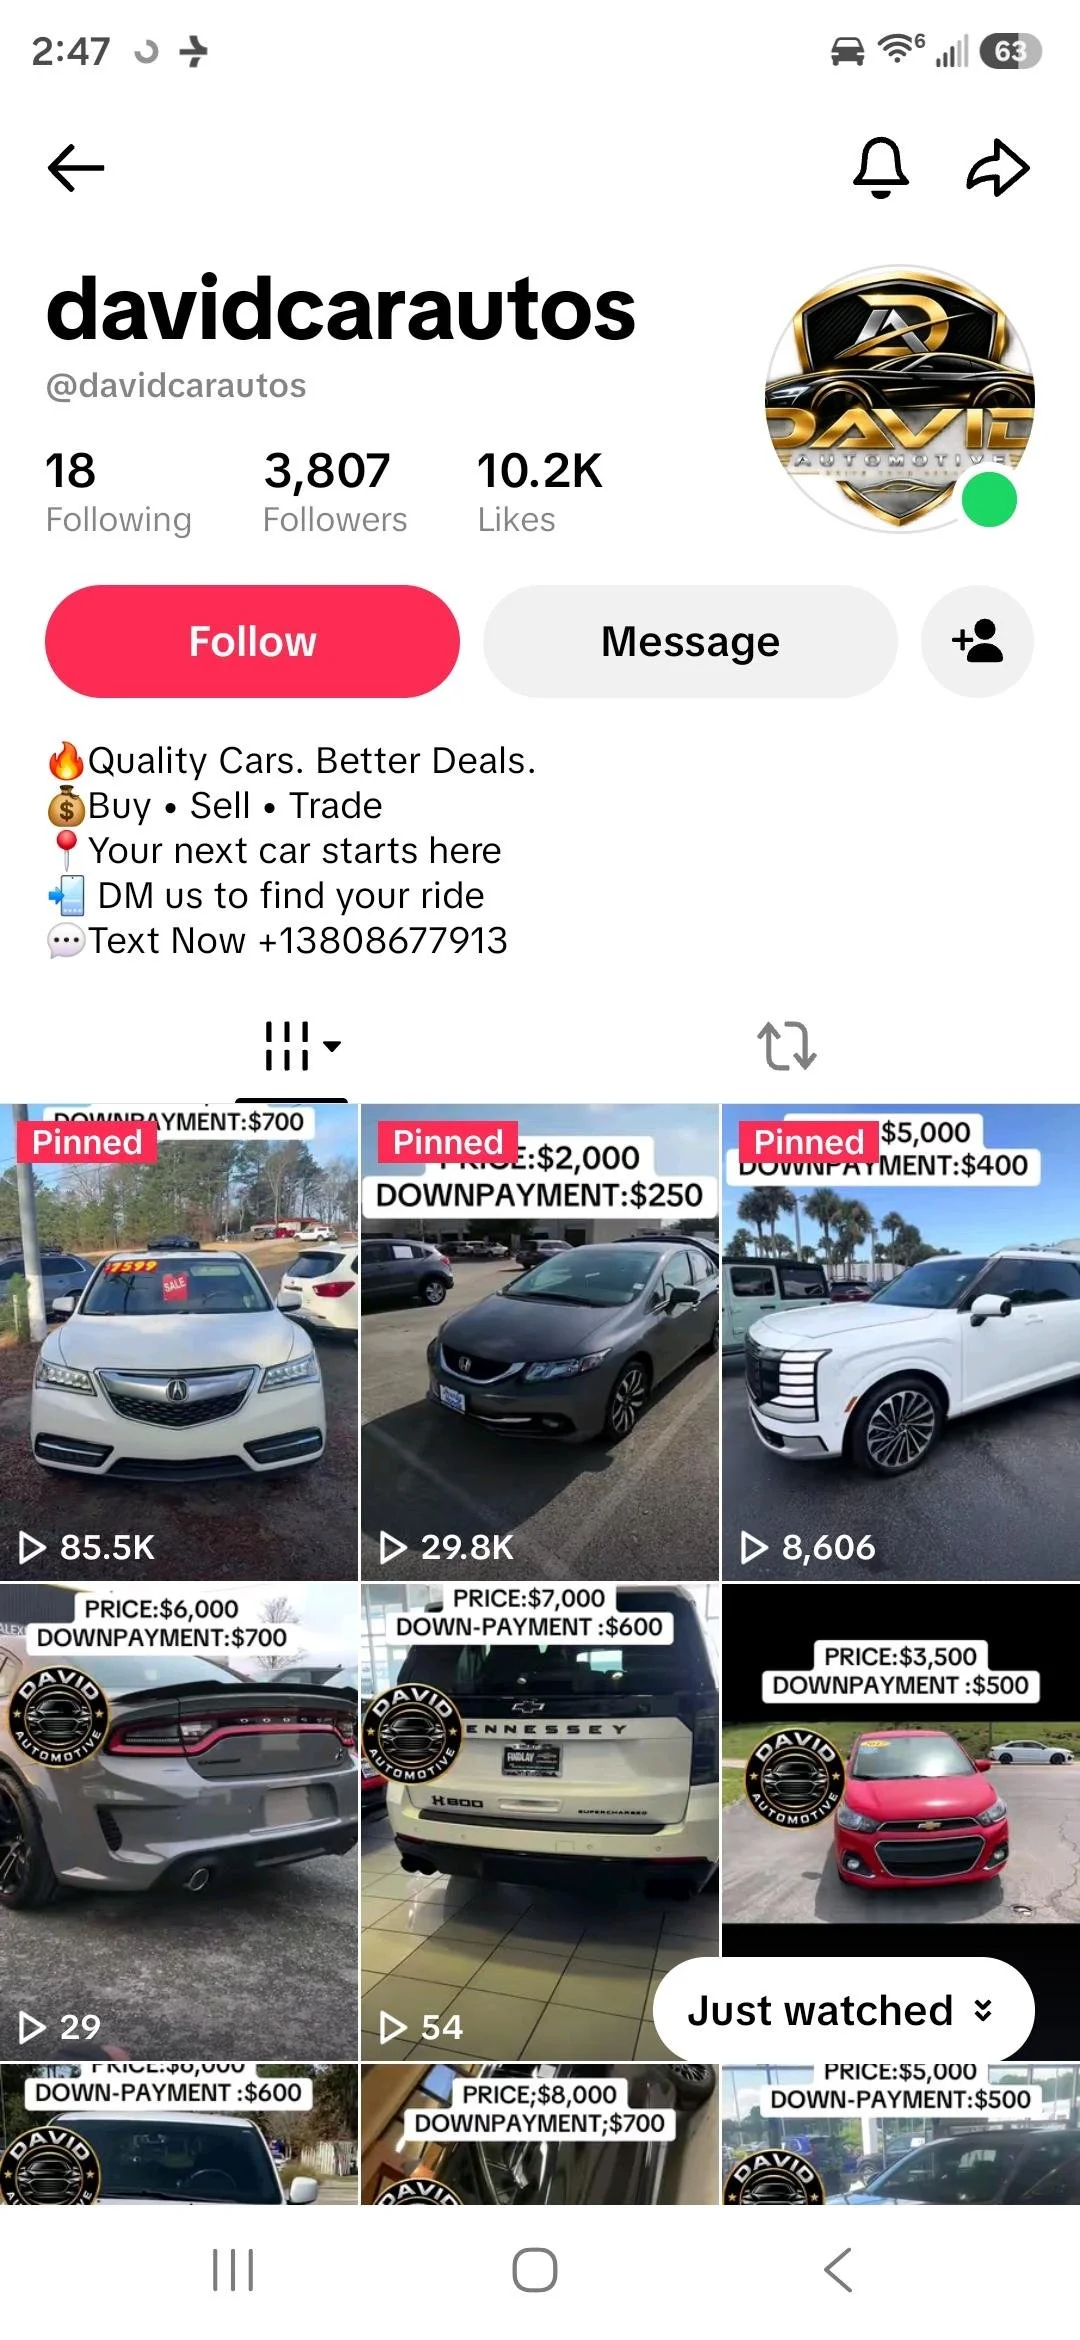
Then I looked at the inventory.
Here we go again.
The Honda is advertised for:
$2,000 — $250 down
Another vehicle:
$5,000 — $400 down
A Dodge:
$6,000 — $700 down
A Chevrolet Hennessey vehicle:
$7,000 — $600 down
Another:
$3,500 — $500 down
And more vehicles appear farther down the page with similarly low asking prices and down payments.
Different cars.
Different backgrounds.
Different dealerships appearing in some of the footage.
Same account selling all of them.
That doesn't prove anything by itself.
It does make one question increasingly important:
Where are these cars actually located?
📍 The Honda Video Says Phoenix
The TikTok interface on the Honda video displays Phoenix, and the hashtags include:
#Arizona #cheapcars #usedcars #affordablecars
Meanwhile, the visible dealership plate frame appears to identify a Honda dealership.
So before sending $250, I'd want to independently identify that dealership and call it using the telephone number from its own official website, not a number supplied by the TikTok account.
Then I'd ask a remarkably simple question:
Do you have this Honda, and is @davidcarautos authorized to sell it?
That could clear up a lot very quickly.
💰 And What Does “$250 Down” Actually Mean?
We've seen this repeatedly.
A tiny down payment gets enormous visual emphasis.
$250 DOWN!
That number feels attainable.
But it tells me almost nothing about the financing.
If the vehicle's total price really is $2,000 and I'm putting $250 down, the remaining amount is $1,750 before taxes, fees, interest and other charges.
So give me the rest:
What's the APR?
What's the term?
What's the monthly payment?
Who's the lender?
What's the total amount financed?
What's the total of payments?
What fees are included?
What credit requirements apply?
Is $2,000 actually the cash purchase price, or is there another condition attached to receiving that price?
The FTC has long warned consumers that unusually low advertised prices, down payments and monthly payments can come with qualifications or additional terms that aren't obvious from the headline advertisement. Consumer Advice
The giant number gets my attention.
The contract gets my money.
I care much more about the second one.
🎥 The Video Overlay May Be the Most Interesting Part
This is what distinguishes this post from some of the others I've documented.
The video itself appears to contain evidence of two different presentations:
The original footage.
And the new narration selling the vehicle.
Maybe there's a perfectly legitimate explanation.
Maybe the account licenses videos from dealerships.
Maybe it's a broker.
Maybe it has agreements with multiple dealers.
Maybe the person who made the original footage is connected with this account.
All of those possibilities can exist.
But I shouldn't have to guess.
If you're asking me to send money, tell me:
Who recorded the original video?
Who currently owns the vehicle?
Where is it physically located?
What's the VIN?
What's the dealer's legal business name?
Can I call that business independently?
Can someone inspect the vehicle before I pay?
A legitimate transaction should survive those questions.
🚨 This Isn't a Hypothetical Type of Scam
The FTC's September 2026 warning describes consumers paying supposed online dealerships only to discover that the actual dealership has no record of the order or payment and no car waiting for them. The FTC says fraudulent sellers can clone legitimate dealership material, including vehicle listings and photos. Consumer Advice
This problem isn't limited to websites, either. FTC data released this year show that nearly 30% of people reporting a scam loss in 2025 said the scam began on social media, with reported losses totaling $2.1 billion. Federal Trade Commission
So seeing a real automobile in a TikTok video isn't where my verification process ends.
It's where it begins.
🏡 Be a Good Neighbor
Here's the person I worry about.
Someone desperately needs transportation.
Their credit isn't great.
They've been turned down elsewhere.
They see:
HONDA CIVIC
PRICE: $2,000
DOWN PAYMENT: $250
And then they hear:
You don't even have to go to the dealership.
Convenient.
Affordable.
Easy.
Exactly what they need.
That's when somebody needs to say:
“Before you send the $250, let's verify the car.”
Not ridicule them.
Not call them stupid.
Help them investigate.
Reverse-search screenshots from the video. Identify the dealership visible in the footage. Call that dealership independently. Ask for the VIN. Verify the title. Check the seller's dealer license. Compare the price with KBB and wholesale values. Arrange an independent inspection.
And most importantly:
Verify that the person asking for your money actually has the legal ability to sell you the car.
The FTC's current advice is similarly straightforward: if you're too far away to see an online vehicle yourself, ask to have a mobile inspection service examine it. If the seller won't allow that, consider walking away. Consumer Advice
The Cars Keep Changing. My Question Doesn't.
Different TikTok accounts.
Different prices.
Different down payments.
And now apparently repurposed-looking video accompanied by a new narration telling me I don't have to visit a dealership.
I don't necessarily need to visit the dealership.
But before anybody gets one dollar from me, I need something considerably more important:
Proof that you actually have the car you're trying to sell me.
Because if the seller doesn't possess the vehicle or have authority to sell it, I'm not purchasing a car remotely.
I'm just sending $250 to somebody on TikTok.
Questions or another suspicious car listing you'd like me to look at? Reach out by DM or email niel@nielflamm.com.
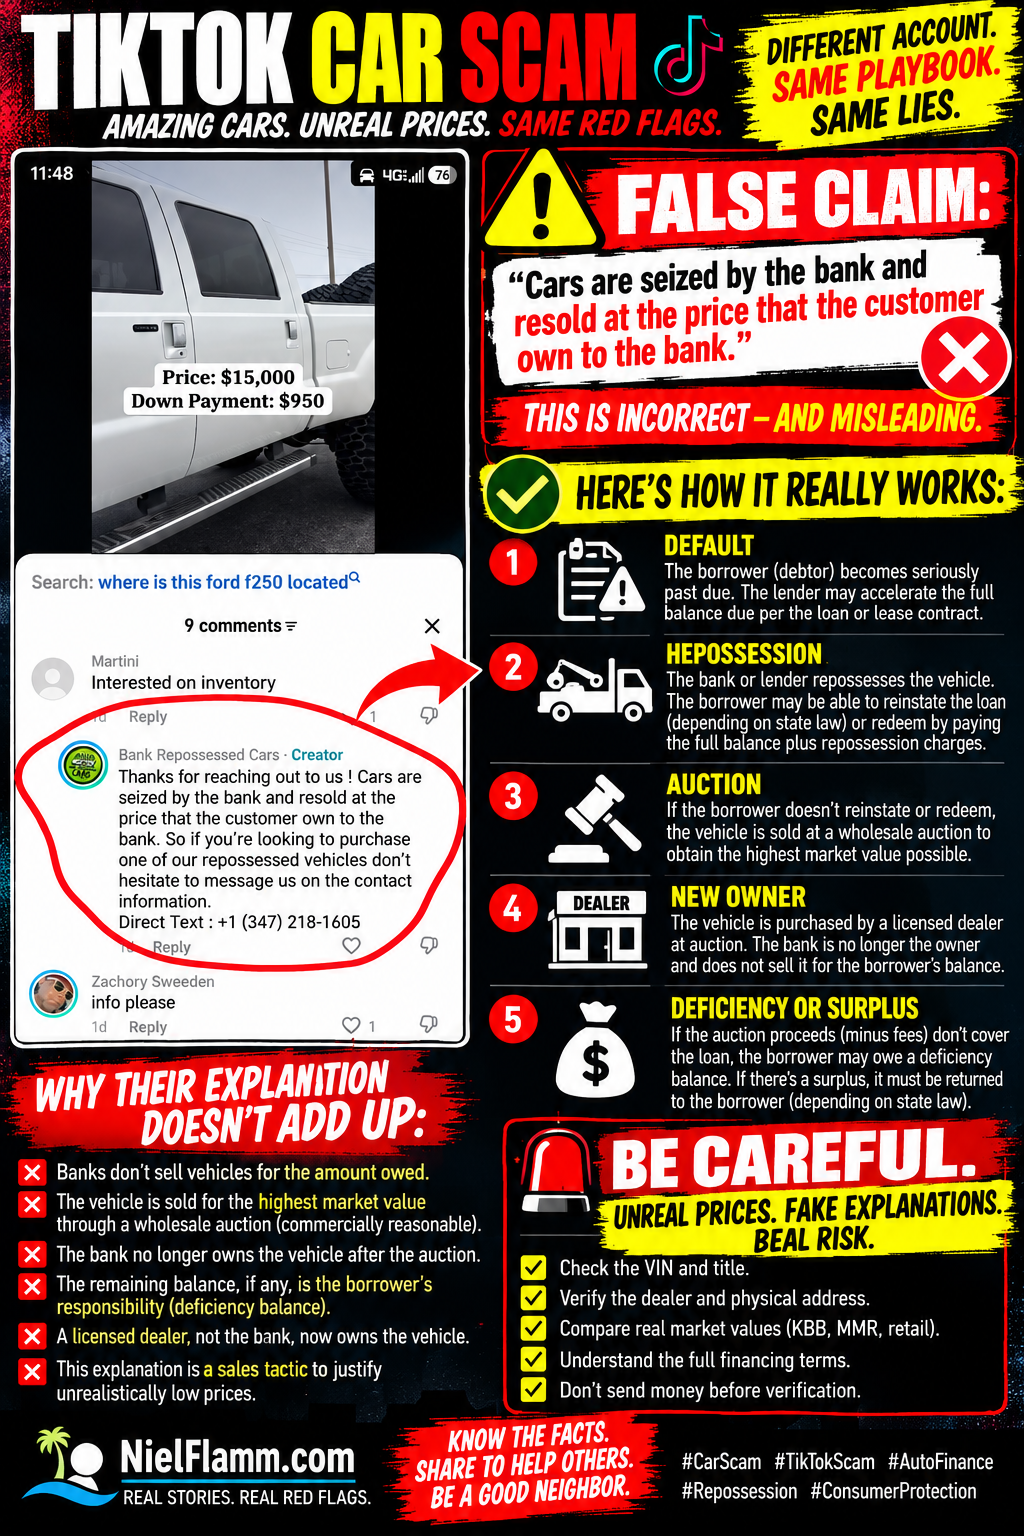
The “Bank Repo” Story Falls Apart: That’s Not How Vehicle Repossession Works
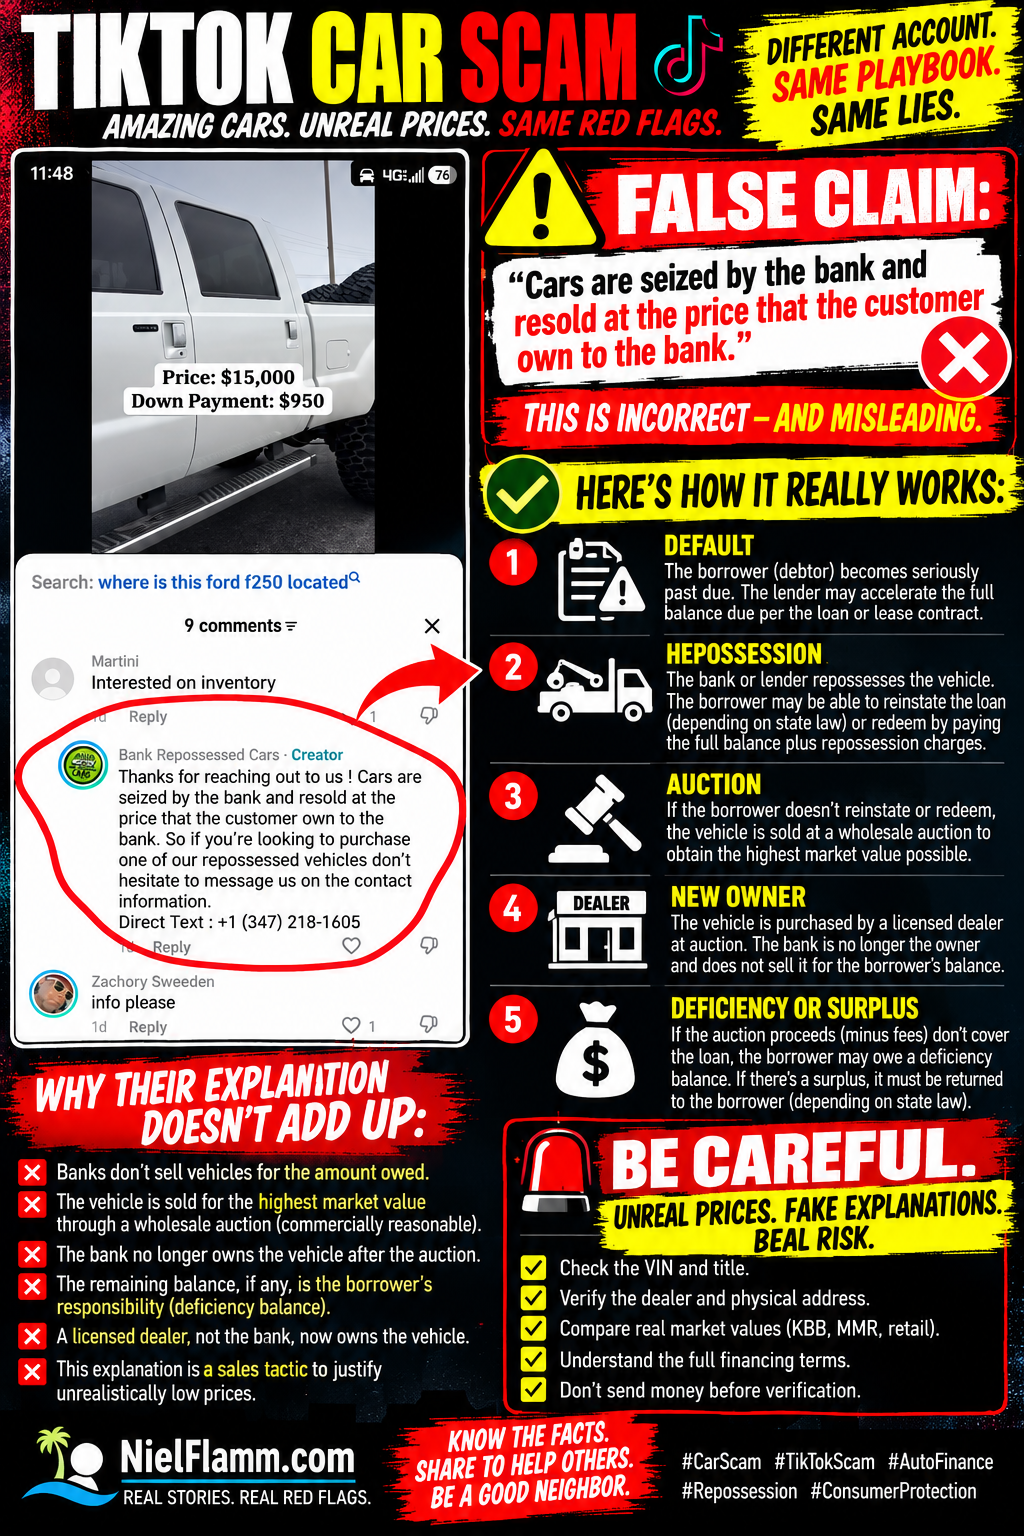
I've been following another TikTok account advertising remarkably inexpensive “bank repossessed” vehicles. This time, I noticed something in the comments that deserves its own post.
The account responded to someone interested in a vehicle with this explanation:
“Cars are seized by the bank and resold at the price that the customer own to the bank.”
In other words, the account appears to be telling potential buyers that banks repossess vehicles and then sell those vehicles for whatever balance the previous customer owed.
That's not an accurate description of the normal repossession and disposition process.
This is an area where I have quite a bit of professional experience.
First, Let's Talk About What Repossession Actually Is
A bank, credit union, captive automotive finance company or other lender doesn't generally repossess a vehicle because it suddenly wants to become a discount used-car dealership.
The vehicle is collateral securing a financial obligation.
When a borrower—often called the debtor—defaults under the retail installment contract or lease, the lender may have the contractual and legal right to repossess the vehicle. Exactly when that can happen and what notices are required depend on the contract and state law. The FTC notes that in many states, a lender may repossess once the borrower defaults, and missed payments are a common form of default. Consumer Advice
State laws vary significantly, so I'm not presenting one procedure as universal across all 50 states.
But the TikTok explanation isn't how the basic economics work.
Reinstatement and Redemption Come Before the Sale
After repossession, the borrower may still have rights.
Depending upon state law and the contract, a borrower may have an opportunity to reinstate the loan by bringing the delinquency current and paying allowable repossession-related expenses.
In other circumstances, the borrower may have the right to redeem the vehicle by paying the full amount required, along with applicable repossession expenses.
The CFPB specifically distinguishes these concepts. Some states permit curing or reinstating a loan after repossession, while redemption generally involves paying the full loan amount plus repossession costs before the vehicle is sold. Consumer Financial Protection Bureau
So repossession doesn't automatically mean:
Bank takes car → bank reviews the remaining balance → a random person gets a screaming deal.
There's a process.
Then Comes the Disposition of the Vehicle
If the borrower doesn't reinstate or redeem where those options apply, the lender may dispose of the collateral.
F
In the automotive finance world, repossessed vehicles commonly move through wholesale channels, including dealer auctions. But to be precise, federal guidance notes that a lender can sell a repossessed vehicle through a public or private sale, depending on applicable law and circumstances. Consumer Advice
Under Article 9 of the Uniform Commercial Code, every aspect of a secured creditor's disposition of collateral must be commercially reasonable. A sale may qualify when it's conducted in the usual manner in a recognized market, at the prevailing market price, or in accordance with reasonable commercial practices among dealers in that type of property. Legal Information Institute
That's an extremely important distinction.
The objective isn't:
“Bob owes $5,850, so let's sell Bob's $35,000 car for $5,850.”
The unpaid loan balance and the vehicle's market value are two different numbers.
That's Where the TikTok Explanation Really Falls Apart
Think about the implications of what this account is saying.
Suppose someone financed a $60,000 vehicle.
Years later, the vehicle is still worth $30,000.
But the borrower happens to owe only $6,000 when the vehicle is repossessed.
According to the explanation in this TikTok comment, the bank would essentially resell the vehicle for what the customer owed.
Why would a lender voluntarily turn a $30,000 asset into $6,000?
That's not how a commercially reasonable disposition works.
The vehicle is sold, the proceeds are applied according to the applicable rules, and then the account is reconciled. Under UCC Article 9, reasonable disposition expenses generally come out of the proceeds, followed by satisfaction of the secured obligation and certain other permitted claims. Legal Information Institute
And then we find out whether there's a deficiency or a surplus.
What's a Deficiency Balance?
Here's where my former world comes into play.
Suppose the borrower owes:
$25,000
The vehicle is repossessed and ultimately sells for:
$18,000
There are also allowable repossession, storage, auction or other disposition expenses.
After applying the proceeds, money is still owed.
That's the deficiency balance.
The CFPB defines a deficiency as the difference between the amount remaining on the loan, plus applicable repossession fees, and what the lender receives from selling the vehicle. Depending on state law and whether the lender complied with applicable requirements, the borrower may remain responsible for that balance. Consumer Financial Protection Bureau
The reverse can also happen.
If the disposition produces more money than the debt and allowable expenses, there can be a surplus, which generally must be returned to the debtor. Legal Information Institute
That's another reason the statement in the TikTok comment doesn't make sense.
The balance owed doesn't establish the vehicle's resale price.
How Do I Know This?
This isn't something I learned yesterday from Google.
In a previous professional life, I worked for a captive automotive finance company—the finance subsidiary of a major European import automobile manufacturer.
I held several different roles there.
I started in primary collections, working delinquent retail contracts at different stages and statuses.
I managed an inbound customer-service team.
I helped set up a predictive dialer.
I worked in retail credit, extending credit through franchised dealership partners.
And one of my other roles was in the loss/deficiency area.
That meant dealing with total losses, collecting total-loss and repossession deficiency balances, and handling post-repossession calls after the lender had taken possession of the collateral.
So when I read:
“Cars are seized by the bank and resold at the price that the customer owe to the bank.”
I don't just see questionable grammar.
I see an explanation of automotive finance that doesn't match the process I spent years working with.
There's Another Problem: “Bank Repossessed” Doesn't Explain a Huge Discount
This matters because the account uses the repossession story to explain prices that appear dramatically below normal market values.
If someone tells me:
“It's cheap because it's bank repossessed.”
That's not enough.
Repossession doesn't erase the market value of an automobile.
Neither does the word auction.
Wholesale values are generally lower than retail values—that's how dealers can acquire inventory, recondition it, cover overhead, and hopefully earn a profit.
But wholesale isn't synonymous with whatever the previous borrower owed.
Those are completely different concepts.
That's why I've been comparing these TikTok prices with KBB retail values and, when reliable vehicle-specific information is available, wholesale/MMR-type benchmarks.
And About That $15,000 F-250...
The video containing this comment shows a Ford F-250 advertised at:
Price: $15,000
Down payment: $950
The TikTok search prompt even asks:
“where is this ford f250 located”
Before anybody sends $950, I'd want a lot more information.
What's the year?
Trim?
Engine?
Mileage?
VIN?
Title status?
Accident history?
Physical location?
Dealer's legal business name?
Dealer license number?
Who actually owns the truck?
What are the complete financing terms?
And if this vehicle was supposedly repossessed by a bank, I'd especially like to know how the seller obtained it and why its current price is what it is.
“Because that's what the previous customer owed” isn't a satisfactory explanation.
A Reputable Lender Has Another Obligation: Commercial Reasonableness
This part shouldn't be overlooked.
A lender can't necessarily dump repossessed collateral for an arbitrary amount and then simply hand the enormous difference to the former borrower as a deficiency.
The disposition must meet applicable legal requirements, including the UCC's requirement that it be commercially reasonable. Legal Information Institute
That protects more than the lender.
It matters to the borrower, too.
Imagine owing $30,000 on a vehicle worth $28,000.
If the lender could arbitrarily sell it to somebody for $5,000 and then demand approximately $25,000 from the borrower, that would create an obvious problem.
That's one reason the manner in which repossessed collateral is disposed of matters.
Be Careful When the Explanation Is Part of the Sales Pitch
I want to make an important distinction.
A questionable explanation in a TikTok comment doesn't, by itself, establish every fact about the person or account behind it.
But I can evaluate the statement they published.
And the statement that repossessed cars are simply resold “at the price that the customer owes to the bank” is materially inconsistent with how reputable lenders generally dispose of repossessed vehicles.
That's significant when that very explanation is being offered to people asking about unusually inexpensive automobiles.
It's one more reason I would verify everything independently before sending a deposit.
Don't rely on the seller to explain why the seller's incredible deal is legitimate.
Check the VIN.
Check the title.
Check the dealer.
Check the physical address.
Check the dealer license.
Check the market value.
Check the financing.
And if the explanation of how repossession works doesn't make sense?
Ask more questions—not fewer.
I've actually worked this process from collections through repossession deficiencies.
So this time, the TikTok algorithm wandered directly into my old office.
Have a question about repossessions, deficiency balances, automotive financing, or one of these suspicious social-media car offers? Reach out by DM or email me at niel@nielflamm.com.
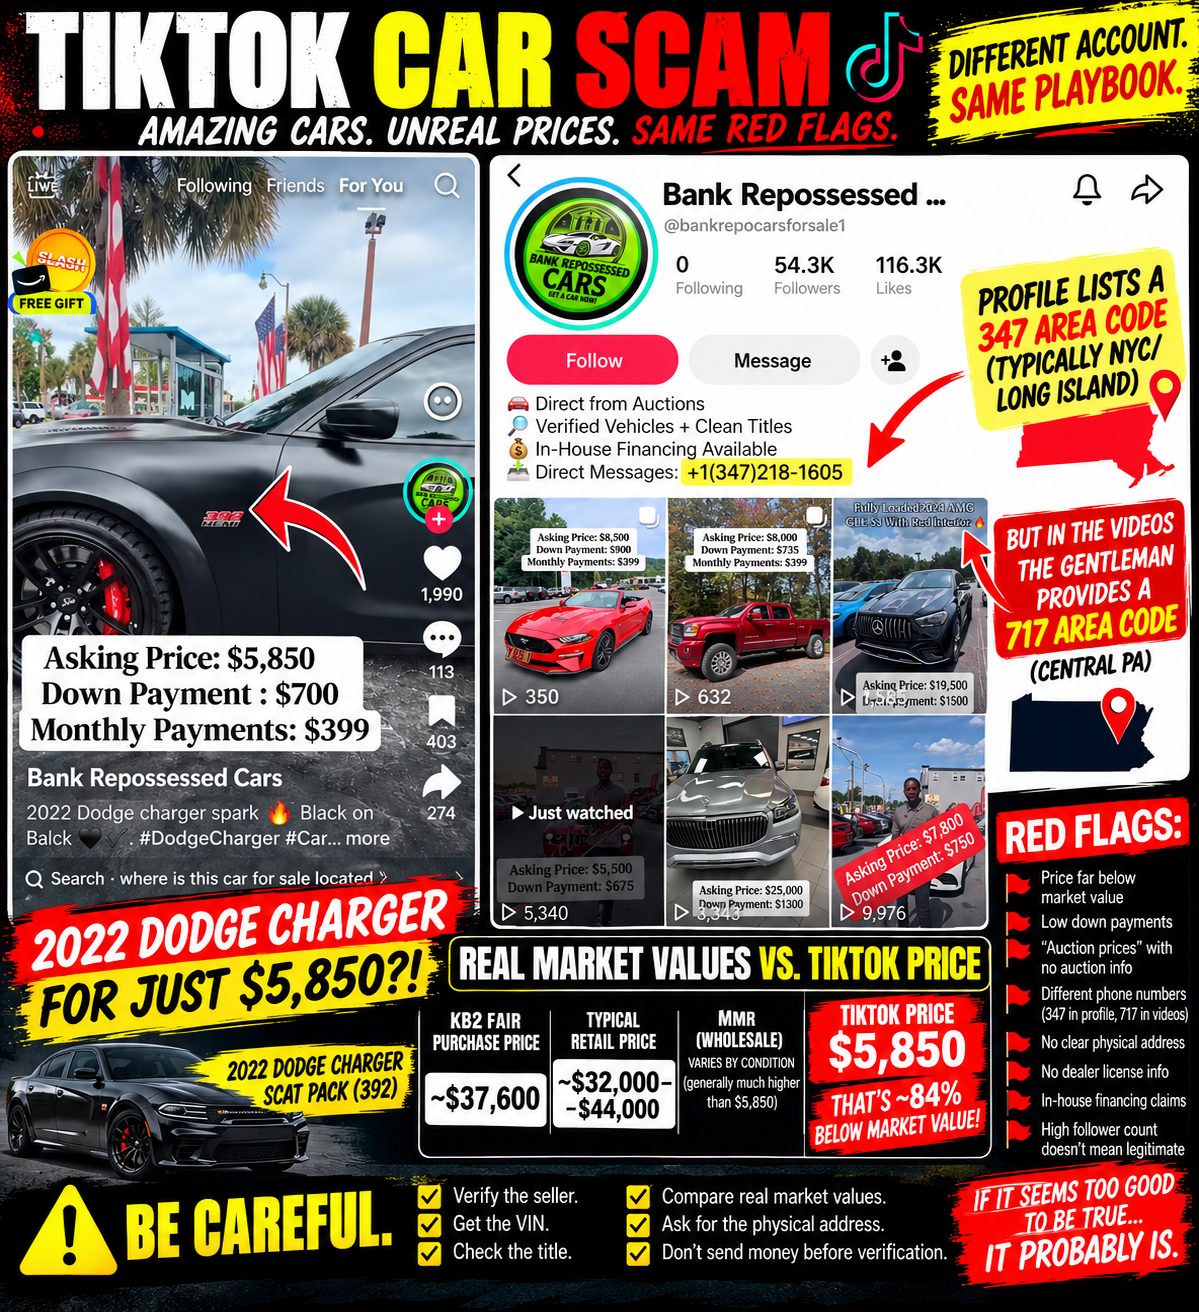
Another “Bank Repossessed” TikTok Car Deal — And the Phone Numbers Don’t Even Match
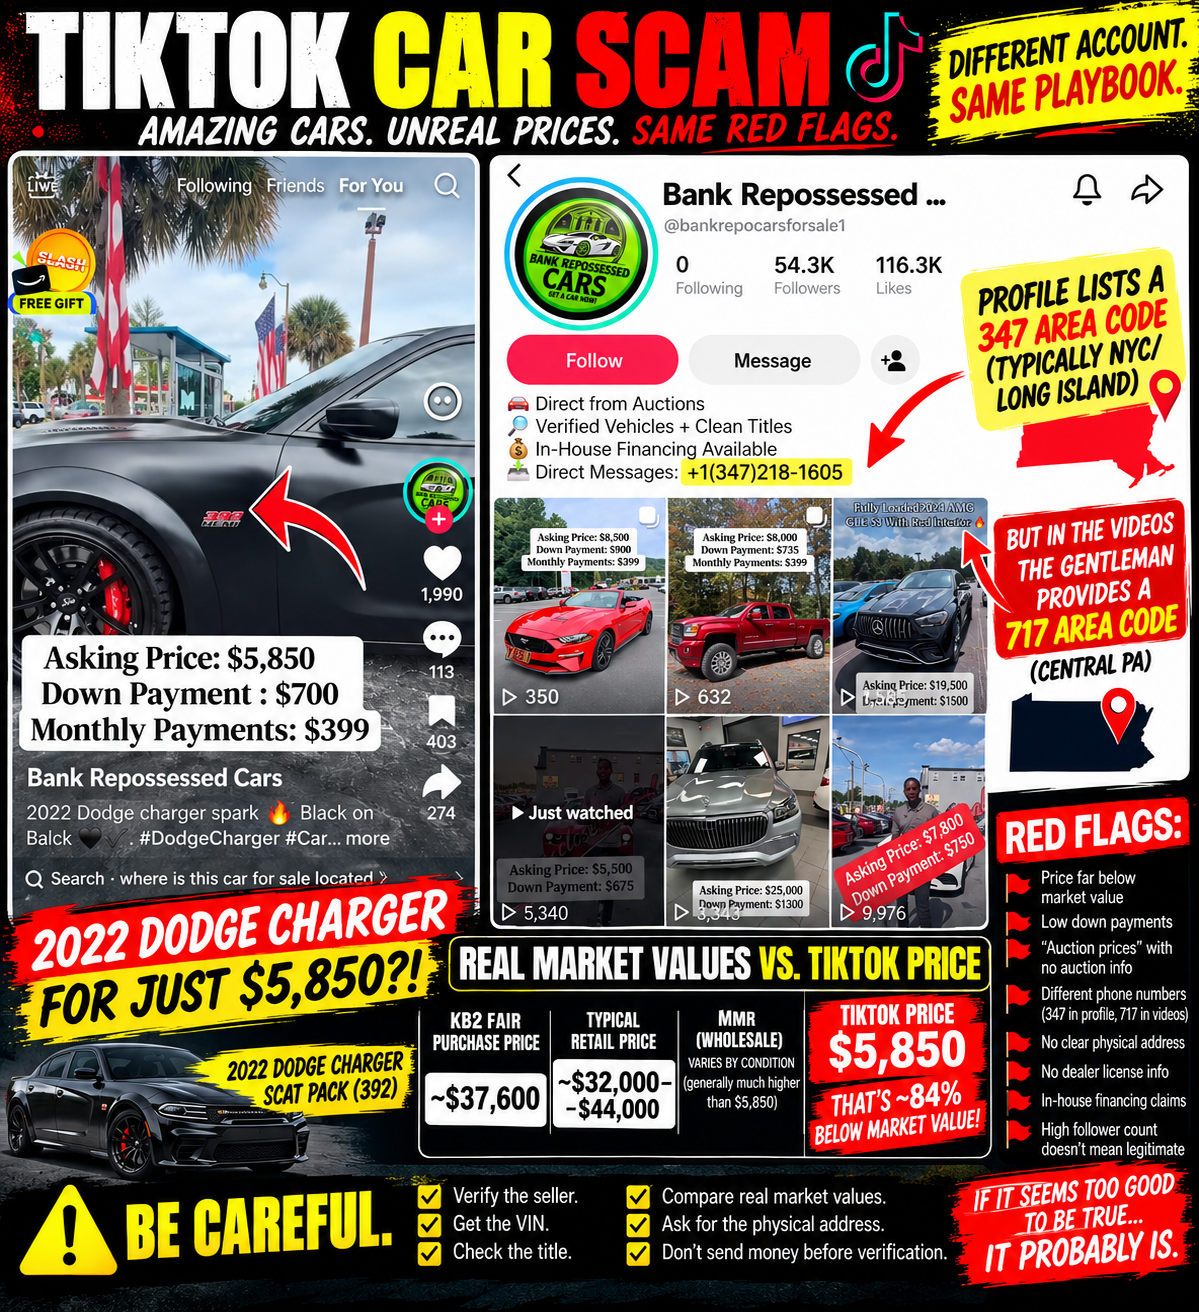
TikTok apparently still thinks I need a ridiculously inexpensive performance car.
The latest account to appear in my feed calls itself “Bank Repossessed Cars” and uses the handle @bankrepocarsforsale1.
At the time of my screenshot, the account had:
54,300 followers.
116,300 likes.
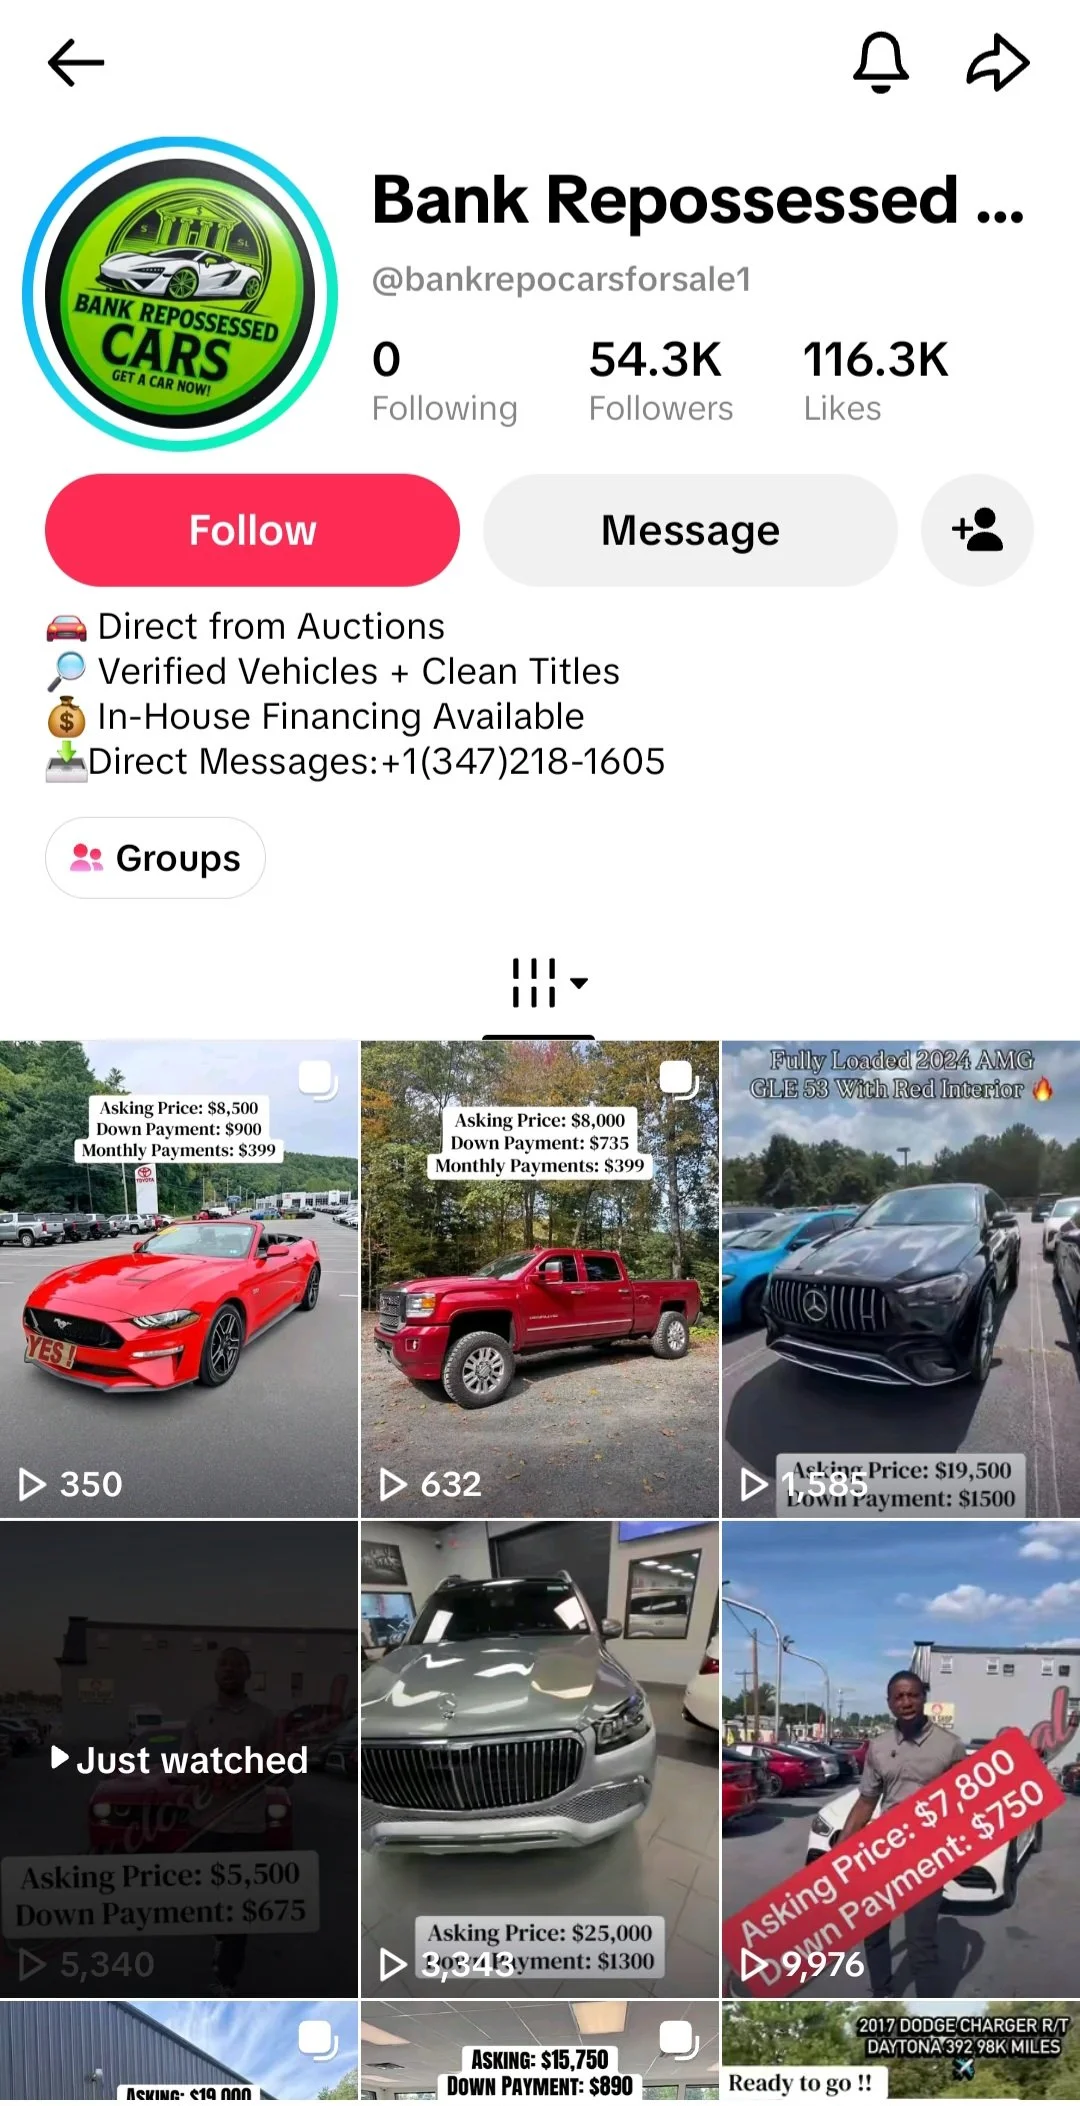
That's substantially larger than several of the questionable car accounts I've written about before.
The profile says:
🚗 Direct from Auctions
🔎 Verified Vehicles + Clean Titles
💰 In-House Financing Available
And then there's a telephone number for direct messages:
+1 (347) 218-1605
Sounds impressive.
Then I started watching the videos.
And once again, I have questions.
🚗 Today's Deal: A 2022 Dodge Charger for $5,850
The video that caught my attention shows what is described as a 2022 Dodge Charger with the following offer:
Asking Price: $5,850
Down Payment: $700
Monthly Payments: $399
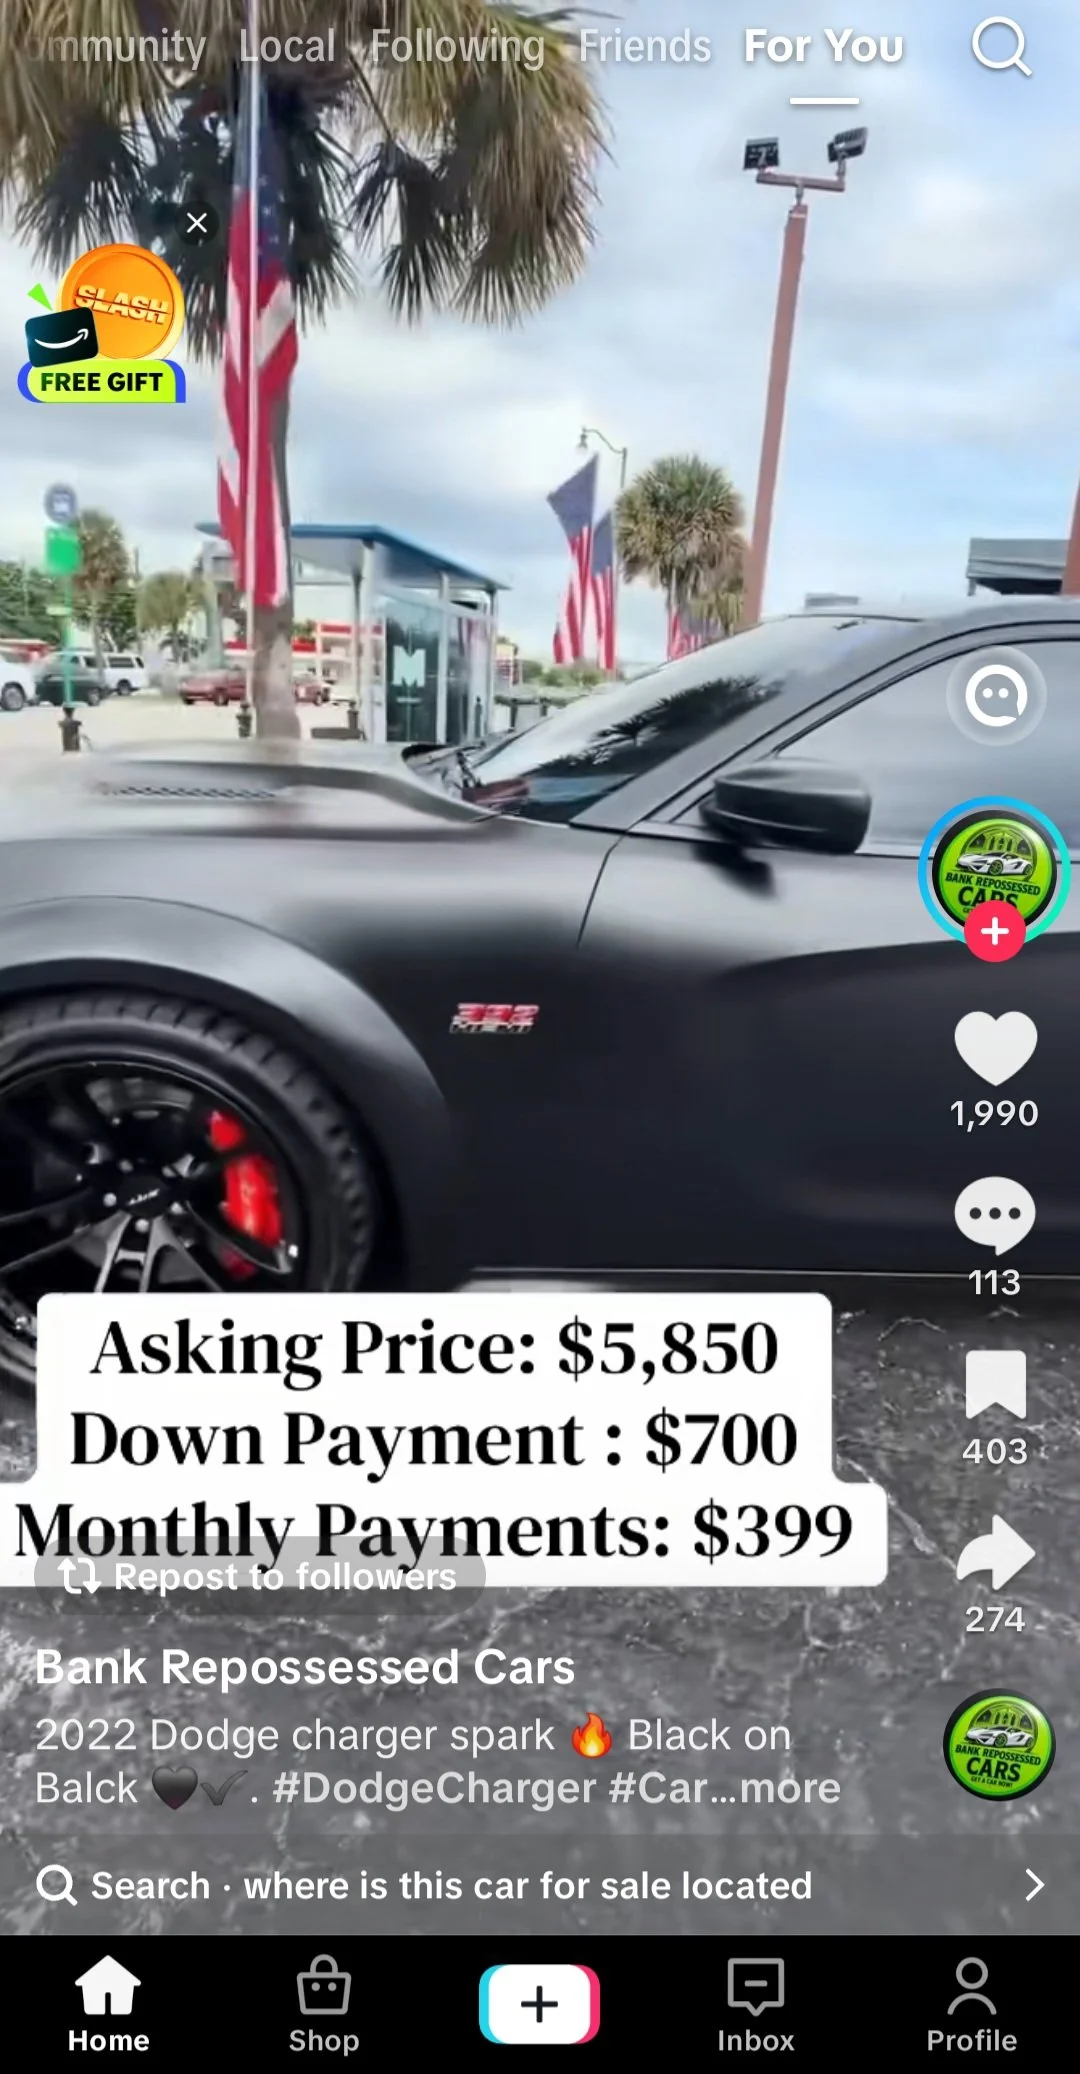
The caption describes it as a “2022 Dodge Charger spark”, although the vehicle shown appears to carry a 392 badge.
If this is actually a 2022 Charger Scat Pack/392, that $5,850 advertised price deserves a very close look.
Why?
Because the market numbers aren't even in the same neighborhood.
💰 Kelley Blue Book Says About $37,000 — Not $5,850
Kelley Blue Book currently puts the national Fair Purchase Price of a 2022 Dodge Charger Scat Pack around $37,600. KBB lists roughly $31,900 trade-in, $34,800 private-party, and $37,600 Fair Purchase Price for a good-condition example, while a Scat Pack Widebody is higher still at about $44,100 Fair Purchase Price. Exact values vary with mileage, condition, options, and location. Kbb.com
Edmunds tells a similar story: its current dealer-retail estimate for a regular 2022 Scat Pack ranges from roughly $32,300 in rough condition to $39,500 in outstanding condition. Edmunds
CARFAX's current listings put 2022 Charger Scat Packs at an average listing price of about $44,347, with its displayed range running roughly $36,747–$52,950. Carfax
TikTok?
$5,850.
That's roughly 84% below KBB's $37,600 Fair Purchase Price.
Maybe there's an explanation.
Fantastic.
I'd like to hear it.
🔨 But What About MMR and “Auction Prices”?
This account specifically promotes the vehicles as coming “Direct from Auctions.”
That's where the Manheim Market Report—or MMR—comes in.
MMR isn't the same thing as KBB retail value. Manheim describes MMR as a wholesale-market valuation based on actual vehicles sold through Manheim, with values that can be adjusted for factors such as odometer reading, selling region, condition grade and even color. Manheim
That's why I'm not going to invent an exact MMR for the Charger in this video.
I don't have its VIN.
I don't have verified mileage.
I don't have its condition report.
I don't have its auction location.
I don't have a current vehicle-specific Manheim report.
Without those things, saying, “The MMR is exactly $XX,XXX,” would be pretending to know something I don't.
But here's what we can compare.
KBB puts the Scat Pack's trade-in value around $31,900. JD Power estimates a trade-in base of around $31,250–$33,250, depending on condition. Those aren't MMR, but they're useful wholesale-side reference points. Kbb.com
So if this really is a clean-title 2022 Scat Pack being sold for $5,850, the question isn't simply:
“Is it cheaper because it came from an auction?”
The question is:
How did someone acquire a vehicle worth tens of thousands of dollars cheaply enough to retail it for $5,850?
“Auction” isn't a magic word that makes vehicle economics disappear.
📞 Then I Noticed the Phone Numbers
Here's where things became even more interesting.
The TikTok profile lists:
+1 (347) 218-1605
The 347 area code is associated with New York City, including the boroughs of Brooklyn, Queens, the Bronx and Staten Island. It's commonly encountered around the broader NYC/Long Island market, although an area code obviously doesn't establish where somebody currently lives or operates a business.
But I watched several of the account's videos.
The gentleman appearing in those videos provides a different telephone number—with a 717 area code.
The 717 area code serves south-central Pennsylvania, including Harrisburg, Lancaster, and York.
Again, people keep phone numbers after moving. Businesses can have multiple telephone numbers. VOIP numbers exist. None of this, by itself, proves anything improper.
But when I'm supposedly dealing with a business selling cars online, it's another question I'd want answered:
Why does the profile give me one phone number while the person in the videos gives me another?
And, more importantly:
What's the actual dealership?
Where is it physically located?
Which number belongs to that dealership?
Those should be remarkably easy questions for a legitimate automobile dealer to answer.
👀 And Look at the Rest of the Inventory
The Charger isn't alone.
The profile shows a Mustang advertised for:
$8,500 — $900 down — $399/month
A GMC pickup:
$8,000 — $735 down — $399/month
A Mercedes-AMG GLE 53 appears to be advertised around:
$19,500 — $1,500 down
Another vehicle:
$5,500 — $500 down
Another:
$7,800 — $750 down
There's even a vehicle shown around $25,000 with $1,300 down.
The scenery changes.
The dealerships and lots visible in the videos appear to change.
The vehicles range from ordinary transportation to expensive luxury and performance models.
Yet the formula remains remarkably familiar.
🚩 “Verified Vehicles + Clean Titles”
Great.
Verified by whom?
That's not sarcasm. That's an actual question I'd ask before buying.
If I'm buying one of these cars, give me the VIN.
Then I can verify the vehicle myself.
If it has a clean title, provide the documentation I need to confirm it independently.
If it came from an auction, tell me which auction.
If you're a licensed dealer, give me the legal business name, physical address, and dealer-license information.
If you're offering in-house financing, give me the written financing terms.
I don't need a green checkmark emoji.
I need documentation.
💳 $700 Down and $399 a Month — What's the Loan?
There's another mathematical problem worth examining.
The Charger is advertised at:
$5,850 purchase price
minus
$700 down
which leaves:
$5,150
If the payments really are $399 per month, $5,150 divided by $399 is only about 12.9 payments, before interest, taxes, fees, or anything else.
So what's the actual term?
What's the APR?
What's the amount financed?
What's the total of payments?
Who's extending the credit?
Are there additional fees?
If the actual vehicle costs $5,850, those should be straightforward questions.
If $5,850 isn't actually the total cash price, then I'd like to know what that number represents.
🚩 54,000 Followers Don't Answer Any of This
This account is bigger than many I've previously documented.
54,300 followers.
That's meaningful social proof.
Someone encountering the account might reasonably think:
They have 54,000 followers. They must be legitimate.
But we've been through this before.
Followers aren't a dealer license.
Likes aren't a title.
Views aren't a VIN.
A green checkmark emoji isn't vehicle verification.
And a real person standing beside a real automobile doesn't establish that the TikTok account displaying the footage owns that automobile or is authorized to sell it under the advertised terms.
🚗 A Real Car Still Doesn't Automatically Make the Offer Real
This has become a recurring theme in this series.
Some of these videos clearly contain actual cars.
Some appear to have been filmed at actual dealerships.
There are real salespeople.
Real parking lots.
Real transporters.
Real dealership signs.
That's persuasive imagery.
But the question isn't:
“Does the car in this video exist?”
It's:
“Does this TikTok account own or have authority to sell this exact vehicle for this exact price under these exact terms?”
Those are very different questions.
I'm not claiming the footage on this account was copied from somewhere else. I haven't established that.
But before sending a $700 deposit, I'd want to establish where the footage came from and whether the seller I'm communicating with is actually connected to that vehicle.
🏡 Be Careful — and Be a Good Neighbor
This is the part that matters most.
Imagine someone who has terrible credit.
Their car just died.
They need transportation Monday morning, or they risk losing their job.
Traditional dealerships have turned them down.
Then TikTok serves them:
2022 Dodge Charger
$5,850
$700 down
$399/month
In-house financing available
That doesn't necessarily look suspicious to someone in that situation.
It looks like hope.
That's why, if somebody you know is considering one of these deals, don't ridicule them.
Help them investigate.
Before sending money, get the VIN. Verify the title. Find the dealership's legal name and physical address independently. Verify the dealer license with the appropriate state regulator. Call a publicly listed number—not simply the number supplied in a TikTok profile. Get the complete financing agreement. Have the vehicle independently inspected. And compare the asking price with retail and realistic wholesale values.
If the seller won't let you do those things before sending a deposit?
Keep your $700.
Different Account. Same Questions.
I'm seeing this pattern often enough that I can practically write the checklist before opening the profile.
Extremely inexpensive desirable car.
Small down payment.
Low monthly payment.
“Direct from auction.”
“Clean title.”
“In-house financing.”
Private messages.
Phone numbers that raise additional questions.
And prices that appear wildly disconnected from ordinary retail values.
Maybe this account has a perfectly reasonable explanation for it all.
I'd be interested in hearing it.
Because based on the screenshot, a $5,850 2022 Charger that appears to be a 392, compared with a KBB Fair Purchase Price around $37,600 for a Scat Pack, is one heck of an explanation. Kbb.com
Until then:
Be careful. Verify everything. And don't let a $700 down payment make a $30,000 question disappear.
Follow the continuing series at NielFlamm.com/blog.