

Day 88: NXDR Ends at $2.23—If Citigroup Sees $2.85, Why Doesn’t the Market?
It's Day 88 of my continuing Nextdoor case study, and today I'm looking at something that should be encouraging to me as a shareholder.
On August 17, 2026, Citigroup analyst Jamesmichael Sherman-Lewis maintained a Neutral rating on Nextdoor Holdings (NYSE: NXDR) but increased his price target from:
$2.30 → $2.85
That's a 23.9% increase in the price target.
Sounds pretty good, right?
Well...
NXDR ended today at approximately $2.23.
And that's where this gets interesting.
Citigroup says $2.85. The Market Says $2.23.
At $2.23, NXDR would need to gain approximately:
27.8%
to reach Citigroup's $2.85 target.
That's a substantial difference between what one major Wall Street analyst believes Nextdoor could be worth and what investors are currently willing to pay.
And on Day 88, that leads me to the obvious question:
If Citigroup sees $2.85 of potential value, why doesn't the market?
Don't Ignore the Word “Neutral”
Citigroup raised the target.
But it didn't upgrade NXDR to Buy.
The rating remained Neutral.
That's important.
Raising a target suggests the analyst sees greater potential value than before.
Maintaining Neutral isn't exactly someone running through Wall Street screaming:
“BUY NEXTDOOR!”
It's more like:
“There's more potential here...but we're still watching.”
As a shareholder, I understand the feeling.
NXDR Is Still Down 16.8% Since August 10
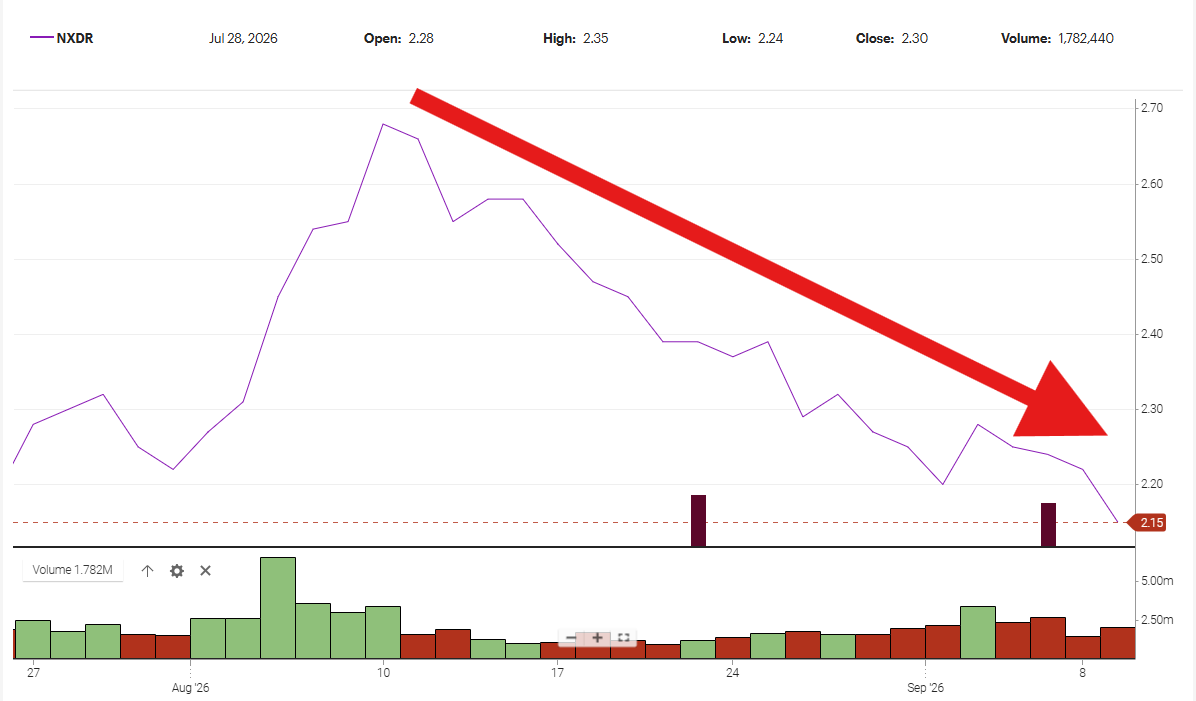
On August 10, NXDR closed around $2.68.
Today it ended at $2.23.
That's:
$0.45 lost per share.
Or approximately:
16.8%
Using roughly 387 million shares as a constant-share-count approximation, that $0.45 decline represents approximately:
$174 million in market capitalization.
That's an improvement from the approximately $205 million decline I calculated when NXDR was trading at $2.15.
But we're still talking about roughly $174 million in market value compared with August 10.
That gets my attention.
Markets fluctuate, share counts change, and one month of stock performance doesn't prove whether a CEO or strategy is succeeding or failing.
But shareholders can certainly ask why the market isn't assigning Nextdoor the value that Citigroup apparently believes is possible.
Where Is the Disconnect?
If analysts believe Nextdoor is worth more...
If management believes the strategy is working...
If advertising is growing...
If the small-business strategy creates value...
If AI-powered search improves the platform...
If verified recommendations differentiate Nextdoor...
Why isn't the market buying the story?
Maybe the market is wrong.
Maybe Citigroup is overly optimistic.
Or maybe investors see Nextdoor's potential but aren't yet convinced leadership can turn that potential into sustained shareholder value.
That's the possibility that interests me.
And What About That $100 Million Buyback?
This makes my recent question about Nextdoor's stock-repurchase program even more interesting.
Nextdoor has a $100 million share-repurchase authorization.
Yet the company repurchased zero shares during Q2 2026.
Put the numbers together:
NXDR closing price: $2.23
Citigroup target: $2.85
Difference: $0.62
Potential upside: ~27.8%
Buyback authorization: $100 million
If Nextdoor's Board and management genuinely believe the company is worth substantially more than $2.23:
At what price does Nextdoor believe Nextdoor is a bargain?
I'm not suggesting management blindly spend $100 million tomorrow.
Capital allocation isn't that simple.
But management already has authorization to repurchase shares.
If leadership believes NXDR is significantly undervalued, buying shares is one way to demonstrate that conviction.
Day 88: Less Storytelling. More Value Creation.
Nirav Tolia has been making the podcast rounds.
Nextdoor has been issuing announcements.
AI.
Verified neighbors.
Local businesses.
Recommendations.
Advertising.
Community.
Trust.
Great.
But ultimately:
Decisions drive value.
Not podcasts.
Not slogans.
Not press releases.
Execution.
Citigroup sees $2.85.
The market ended today at $2.23.
That's a $0.62 gap—or nearly 28% potential upside.
Someone eventually gets proven right.
And I Hope It's Citigroup
That's something that sometimes gets lost in my feedback.
I want Nextdoor to succeed.
I'm a shareholder.
If NXDR goes from $2.23 to $2.85—or considerably higher—I'm certainly not going to complain.
That's precisely why I've spent 88 days questioning leadership, communication, accountability, monetization and shareholder value.
I want Nextdoor to realize the potential people keep telling shareholders exists.
So on Day 88, my question for Nextdoor is simple:
If Citigroup sees $2.85, what does Nextdoor see?
More importantly:
What is leadership doing to close the gap between potential value and realized shareholder value?
Because shareholders can't spend price targets.
We own the stock that's actually trading.
Follow my continuing Nextdoor case study at NielFlamm.com/blog.

Day 83: Nextdoor Has $100 Million for Stock Buybacks. So Why Isn't It Buying?
It's Day 83 of my continuing Nextdoor case study.
Today I want to talk about something different:
NXDR shares.
More specifically, if Nextdoor's leadership believes the company is undervalued and believes strongly in its direction, why isn't it aggressively buying its own stock at these prices?
Before somebody jumps into the comments with a correction, let me make one myself.
Nextdoor DOES have a stock-buyback program.
And it has bought shares.
According to Nextdoor's SEC filings, during the first six months of 2026, the company repurchased and retired approximately 17 million shares for $28.7 million, at an average price of $1.69 per share.
But here's the part I find interesting:
During Q2 2026, Nextdoor repurchased ZERO shares.
And as of June 30, the company still had $100 million available under its current share-repurchase authorization.
So my question isn't:
Why doesn't Nextdoor have a buyback?
My question is:
Why aren't you using it now?
Nextdoor reported $378 million in cash, cash equivalents, and marketable securities at the end of Q2.
The Board has already authorized up to $100 million for share repurchases through June 2028.
Meanwhile, NXDR has recently been trading in the low-$2 range.
If management believes Nextdoor's strategy is working...
If management believes the market is undervaluing the company...
If management believes all these new products, small-business initiatives, AI features, and advertising strategies are going to create substantial future value...
Why wouldn't buying your own stock be an attractive use of at least some of that authorized capital?
Put Your Money Where Your Podcasts Are
I've watched Nirav Tolia make the podcast rounds.
I've heard the vision.
I've read the press releases.
I've seen Nextdoor describe itself as the “essential neighborhood network.”
Okay.
Show me the confidence with capital.
A meaningful stock repurchase at a price management genuinely believes is substantially below intrinsic value can send a very different message than another podcast interview.
It says:
We believe our shares are worth more than this.
And we're willing to put the company's money behind that belief.
Nextdoor itself made almost exactly that argument when it announced its original buyback program in 2022, saying the plan reflected confidence in its strategy and a belief that the market valuation didn't reflect the company's opportunity.
So what does management believe today?
Then There's Stock-Based Compensation
There's another side to this discussion.
Nextdoor reported approximately $14.9 million in stock-based compensation in Q2 2026.
Stock compensation isn't automatically bad. It's extremely common in technology companies and can help align employees and executives with shareholders.
But shareholders should still ask what happens to their ownership percentage as equity compensation is issued over time.
Dilution matters.
If you're issuing equity to employees and executives while the stock struggles, shareholders have every reason to ask whether repurchases are sufficiently offsetting that dilution—and whether compensation is producing the performance shareholders are paying for.
That's particularly important to me when we're discussing executive compensation.
I've repeatedly questioned how Nirav Tolia's compensation aligns with the value being delivered to shareholders.
Here's another way management could demonstrate confidence:
Buy the stock.
Imagine the Message
Forget another Business Wire release for a moment.
Imagine Nextdoor announcing that management believes NXDR is materially undervalued and therefore intends to meaningfully utilize its existing $100 million repurchase authorization.
That's a statement I would notice as a shareholder.
Not because buybacks magically fix a company.
They don't.
Nextdoor itself warns investors that repurchases aren't guaranteed to increase long-term shareholder value and that they reduce cash available for other purposes.
That's fair.
If Nextdoor can invest $1 internally and generate substantially more than $1 in long-term shareholder value, invest the dollar in the business.
But if management believes its own stock represents one of the best values available to the company?
Buy it.
That's capital allocation.
This Is Really a Question About Confidence
Nextdoor's Q2 wasn't all bad.
Revenue increased 15% year over year to $75 million.
Platform Weekly Active Users reached 22.9 million.
Adjusted EBITDA reached approximately $10 million.
The GAAP net loss narrowed dramatically to approximately $2 million, compared with $15 million a year earlier.
And the company finished June with approximately $378 million in cash, cash equivalents, and marketable securities.
Those are real improvements.
So here's what I want to understand:
If management believes those improvements are the beginning of something much bigger, why did Nextdoor repurchase zero shares during Q2?
You already have the authorization.
You have substantial liquidity.
You've bought shares before.
And the stock remains at a valuation that has frustrated shareholders like me.
Day 83
I'm still waiting for the two detailed Insights studies.
I'm still questioning the small-business monetization strategy.
I'm still questioning corporate communication.
I'm still questioning leadership.
And now I'm adding another question for Nirav Tolia and Nextdoor's Board:
You authorized $100 million to buy back NXDR shares.
At these prices, what are you waiting for?
If leadership believes in the direction of Nextdoor, I'd like to see that confidence demonstrated not just through words, podcasts and press releases.
Show shareholders through decisions.
Because ultimately, confidence isn't what management says about the company.
It's what management is willing to do with the company's capital.
Follow my continuing Nextdoor case study at NielFlamm.com/blog.