
Day 90: What If Nextdoor Is Trying to Serve Too Many Customers at Once?
Day 90.
Ninety consecutive days of looking at Nextdoor from different angles.
Yesterday, NXDR closed at $2.27. That's up from the $2.23 close I discussed on Day 88, but I'm not going to spend Day 90 dissecting four cents.
Instead, I want to ask a completely different question:
Who exactly is Nextdoor's customer?
Sounds simple.
I'm not sure it is.
Meet the Nextdoor Family
Think about all the different people Nextdoor is trying to satisfy.
There's the neighbor who wants to know why three police cars just went down the street.
There's the small-business owner who wants customers.
There's the advertiser who wants access to those neighbors.
There's the moderator trying to keep everyone from digitally strangling each other over political signs and dog poop.
There's the researcher or marketer interested in Nextdoor's Insights.
There's the shareholder—hello!—who wants the company to create sustainable value.
And then there's Nextdoor itself, which has to somehow turn this entire neighborhood block party into a profitable business.
That's a lot of people sitting at one table.
And they don't necessarily want the same meal.
The Neighbor Doesn't Wake Up Thinking About Monetization
I doubt many people roll out of bed thinking:
“I hope Nextdoor improves its advertising yield today.”
Neighbors want utility.
What's happening?
Who can fix my air conditioner?
Did somebody find my dog?
Why is the power out?
Is that restaurant any good?
What's being built down the street?
And, naturally:
“Did anyone else hear that boom?”
That's the product from the neighbor's perspective.
But there's a problem.
The neighbor may be the person using the product...
without being the person primarily paying for it.
That's where things get interesting.
The Advertiser Wants Something Completely Different
The advertiser doesn't necessarily care whether Karen and Steve finally resolve their six-day dispute over Steve's garbage cans.
The advertiser wants:
Attention.
Preferably local attention.
And preferably attention from people likely to buy something.
That creates a balancing act.
Nextdoor needs enough people using the platform to make the audience valuable to advertisers.
But if monetizing that audience makes the experience less useful, those people may use Nextdoor less.
And then the audience becomes less valuable.
Welcome to the social-media hamster wheel.
Then Along Comes the Small Business
This is where Nextdoor has another interesting relationship.
The local business can simultaneously be:
Content creator.
Advertiser.
Community participant.
Recommended business.
Potential paying customer.
That's a lot of hats.
Nextdoor wants neighbors to recommend local businesses organically because those recommendations build trust and create useful content.
But Nextdoor also needs to make money from businesses.
That's not inherently wrong.
Nextdoor is a public company, not a neighborhood charity.
The interesting question is where the line sits between:
Helping local businesses participate
and
Monetizing their need to reach neighbors.
That's a strategic question worth watching.
And Then There Are Shareholders
This is the group I belong to.
I don't need Nextdoor to be free of advertising.
I want revenue growth.
I want profitability.
I want innovation.
I want management making intelligent investments.
And yes...
I want NXDR worth more than $2.27.
But here's the catch.
If Nextdoor squeezes too much money out of the platform and damages the neighbor experience, that isn't necessarily good for shareholders long-term.
If Nextdoor focuses exclusively on making neighbors happy but can't build a profitable business around them, that's not particularly helpful either.
The interests are connected.
Maybe Nextdoor Isn't One Product
This is the thought that really interests me on Day 90.
Maybe we're evaluating Nextdoor incorrectly by thinking of it as one product.
It may actually be several products sharing the same neighborhood.
To the neighbor, Nextdoor sells connection and information.
To the local business, it sells visibility and potential customers.
To the advertiser, it sells access and attention.
To researchers and marketers, it offers neighborhood insights.
And to shareholders, management is ultimately selling something else:
The promise that all of those pieces can become a valuable business.
That's a difficult puzzle.
Imagine Trying to Run This Restaurant
Imagine opening a restaurant where one customer wants steak.
Another wants vegan.
Another wants breakfast.
Another wants cocktails.
Another wants everything free.
And there's a shareholder standing near the kitchen asking why the margins aren't better.
Hi. I'm the guy near the kitchen.
Meanwhile, the chef is doing podcasts explaining the future of restaurants.
At some point somebody has to decide:
What's our signature dish?
That's what I'm asking about Nextdoor.
What Is the One Thing Nextdoor Must Be Exceptional At?
Not 17 things.
One.
Is Nextdoor primarily:
The place to discover what's happening nearby?
The place to connect with neighbors?
The place to discover trusted local businesses?
A hyperlocal advertising platform?
A neighborhood recommendation engine?
A source of uniquely valuable local data?
Maybe it can eventually be all of those things.
But companies usually become indispensable because they're exceptionally good at something.
Then they expand.
And That Brings Me Back to $2.27
NXDR closed yesterday at $2.27.
Four cents higher than the $2.23 close I discussed earlier this week.
Good.
As a shareholder, I'll happily take the four cents.
But Day 90 isn't about whether the stock moved four cents.
It's about what eventually moves it forty cents, a dollar, or several dollars—and keeps it there.
That requires more than announcements.
It requires a business people understand.
A product neighbors value.
An ecosystem businesses value.
An audience advertisers value.
And a strategy shareholders believe will eventually create sustainable returns.
That's a lot of customers to keep happy.
Day 90: Who Gets the Best Seat at the Table?
So after 90 days, here's today's question:
When the interests of neighbors, businesses, advertisers, and shareholders collide, who comes first?
Because saying everyone comes first sounds wonderful.
Until two of them want completely different things.
That's when corporate strategy stops being a mission statement and becomes a decision.
And those decisions may ultimately tell us far more about Nextdoor's future than whether NXDR closed yesterday at $2.27 or $2.23.
Ninety days down.
And somehow, I still haven't run out of doors to open.
Follow my continuing Nextdoor case study at NielFlamm.com/blog.
Day 89: What If Nextdoor’s Biggest Competitor Isn’t Another App?
For 88 days, I’ve written about Nextdoor from almost every angle imaginable.
Leadership. Communication. Surveys. Detailed data that I’m still waiting for. Moderation. Small businesses. Advertising. Stock price. Executive decisions. AI. Trust. Blocking shareholders. Even the question of whether anybody is actually driving the bus.
So for Day 89, let's go somewhere completely different.
What if Nextdoor's biggest competitive threat isn't Citizen, Facebook, Ring, Reddit, or some new neighborhood app?
What if Nextdoor's biggest competitor is simply…not opening Nextdoor?
Think about that.
The Most Dangerous Competitor Has No Logo
Every technology company watches its competitors.
What features did they launch?
How many users do they have?
What are they charging?
What are people saying about them?
But there's another competitor that doesn't appear on a PowerPoint competitive-analysis slide.
Indifference.
The person who gets a Nextdoor notification and swipes it away.
The business owner who decides it isn't worth figuring out how Nextdoor works.
The neighbor who hasn't deleted the app but hasn't opened it in six months.
The person who once checked Nextdoor every morning and gradually stopped.
They're technically still a potential user.
But Nextdoor has lost something arguably more important than an account:
Nextdoor has lost their attention.
Deleting an App Is Actually a Dramatic Event
Someone deleting Nextdoor can be measured.
Someone quitting publicly can be noticed.
Someone posting:
“I'M DONE WITH NEXTDOOR!”
is actually giving the company valuable information.
They're angry enough to explain why they're leaving.
But what happens when someone doesn't leave?
They just stop caring.
No complaint.
No angry email.
No support ticket.
No dramatic goodbye post.
Nextdoor remains buried somewhere between Candy Crush and an app they downloaded three phones ago.
That's much harder to fix.
Think About Your Own Neighborhood
If something happens on your street, what's your first instinct?
Do you open Nextdoor?
Text a neighbor?
Check Facebook?
Look at Ring?
Search Google?
Check Citizen?
Look out the window?
Walk outside?
Or do you simply wait until somebody tells you what happened?
That's the real competitive battle.
Nextdoor doesn't merely need to convince people that it's better than another social platform.
It needs to become the answer to:
“Where do I go when I want to know what's happening around me?”
That's a much bigger challenge.
This Is Where “Essential” Gets Interesting
Nextdoor has described itself as an essential neighborhood network.
That's a powerful word.
Essential.
Water is essential.
Electricity is essential.
My morning caffeine can occasionally feel essential.
But an essential product isn't something people have to remind themselves to use.
It becomes habitual because it repeatedly provides value.
That's why I think Nextdoor's most important metric may not simply be how many people can use it.
It's whether people feel they need to use it.
And This Isn't Just About Users
The same question applies to businesses.
Imagine you're a plumber.
A landscaper.
A restaurant.
A dog groomer.
A handyman.
With limited time and limited marketing dollars.
They can be spent on Google.
Facebook.
Instagram.
Direct mail.
Local sponsorships.
Search advertising.
Or Nextdoor.
Nextdoor doesn't just compete against those platforms.
It competes against the business owner saying:
“Nah. I'm good.”
That's the competitor without a logo again.
Indifference.
Maybe This Is the Question Nextdoor Should Obsess Over
Instead of:
How do we get another click?
Try:
What would make somebody miss Nextdoor if it disappeared tomorrow?
That's a fascinating question for any company.
If Nextdoor vanished tonight, what would neighbors genuinely lose?
Local recommendations?
Emergency information?
Community discussion?
Business discovery?
Lost-dog alerts?
Someone asking what that helicopter is doing?
The annual neighborhood debate about whether fireworks are legal?
And, of course, the timeless classic:
“WHOSE DOG POOPED ON MY LAWN?”
There is genuine value buried inside all of that.
The challenge is making the valuable parts important enough that people tolerate—or better yet, don't encounter—the parts that drive them away.
Day 89: Forget the Competition for a Minute
I've spent a lot of time examining what Nextdoor says.
Today I'm more interested in what users do.
Nextdoor can advertise trust.
Nextdoor can announce AI.
Nextdoor can redesign Business Pages.
Nextdoor can create new advertising products.
Nextdoor can publish Insights reports.
Nextdoor can make podcast appearances.
But none of it matters if the customer eventually responds with the most dangerous sentence in business:
“I don't really use it anymore.”
Anger can be addressed.
Complaints can be investigated.
Products can be improved.
Even a shareholder writing about you for 89 consecutive days is demonstrating engagement.
But indifference?
Indifference doesn't complain.
It just leaves the app sitting unopened.
And maybe that's the Nextdoor problem worth talking about on Day 89.
Not who's criticizing the company.
Not who's blocking whom.
Not even where NXDR closed yesterday.
Who still cares enough to open the door?
Follow my continuing Nextdoor case study at NielFlamm.com/blog.
Day 88: NXDR Ends at $2.23—If Citigroup Sees $2.85, Why Doesn’t the Market?
It's Day 88 of my continuing Nextdoor case study, and today I'm looking at something that should be encouraging to me as a shareholder.
On August 17, 2026, Citigroup analyst Jamesmichael Sherman-Lewis maintained a Neutral rating on Nextdoor Holdings (NYSE: NXDR) but increased his price target from:
$2.30 → $2.85
That's a 23.9% increase in the price target.
Sounds pretty good, right?
Well...
NXDR ended today at approximately $2.23.
And that's where this gets interesting.
Citigroup says $2.85. The Market Says $2.23.
At $2.23, NXDR would need to gain approximately:
27.8%
to reach Citigroup's $2.85 target.
That's a substantial difference between what one major Wall Street analyst believes Nextdoor could be worth and what investors are currently willing to pay.
And on Day 88, that leads me to the obvious question:
If Citigroup sees $2.85 of potential value, why doesn't the market?
Don't Ignore the Word “Neutral”
Citigroup raised the target.
But it didn't upgrade NXDR to Buy.
The rating remained Neutral.
That's important.
Raising a target suggests the analyst sees greater potential value than before.
Maintaining Neutral isn't exactly someone running through Wall Street screaming:
“BUY NEXTDOOR!”
It's more like:
“There's more potential here...but we're still watching.”
As a shareholder, I understand the feeling.
NXDR Is Still Down 16.8% Since August 10
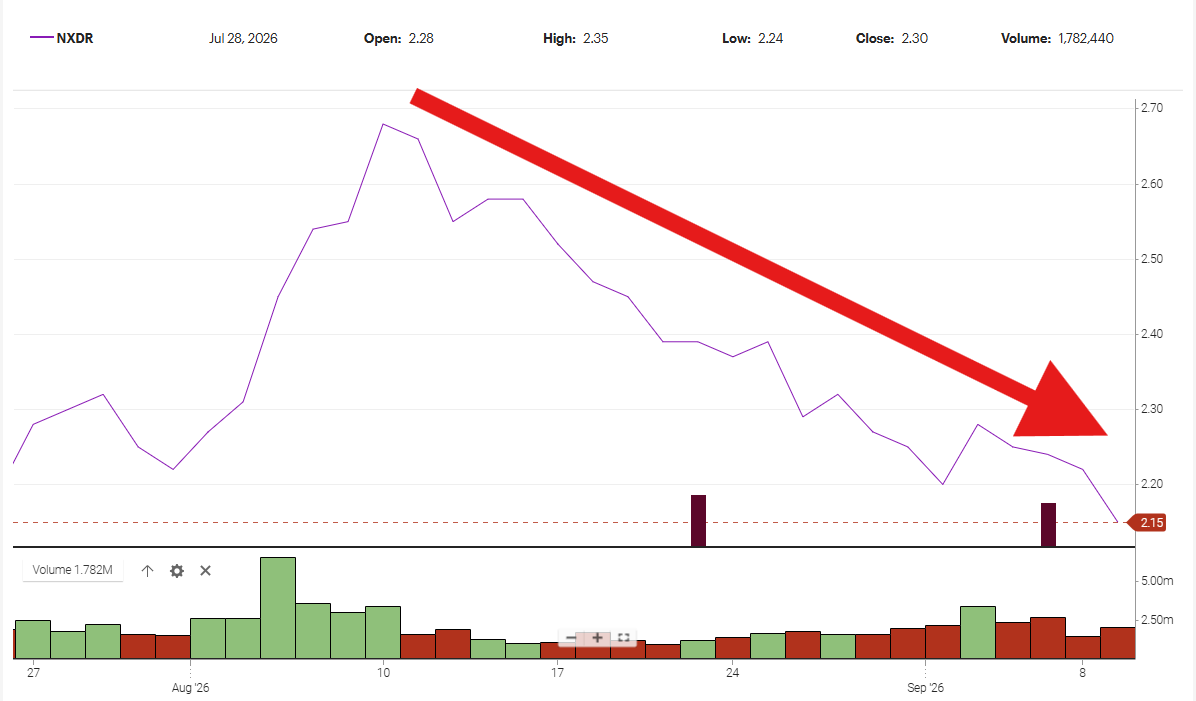
On August 10, NXDR closed around $2.68.
Today it ended at $2.23.
That's:
$0.45 lost per share.
Or approximately:
16.8%
Using roughly 387 million shares as a constant-share-count approximation, that $0.45 decline represents approximately:
$174 million in market capitalization.
That's an improvement from the approximately $205 million decline I calculated when NXDR was trading at $2.15.
But we're still talking about roughly $174 million in market value compared with August 10.
That gets my attention.
Markets fluctuate, share counts change, and one month of stock performance doesn't prove whether a CEO or strategy is succeeding or failing.
But shareholders can certainly ask why the market isn't assigning Nextdoor the value that Citigroup apparently believes is possible.
Where Is the Disconnect?
If analysts believe Nextdoor is worth more...
If management believes the strategy is working...
If advertising is growing...
If the small-business strategy creates value...
If AI-powered search improves the platform...
If verified recommendations differentiate Nextdoor...
Why isn't the market buying the story?
Maybe the market is wrong.
Maybe Citigroup is overly optimistic.
Or maybe investors see Nextdoor's potential but aren't yet convinced leadership can turn that potential into sustained shareholder value.
That's the possibility that interests me.
And What About That $100 Million Buyback?
This makes my recent question about Nextdoor's stock-repurchase program even more interesting.
Nextdoor has a $100 million share-repurchase authorization.
Yet the company repurchased zero shares during Q2 2026.
Put the numbers together:
NXDR closing price: $2.23
Citigroup target: $2.85
Difference: $0.62
Potential upside: ~27.8%
Buyback authorization: $100 million
If Nextdoor's Board and management genuinely believe the company is worth substantially more than $2.23:
At what price does Nextdoor believe Nextdoor is a bargain?
I'm not suggesting management blindly spend $100 million tomorrow.
Capital allocation isn't that simple.
But management already has authorization to repurchase shares.
If leadership believes NXDR is significantly undervalued, buying shares is one way to demonstrate that conviction.
Day 88: Less Storytelling. More Value Creation.
Nirav Tolia has been making the podcast rounds.
Nextdoor has been issuing announcements.
AI.
Verified neighbors.
Local businesses.
Recommendations.
Advertising.
Community.
Trust.
Great.
But ultimately:
Decisions drive value.
Not podcasts.
Not slogans.
Not press releases.
Execution.
Citigroup sees $2.85.
The market ended today at $2.23.
That's a $0.62 gap—or nearly 28% potential upside.
Someone eventually gets proven right.
And I Hope It's Citigroup
That's something that sometimes gets lost in my feedback.
I want Nextdoor to succeed.
I'm a shareholder.
If NXDR goes from $2.23 to $2.85—or considerably higher—I'm certainly not going to complain.
That's precisely why I've spent 88 days questioning leadership, communication, accountability, monetization and shareholder value.
I want Nextdoor to realize the potential people keep telling shareholders exists.
So on Day 88, my question for Nextdoor is simple:
If Citigroup sees $2.85, what does Nextdoor see?
More importantly:
What is leadership doing to close the gap between potential value and realized shareholder value?
Because shareholders can't spend price targets.
We own the stock that's actually trading.
Follow my continuing Nextdoor case study at NielFlamm.com/blog.
Day 87: Is Anybody Driving the Nextdoor Bus? 🚌

It's 10:45 AM EDT on Day 87, and I'm picturing the Nextdoor corporate bus.
The engine is running.
The shareholders are sitting in the back.
The businesses are wondering why there's suddenly a toll booth.
The neighbors are arguing over who parked the bus incorrectly.
And I'm standing in the aisle asking:
“Ummm...who's driving?”
NXDR is down to approximately $2.17 as of this writing.
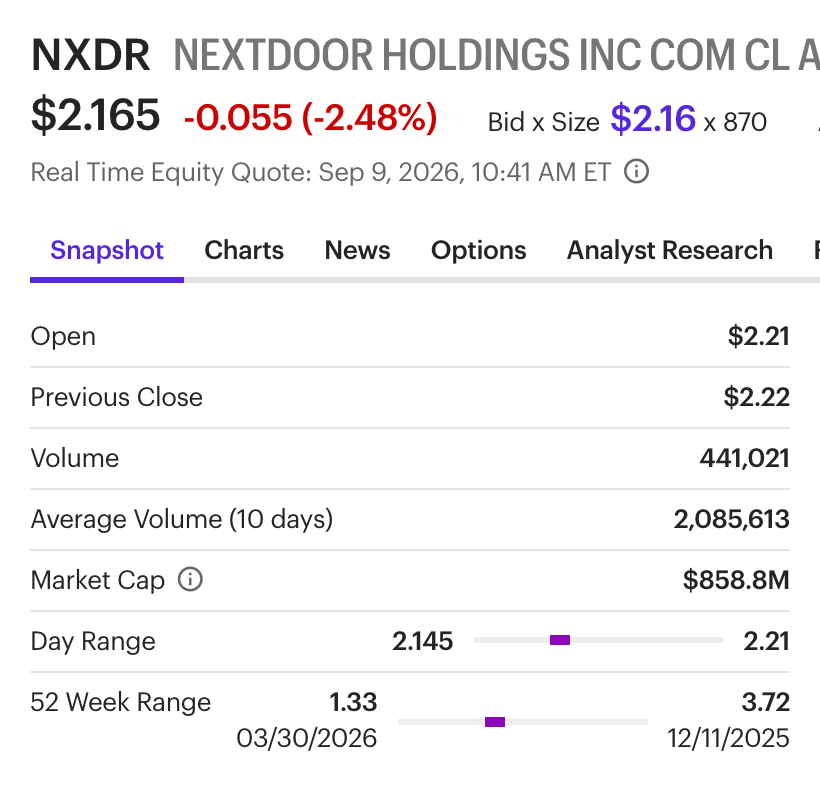
Meanwhile, I've seen no new posts or updates today from Nextdoor or CEO Nirav Tolia.
No answers on my two outstanding studies either.
Maybe everyone is working feverishly behind the scenes.
Maybe Communications is preparing something spectacular.
Maybe Nirav is recording another podcast.
Or maybe the bus is just rolling downhill while everyone debates the seating arrangement.
It's still early.
I'll give Day 87 a chance to unfold.
I may be back later today.
Hopefully someone grabs the wheel before then.
👉 Follow the continuing ride at NielFlamm.com/blog

Day 86: Is Nextdoor Laboring? Or Are We Back to Business as Usual?
Labor Day is over.
It's Day 86 of my continuing Nextdoor case study, and after wondering yesterday whether Nextdoor was taking an extended holiday weekend, I checked again today.
I haven't received any communication regarding the two detailed Insights studies I requested.
And NXDR?
As of this writing, it's hovering around the low $2.20s. Market sources were showing roughly $2.24 late this afternoon after Friday's $2.24 close, so the exact number is moving as I write this.
Hey, at least we're talking pennies now.
Is Nextdoor laboring?
I'm still trying to figure that out.
But something Nirav Tolia posted on X on September 3 caught my attention.
“A 2025 Study Found...”
In the post, Nirav wrote:
“A 2025 study found AI-generated fake reviews are now indistinguishable from real ones...”
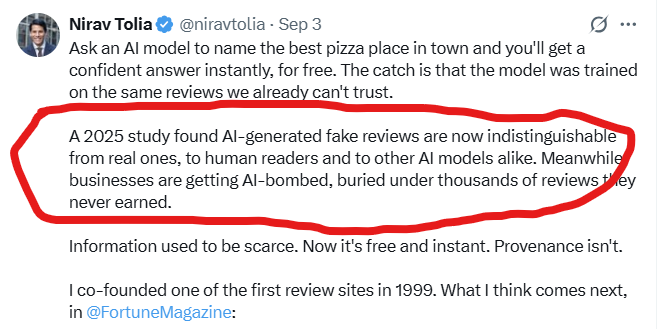
And immediately I thought:
Here we go again.
A study.
Which study?
Who wrote it?
Where was it published?
What was the methodology?
What was the sample size?
What exactly did “indistinguishable” mean?
This probably sounds familiar to anyone who has followed my 86-day adventure in Nextdoor research transparency.
Here's the interesting part: I looked, and there is identifiable research behind Nirav's statement.
In a Fortune piece published the same day, Nirav identified it more specifically as a 2025 study from Nottingham University Business School.
Peer-reviewed 2025 studies examine AI-generated fake reviews, including a Journal of Retailing and Consumer Services study analyzing 714,016 reviews and finding meaningful linguistic differences between AI-generated fake reviews, human-generated fake reviews, and authentic reviews.
So my criticism isn't:
“The study doesn't exist.”
My question is:
Why not cite it in the original post?
If you're going to use research to establish credibility, give readers enough information to evaluate the research themselves.
Study name. Authors. Publication. Link.
Four things.
Done.
Especially when you're the CEO of a company currently promoting the idea that provenance matters.
That's almost too perfect.
Fake Reviews Didn't Arrive With ChatGPT
Another part of this discussion bothers me.
AI didn't invent fake reviews.
AI made them faster, cheaper, and easier to produce at scale.
Humans have been manipulating reputations for a very, very long time.
In fact, the history is pretty entertaining.
1800s: Walt Whitman anonymously published glowing reviews of his own Leaves of Grass. That's essentially the 19th-century version of creating a burner account and giving yourself five stars.
Early 1900s: Newspapers were already dealing with fabricated information, exaggerated claims, and “fakers.” By 1913, the New York World had established a Bureau of Accuracy and Fair Play partly to address complaints and “stamp out fakes and fakers.”
Pre-internet advertising: Businesses used testimonials and endorsements as marketing tools, creating the same fundamental problem we face today: Is this person recommending the product because they genuinely love it—or because somebody benefits from the endorsement?
Early Internet: Message boards, review sites, and eventually e-commerce let businesses and individuals create accounts and manufacture praise—or attack competitors.
Ironically, Nirav himself co-founded Epinions in 1999, one of the early user-generated review platforms. He now acknowledges that the review economy eventually became vulnerable to manipulation.
2010s: Fake-review businesses became an industry. Businesses could purchase positive reviews, competitors could be attacked with negative ones, and reviewers could operate multiple identities.
2020s: Review farms became increasingly sophisticated. Investigators found coordinated reviewers praising unrelated businesses across countries, with identical reviews sometimes appearing under different names.
Today: Generative AI has dramatically changed the economics. Instead of paying humans to crank out hundreds of reviews manually, someone can rapidly generate enormous quantities of convincing text. Research now shows LLMs can produce deceptive reviews with human-level capabilities, even though researchers can still statistically identify some linguistic differences.
Same scam.
Much better machinery.
Which Brings Me Back to Nextdoor
Nextdoor's current pitch is that verified identity and neighborhood accountability can make recommendations more trustworthy.
That's an interesting strategy.
But verification alone doesn't make an opinion truthful.
A real person can exaggerate.
A verified person can have a grudge.
A real neighbor can recommend their friend's company.
A legitimate customer can receive an incentive.
Two verified neighbors can have completely different experiences with the same business.
And, as I've previously documented, I've had my own questions about how robust Nextdoor's verification system actually is.
So “verified” is a trust signal.
It isn't a magical truth serum.
Provenance Matters? I agree.
That's actually what makes Nirav's post so interesting.
His broader argument is essentially:
Where information comes from matters.
I agree.
Completely.
Which is why when the CEO says:
“A 2025 study found...”
I want the provenance.
Name the study.
Name the researchers.
Link to it.
Let readers inspect it.
And that's precisely what I've been asking Nextdoor to provide regarding its own research.
For 86 days.
Nextdoor published Insights findings.
Nextdoor publicly told readers they could request detailed data.
I requested it.
I've emailed.
I've followed up.
I've expanded the distribution.
I sent another request Saturday.
And I'm still waiting for the two detailed studies.
Day 86
Yesterday was Labor Day.
Today I'm asking:
Is Nextdoor laboring?
Because I'm still doing the work.
Waiting for somebody at Nextdoor to answer the questions.
Nirav's post argues that provenance matters.
On that, we agree.
So here's my Day 86 suggestion:
Practice it.
When you cite research, show us the research.
When Nextdoor publishes research, show us the methodology.
When your own blog tells readers they can request detailed data, provide the detailed data—or explain why you won't.
Because whether we're talking about a restaurant review, an AI-generated recommendation, or a corporate Insights report, the principle is the same:
Don't just tell me to trust it. Give me enough information to decide whether to trust it.
Follow the continuing Nextdoor case study at NielFlamm.com/blog.