

When Guilt Feels Real: Recovery, Mental Health and Making Amends
The Down a Hole podcast is back, and Fish and I are tackling a difficult question: What happens when someone feels genuine guilt about events experienced during psychosis—even after realizing those events never actually happened?
In this episode, we discuss a man in recovery who believed he had three daughters and had failed them as a father. The daughters were not real, but his memories and guilt still felt very real to him. Should he make amends to people who never existed? Could doing so provide relief, or would it reinforce the delusion?
There is no simple answer. Our conversation explores the complicated intersection of sobriety, mental health, guilt, accountability, and spirituality. We also discuss why someone facing these questions should not try to work through them alone. A therapist, psychiatrist, sponsor or another qualified and trusted person can help determine the healthiest next step.
Watching this episode may offer a different perspective on recovery and a better understanding of how real another person’s experiences can feel—even when those experiences do not match our reality. It also reminds us that listening without immediately judging or dismissing someone can create the safety needed for an honest conversation.
The full podcast is available at NielFlamm.com/podcast.
While you are there, check out the other podcast episodes available on the site. Each conversation explores different experiences, perspectives, and challenges. Watching them may help viewers feel less alone, understand someone else’s journey or begin a meaningful conversation of their own.
Sometimes the greatest benefit of a podcast is not that it provides every answer. It encourages us to ask better questions—and to listen when someone is brave enough to share a vulnerable part of their life.

The “Bank Repo” Story Falls Apart: That’s Not How Vehicle Repossession Works
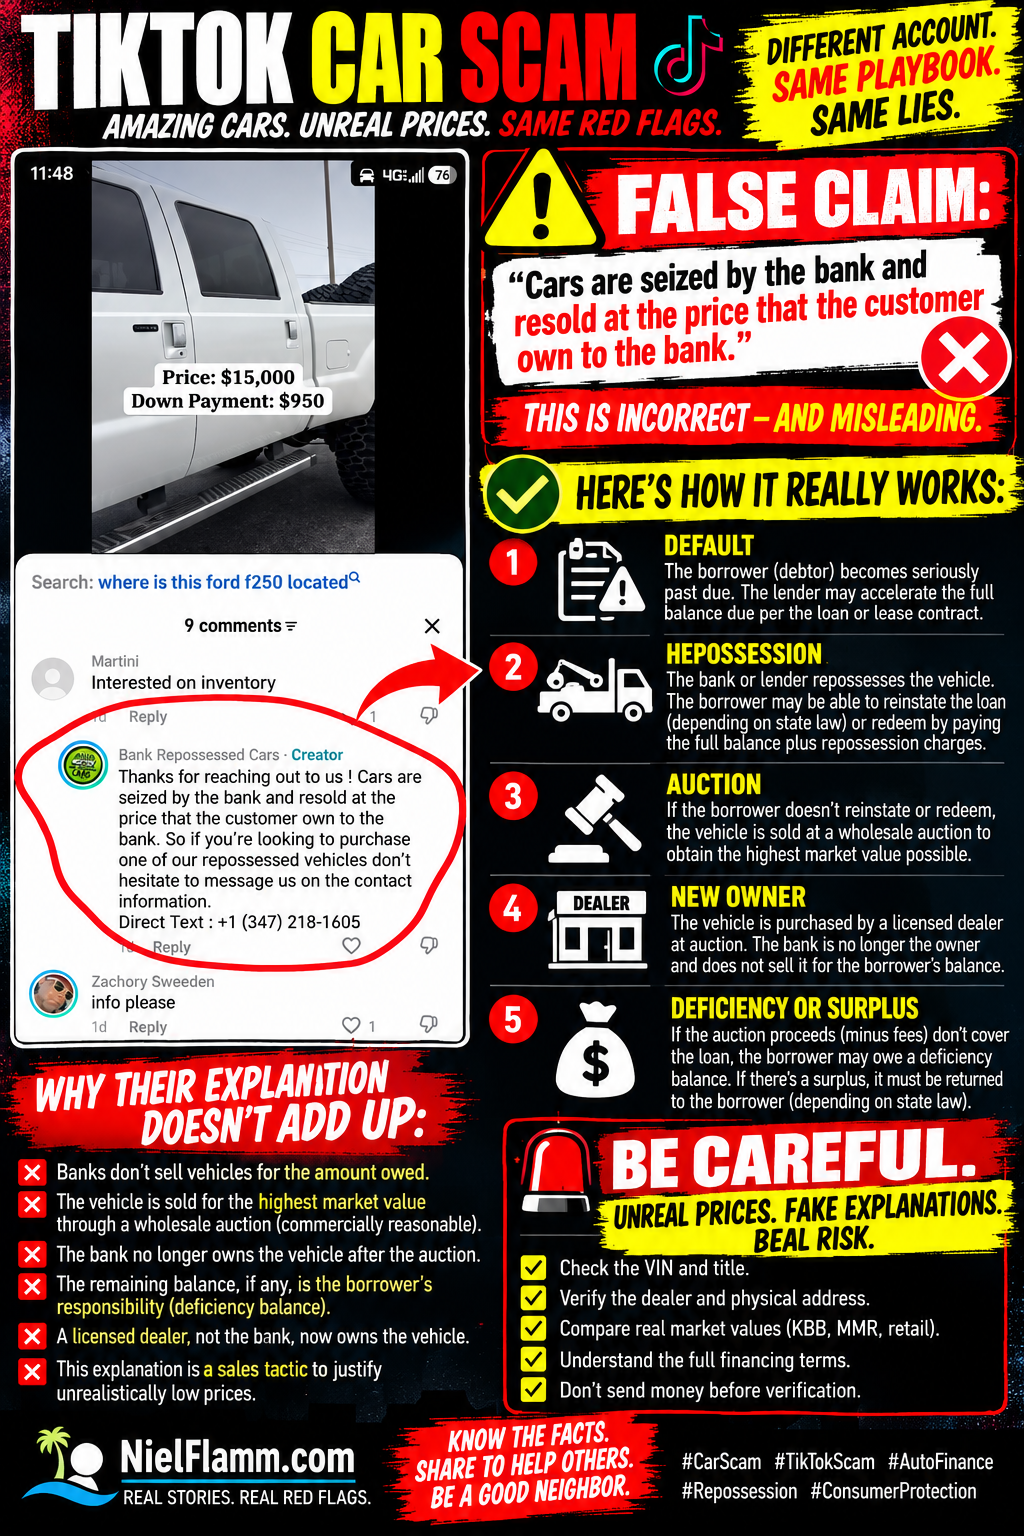
I've been following another TikTok account advertising remarkably inexpensive “bank repossessed” vehicles. This time, I noticed something in the comments that deserves its own post.
The account responded to someone interested in a vehicle with this explanation:
“Cars are seized by the bank and resold at the price that the customer own to the bank.”
In other words, the account appears to be telling potential buyers that banks repossess vehicles and then sell those vehicles for whatever balance the previous customer owed.
That's not an accurate description of the normal repossession and disposition process.
This is an area where I have quite a bit of professional experience.
First, Let's Talk About What Repossession Actually Is
A bank, credit union, captive automotive finance company or other lender doesn't generally repossess a vehicle because it suddenly wants to become a discount used-car dealership.
The vehicle is collateral securing a financial obligation.
When a borrower—often called the debtor—defaults under the retail installment contract or lease, the lender may have the contractual and legal right to repossess the vehicle. Exactly when that can happen and what notices are required depend on the contract and state law. The FTC notes that in many states, a lender may repossess once the borrower defaults, and missed payments are a common form of default. Consumer Advice
State laws vary significantly, so I'm not presenting one procedure as universal across all 50 states.
But the TikTok explanation isn't how the basic economics work.
Reinstatement and Redemption Come Before the Sale
After repossession, the borrower may still have rights.
Depending upon state law and the contract, a borrower may have an opportunity to reinstate the loan by bringing the delinquency current and paying allowable repossession-related expenses.
In other circumstances, the borrower may have the right to redeem the vehicle by paying the full amount required, along with applicable repossession expenses.
The CFPB specifically distinguishes these concepts. Some states permit curing or reinstating a loan after repossession, while redemption generally involves paying the full loan amount plus repossession costs before the vehicle is sold. Consumer Financial Protection Bureau
So repossession doesn't automatically mean:
Bank takes car → bank reviews the remaining balance → a random person gets a screaming deal.
There's a process.
Then Comes the Disposition of the Vehicle
If the borrower doesn't reinstate or redeem where those options apply, the lender may dispose of the collateral.
F
In the automotive finance world, repossessed vehicles commonly move through wholesale channels, including dealer auctions. But to be precise, federal guidance notes that a lender can sell a repossessed vehicle through a public or private sale, depending on applicable law and circumstances. Consumer Advice
Under Article 9 of the Uniform Commercial Code, every aspect of a secured creditor's disposition of collateral must be commercially reasonable. A sale may qualify when it's conducted in the usual manner in a recognized market, at the prevailing market price, or in accordance with reasonable commercial practices among dealers in that type of property. Legal Information Institute
That's an extremely important distinction.
The objective isn't:
“Bob owes $5,850, so let's sell Bob's $35,000 car for $5,850.”
The unpaid loan balance and the vehicle's market value are two different numbers.
That's Where the TikTok Explanation Really Falls Apart
Think about the implications of what this account is saying.
Suppose someone financed a $60,000 vehicle.
Years later, the vehicle is still worth $30,000.
But the borrower happens to owe only $6,000 when the vehicle is repossessed.
According to the explanation in this TikTok comment, the bank would essentially resell the vehicle for what the customer owed.
Why would a lender voluntarily turn a $30,000 asset into $6,000?
That's not how a commercially reasonable disposition works.
The vehicle is sold, the proceeds are applied according to the applicable rules, and then the account is reconciled. Under UCC Article 9, reasonable disposition expenses generally come out of the proceeds, followed by satisfaction of the secured obligation and certain other permitted claims. Legal Information Institute
And then we find out whether there's a deficiency or a surplus.
What's a Deficiency Balance?
Here's where my former world comes into play.
Suppose the borrower owes:
$25,000
The vehicle is repossessed and ultimately sells for:
$18,000
There are also allowable repossession, storage, auction or other disposition expenses.
After applying the proceeds, money is still owed.
That's the deficiency balance.
The CFPB defines a deficiency as the difference between the amount remaining on the loan, plus applicable repossession fees, and what the lender receives from selling the vehicle. Depending on state law and whether the lender complied with applicable requirements, the borrower may remain responsible for that balance. Consumer Financial Protection Bureau
The reverse can also happen.
If the disposition produces more money than the debt and allowable expenses, there can be a surplus, which generally must be returned to the debtor. Legal Information Institute
That's another reason the statement in the TikTok comment doesn't make sense.
The balance owed doesn't establish the vehicle's resale price.
How Do I Know This?
This isn't something I learned yesterday from Google.
In a previous professional life, I worked for a captive automotive finance company—the finance subsidiary of a major European import automobile manufacturer.
I held several different roles there.
I started in primary collections, working delinquent retail contracts at different stages and statuses.
I managed an inbound customer-service team.
I helped set up a predictive dialer.
I worked in retail credit, extending credit through franchised dealership partners.
And one of my other roles was in the loss/deficiency area.
That meant dealing with total losses, collecting total-loss and repossession deficiency balances, and handling post-repossession calls after the lender had taken possession of the collateral.
So when I read:
“Cars are seized by the bank and resold at the price that the customer owe to the bank.”
I don't just see questionable grammar.
I see an explanation of automotive finance that doesn't match the process I spent years working with.
There's Another Problem: “Bank Repossessed” Doesn't Explain a Huge Discount
This matters because the account uses the repossession story to explain prices that appear dramatically below normal market values.
If someone tells me:
“It's cheap because it's bank repossessed.”
That's not enough.
Repossession doesn't erase the market value of an automobile.
Neither does the word auction.
Wholesale values are generally lower than retail values—that's how dealers can acquire inventory, recondition it, cover overhead, and hopefully earn a profit.
But wholesale isn't synonymous with whatever the previous borrower owed.
Those are completely different concepts.
That's why I've been comparing these TikTok prices with KBB retail values and, when reliable vehicle-specific information is available, wholesale/MMR-type benchmarks.
And About That $15,000 F-250...
The video containing this comment shows a Ford F-250 advertised at:
Price: $15,000
Down payment: $950
The TikTok search prompt even asks:
“where is this ford f250 located”
Before anybody sends $950, I'd want a lot more information.
What's the year?
Trim?
Engine?
Mileage?
VIN?
Title status?
Accident history?
Physical location?
Dealer's legal business name?
Dealer license number?
Who actually owns the truck?
What are the complete financing terms?
And if this vehicle was supposedly repossessed by a bank, I'd especially like to know how the seller obtained it and why its current price is what it is.
“Because that's what the previous customer owed” isn't a satisfactory explanation.
A Reputable Lender Has Another Obligation: Commercial Reasonableness
This part shouldn't be overlooked.
A lender can't necessarily dump repossessed collateral for an arbitrary amount and then simply hand the enormous difference to the former borrower as a deficiency.
The disposition must meet applicable legal requirements, including the UCC's requirement that it be commercially reasonable. Legal Information Institute
That protects more than the lender.
It matters to the borrower, too.
Imagine owing $30,000 on a vehicle worth $28,000.
If the lender could arbitrarily sell it to somebody for $5,000 and then demand approximately $25,000 from the borrower, that would create an obvious problem.
That's one reason the manner in which repossessed collateral is disposed of matters.
Be Careful When the Explanation Is Part of the Sales Pitch
I want to make an important distinction.
A questionable explanation in a TikTok comment doesn't, by itself, establish every fact about the person or account behind it.
But I can evaluate the statement they published.
And the statement that repossessed cars are simply resold “at the price that the customer owes to the bank” is materially inconsistent with how reputable lenders generally dispose of repossessed vehicles.
That's significant when that very explanation is being offered to people asking about unusually inexpensive automobiles.
It's one more reason I would verify everything independently before sending a deposit.
Don't rely on the seller to explain why the seller's incredible deal is legitimate.
Check the VIN.
Check the title.
Check the dealer.
Check the physical address.
Check the dealer license.
Check the market value.
Check the financing.
And if the explanation of how repossession works doesn't make sense?
Ask more questions—not fewer.
I've actually worked this process from collections through repossession deficiencies.
So this time, the TikTok algorithm wandered directly into my old office.
Have a question about repossessions, deficiency balances, automotive financing, or one of these suspicious social-media car offers? Reach out by DM or email me at niel@nielflamm.com.

A Thank You to My Readers—and a Free Advertising Opportunity
To everyone visiting NielFlamm.com: thank you for reading, sharing, and enjoying my content! A special thank you to my readers in China, where most of the site’s visits come from.
As a short-term experiment, I’m offering free advertising on NielFlamm.com to business owners everywhere. That’s $0—no cost. A limited number of advertising opportunities are available, and I’m curious to see what impact these ads can have.
Maybe you’d like to reach customers in China, introduce your goods or services to the United States market, or connect with people elsewhere. Wherever your business is based, you’re welcome to participate.
Interested? Email me at niel@nielflamm.com and tell me a little about your business and the audience you’d like to reach.
Let’s connect and explore how I can help your business grow!
Caring for My Mother Without Running the Show
Yesterday, during meditation, I felt a conscious contact with a Power Greater than myself. I felt grounded and right-sized.
Then, before a conversation with another alcoholic, a few questions came up.
Are my motives pure when it comes to my mother? Am I doing God’s will?
Without a doubt, I want my mother to have the best experiences she can with whatever time she has here on Earth before moving on to the next dimension. I want her to have care, comfort, choices, and things to look forward to.
That part is clear to me.
But another question followed: Am I trying to exert my own will? Am I taking control? Is my ego involved?
Apparently, my ego also attended the meditation and hoped nobody would take attendance.
After prayer and discussion, I could acknowledge it: I am trying to run the show.
That is uncomfortable to admit, especially after writing so openly about my frustrations with my father. But if I’m willing to share my anger, I need to be willing to share my self-reflection, too.
I can deeply love my mother and still get caught up in wanting everything done my way. I can have good intentions and become attached to being the person who makes the decisions.
My concern for her is real. So is my responsibility to examine how I act on that concern.
I’ve written about money and control, and how I’ve experienced my father’s responses. Now I need to look at my own desire for control.
Whether my father is trying to run the show, appease his ego, or act from some other motive is not mine to judge. I don’t know everything going on inside him.
I am responsible for my actions.
That gives me plenty to work on without taking on a second job managing his spiritual condition.
For the moment, I’m going to relent. I’m going to loosen my grip on how this has to happen.
My mother has expressed that she wants assisted living. After that, the plan is Thailand with me for the 6+6. As long as her care and those plans are being funded, who manages the finances or makes the payments does not need to be the thing I fight over.
The resources need to be there. The bills need to be paid. My mother’s wishes need to remain part of the decisions about her life.
I can do my part: show up, listen, help with arrangements, ask questions, and follow through on my responsibilities.
Then I need to let God control the result.
I would love to report that I have mastered this and will never mentally grab the steering wheel again. Unfortunately, I know the driver.
This will take practice. More prayer. More honest conversations. More willingness to pause when I start confusing helping with directing every detail.
My boundaries with my father remain.
I have identified what I will accept in that relationship and what I won’t tolerate. Letting go of an outcome doesn’t erase those boundaries. I am still responsible for how I participate, what I agree to, and when I need to step back.
I won’t let fear of people or economic insecurity make those decisions for me. When fear shows up, I can bring it into prayer and talk about it honestly instead of giving it control over my behavior.
Today, I feel clearer about where my work is.
I love my mother. I want to help her have a life she enjoys. I can act with care and hold my boundaries while leaving room for things to happen without my direction.
I’ll do my part—and keep practicing the part where I let go.

Day 101: Our Data Is a Commodity. Why Are We Giving It Away?
Day 101.
Today I want to strip this Nextdoor discussion down to basic economics.
If I have something of value, another party uses it, and that use generates revenue, why shouldn't I share in the value created?
In this case, the commodity is information.
Reviews are information.
Recommendations are information.
Posts, comments, neighborhood observations, business experiences, and local knowledge are information.
Collectively, that's user-generated content.
And when a platform can aggregate, organize, analyze, and monetize that information, those individual contributions can become economically valuable.
We Call It “Content.” But It's Also an Economic Input.
Suppose I recommend a plumber on Nextdoor.
I supplied the experience. I paid to hire the plumber. I evaluated the work. I spent my time writing the recommendation.
Another neighbor reads it.
The plumber potentially gets business.
Nextdoor gets engagement and another piece of local knowledge stored within its platform.
Now multiply that by millions of neighbors and years of participation.
Suddenly, what looks like individual posts becomes something much more interesting:
An asset.
And with AI making it increasingly possible to organize, summarize, and extract useful information from enormous collections of human-created knowledge, that accumulated information may become even more useful.
I'm Not Saying Nextdoor Shouldn't Profit
Quite the opposite.
I'm a shareholder. I want Nextdoor to make money.
Nextdoor built the technology. It operates the platform. It employs people, develops products, sells advertising, and assumes the financial risk of running the business.
Nextdoor should benefit from the value it creates.
My question is:
Why does that automatically mean the neighbor gets zero?
If my contribution becomes part of something commercially valuable, why couldn't there be a model where:
Nextdoor wins.
Shareholders win.
Businesses win.
And the neighbors supplying the information win too.
I'm not suggesting every post deserves a royalty check.
But reviews, recommendations, local knowledge, research participation, and other user-generated information that contributes to commercial value?
Let's have that conversation.
Until Then, Maybe We Stop Supplying the Commodity
That's the idea behind my Neighbor Value-Sharing Petition.
The petition asks Nextdoor users to voluntarily stop providing new routine data, business reviews, recommendations, and other commercial user-generated content until Nextdoor develops a meaningful way for neighbors to participate in the revenue and value their contributions help generate.
It's not about withholding emergency information, safety alerts, missing-person information or other important community communication.
It's about the commodity.
If our information has value, perhaps we should stop giving that value away for free until there's a conversation about sharing it.
Read and sign the petition:
Then share it with another Nextdoor user.
Nextdoor Built the Container. Neighbors Keep Filling It.
A platform without people is software.
A review platform without reviews is an empty database.
A neighborhood network without neighbors sharing neighborhood knowledge isn't much of a neighborhood network.
Nextdoor built the container.
Neighbors keep filling it.
If what's inside that container can be monetized, I think it's reasonable for the people supplying it to ask:
Where's our share?
Until Nextdoor is willing to have that conversation, I'm asking neighbors to consider something incredibly simple:
Don't provide the commodity.
No new routine reviews.
No new business recommendations.
No additional commercial data.
Then let's see how valuable the commodity becomes when the people producing it decide they want to share in its value.
Our data. Our knowledge. Our time. Our value.
👉 Sign the petition:
https://c.org/GkNWmffgg9
👉 More of my continuing Nextdoor case study:
NielFlamm.com/blog