

Day 102: Transparency Shouldn’t Be This Difficult
Day 102.
Earlier today, I posted something on NielFlamm.com/blog that I think connects directly to this entire Nextdoor journey:
My own numbers.
Not just the flattering ones.
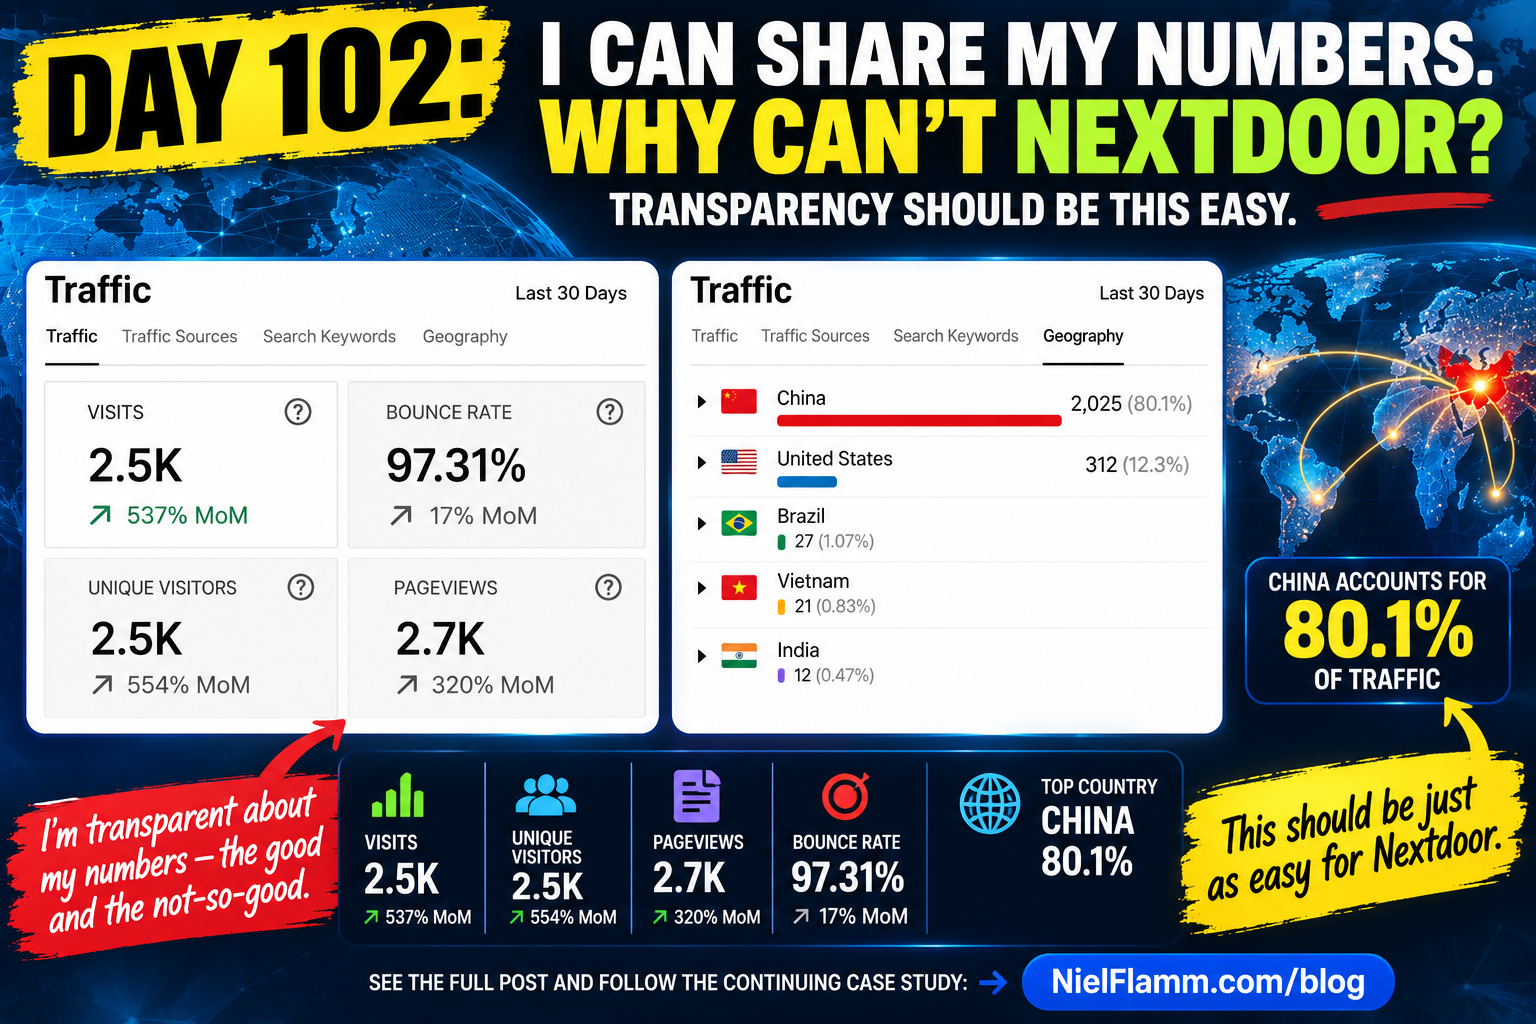
My latest 30-day website metrics show approximately 2,500 visits, 2,500 unique visitors, and 2,700 pageviews. Visits are up 537% month over month, unique visitors are up 554%, and pageviews are up 320%.
Sounds fantastic.
Then there's the 97.31% bounce rate.
Not exactly something I'm putting on a trophy. 😂
And I'm showing that number too.
China? Apparently, I’m Huge in China.
The geography surprised me even more.
Of the traffic shown in my analytics:
China: 2,025 visits — 80.1%
United States: 312 — 12.3%
Brazil: 27 — 1.07%
Vietnam: 21 — 0.83%
India: 12 — 0.47%
Do I completely understand why China represents 80% of the traffic?
Nope.
Could some traffic be automated, routed strangely, or otherwise not represent 2,025 people sitting in China eagerly awaiting my next blog post?
Absolutely.
That's the point.
I don't know everything happening behind the numbers.
So I'm showing them, asking questions and asking readers for feedback.
,
Why Is That So Difficult?
This brings me back to Nextdoor.
I've asked about WAU—Weekly Active Users.
I've asked for the detailed Insights reports that Nextdoor itself told readers were available upon request.
I've asked questions about methodology, engagement, communication, and other metrics.
And after 102 days, what have I received?
Links to information that was already publicly available and responses that, from my perspective, haven't answered the underlying questions.
That's not the transparency I'm talking about.
Transparency isn't:
“Here's the number we want you to see.”
It's also:
“Here's the number. Here's what we know about it. Here's what we don't know. Here's how we calculated it. Ask us questions.”
I Don't Know Everything
That's an easy sentence for me to write.
I don't know why my traffic suddenly jumped.
I don't know exactly why China dominates it.
I don't know how many visitors read every word versus those who accidentally land on the site and disappear.
And I certainly don't know what's going on inside the minds of my readers and viewers.
So I ask.
What are you reading?
What isn't working?
Why did you leave?
What should I change?
What would make you come back?
That's useful feedback.
And if a guy running NielFlamm.com can publish both the pretty numbers and the ugly ones, ask questions about them and admit what he doesn't know, I don't think it's unreasonable to expect a publicly traded neighborhood platform to engage seriously when a shareholder asks questions about its metrics and research.
I'm not asking Nextdoor to know everything.
I'm asking it to explain what it does know.
Day 102.
👉 See the metrics and follow the continuing case study:
NielFlamm.com/blog
I Asked a Question. I Got the Director’s Cut.
Today, while hanging out with Mom at the skilled nursing facility, I was reminded that my preferred conversation speed isn’t necessarily everyone else’s.
Especially with people older than me. I have to say “older than me” because, at this point, I’m old, too. I’m just wearing a Yankees pullover and hoping nobody checks the paperwork.
I didn’t see my friend Donna Woods today. With all the talking she does, I’m beginning to wonder whether she knows Elle Woods from Legally Blonde. I have no evidence of a connection, but I suspect Donna could keep a courtroom occupied.
In her absence, I got better acquainted with Mom’s roommate, Miss Jenny.
I remember the roommate setup from my own days in skilled nursing. A shared room gives you plenty of opportunities to get to know someone. Sometimes more opportunities than you had scheduled.
Miss Jenny asked me a question. I asked her a question.
And that’s how I received the ten-minute answer.
I had already told her I’m a native New Yorker. Just in case she forgot, I was wearing a lightweight New York Yankees quarter-zip pullover. I felt I had provided both verbal notice and supporting documentation.
My preferred answer is fewer than ten words. About five seconds. Enough information to move forward, with perhaps a little time left to blink.
Some of the Southern folks I meet have a more generous approach to conversation. My question gets an answer, a backstory, introductions to supporting characters, and enough local history to qualify for a walking tour.
Meanwhile, my New York brain is standing by the door with its keys out.
This reminded me of a former colleague. I once asked a yes-or-no question about our learning management system, SumTotal.
Before I got the answer, I received a refresher on Kirkpatrick, Maslow’s hierarchy of needs, and the post-training assessments. All of them.
I was waiting for “yes” or “no.” Somehow, I had enrolled in continuing education.
By the time we reached the answer, my most urgent need in Maslow’s hierarchy was for the conversation to end.
It drove me bonkers.
And today, sitting with Mom and listening to Miss Jenny, I recognized that same feeling. I had asked a small question and apparently selected the extended warranty on the response.
I now know more about Miss Jenny than I expected to learn during this visit. Sometimes, the less I know, the better off I am. My brain already has enough open tabs, and several of them are playing music I can’t locate.
Of course, I can hear the irony.
I’ve spent the last few days writing about taking time to listen, visiting people, and making room for conversation.
I still mean every word.
I’m also discovering that I can believe in all of that while occasionally wishing an answer came with a table of contents.
Some days, I have the patience to follow every detour. Other days, I’m silently trying to remember what I asked in the first place. That probably says as much about me as it does about the person talking.
Today, I got to spend time with Mom and learn a little more—okay, considerably more—about Miss Jenny.
Next visit, I’ll wear the Yankees pullover again.
Apparently, it’s a fashion statement, not a speed limit.

From 1,000 to 2,500 Visitors in 18 Days—Thank You!
Eighteen days ago, I published “Thank You for Reading My Stupidity,” after traffic had dropped by almost 50% and then finally returned to its previous level.
At that time, the previous 30-day figures showed approximately:
1,000 visits
1,000 unique visitors
1,300 page views
The newest 30-day report shows:
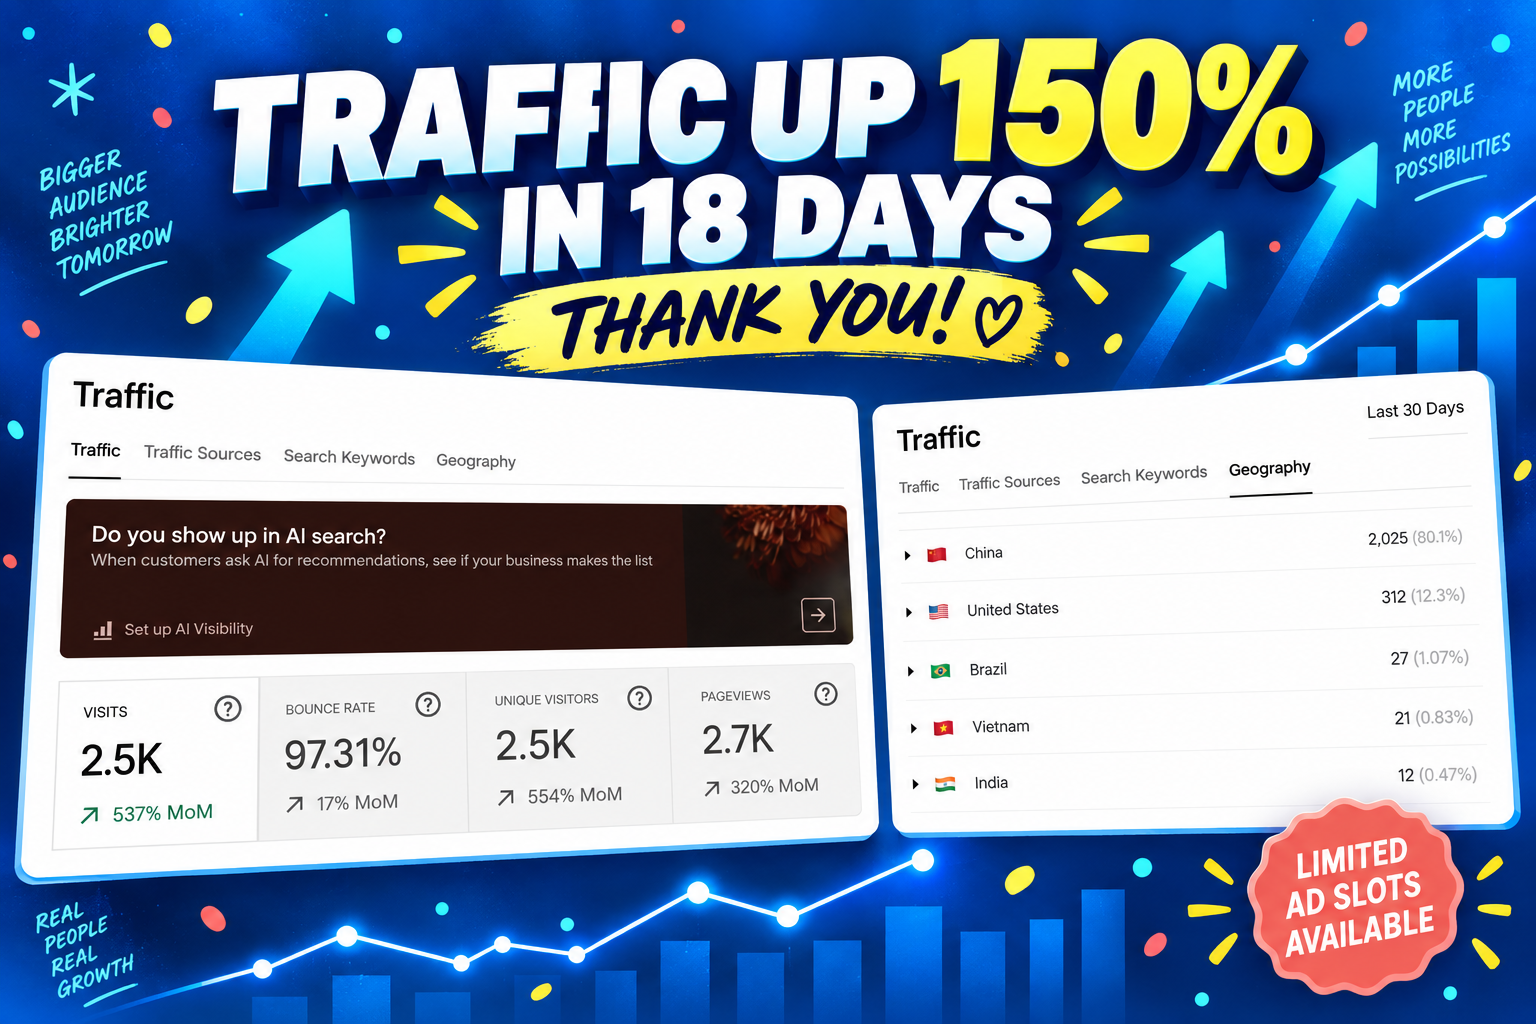
2,500 visits—an increase of approximately 150% since the last post
2,500 unique visitors—also up approximately 150%
2,700 page views—an increase of approximately 108%
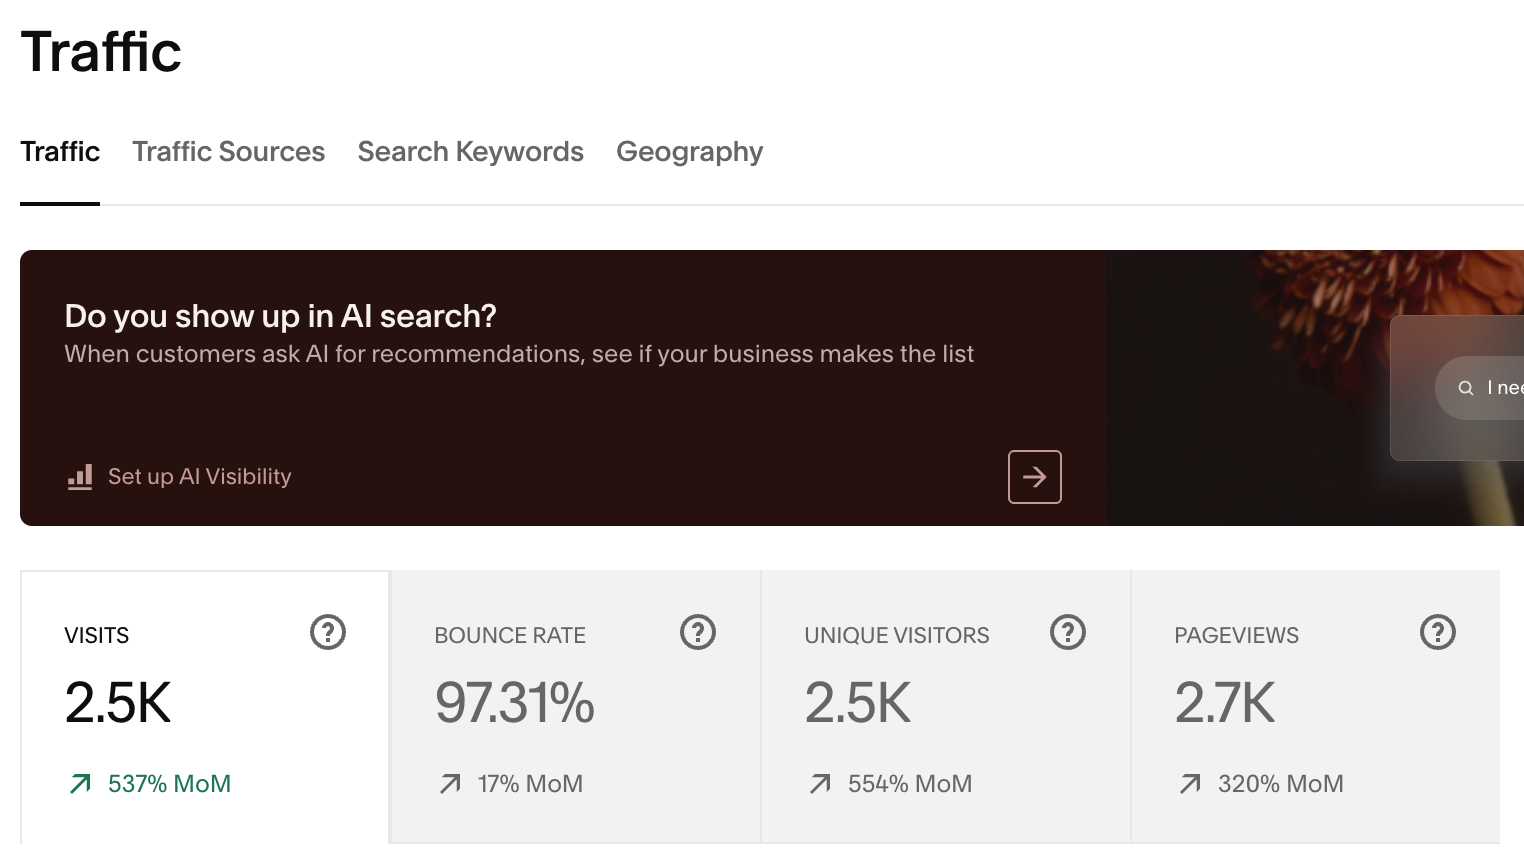
These comparisons are based on rounded figures, but the direction is unmistakable: considerably more people are finding and viewing the site.
I want to thank everyone who has visited, read a post, shared a link, or simply stopped by to see what kind of stupidity I’ve posted lately. I’m genuinely grateful for every visit.
The China Is Still Leading the Way
In the previous post, I thanked the 710 visitors from The China. The latest report shows 2,025 visits from The China—an increase of approximately 185% in just 18 days.
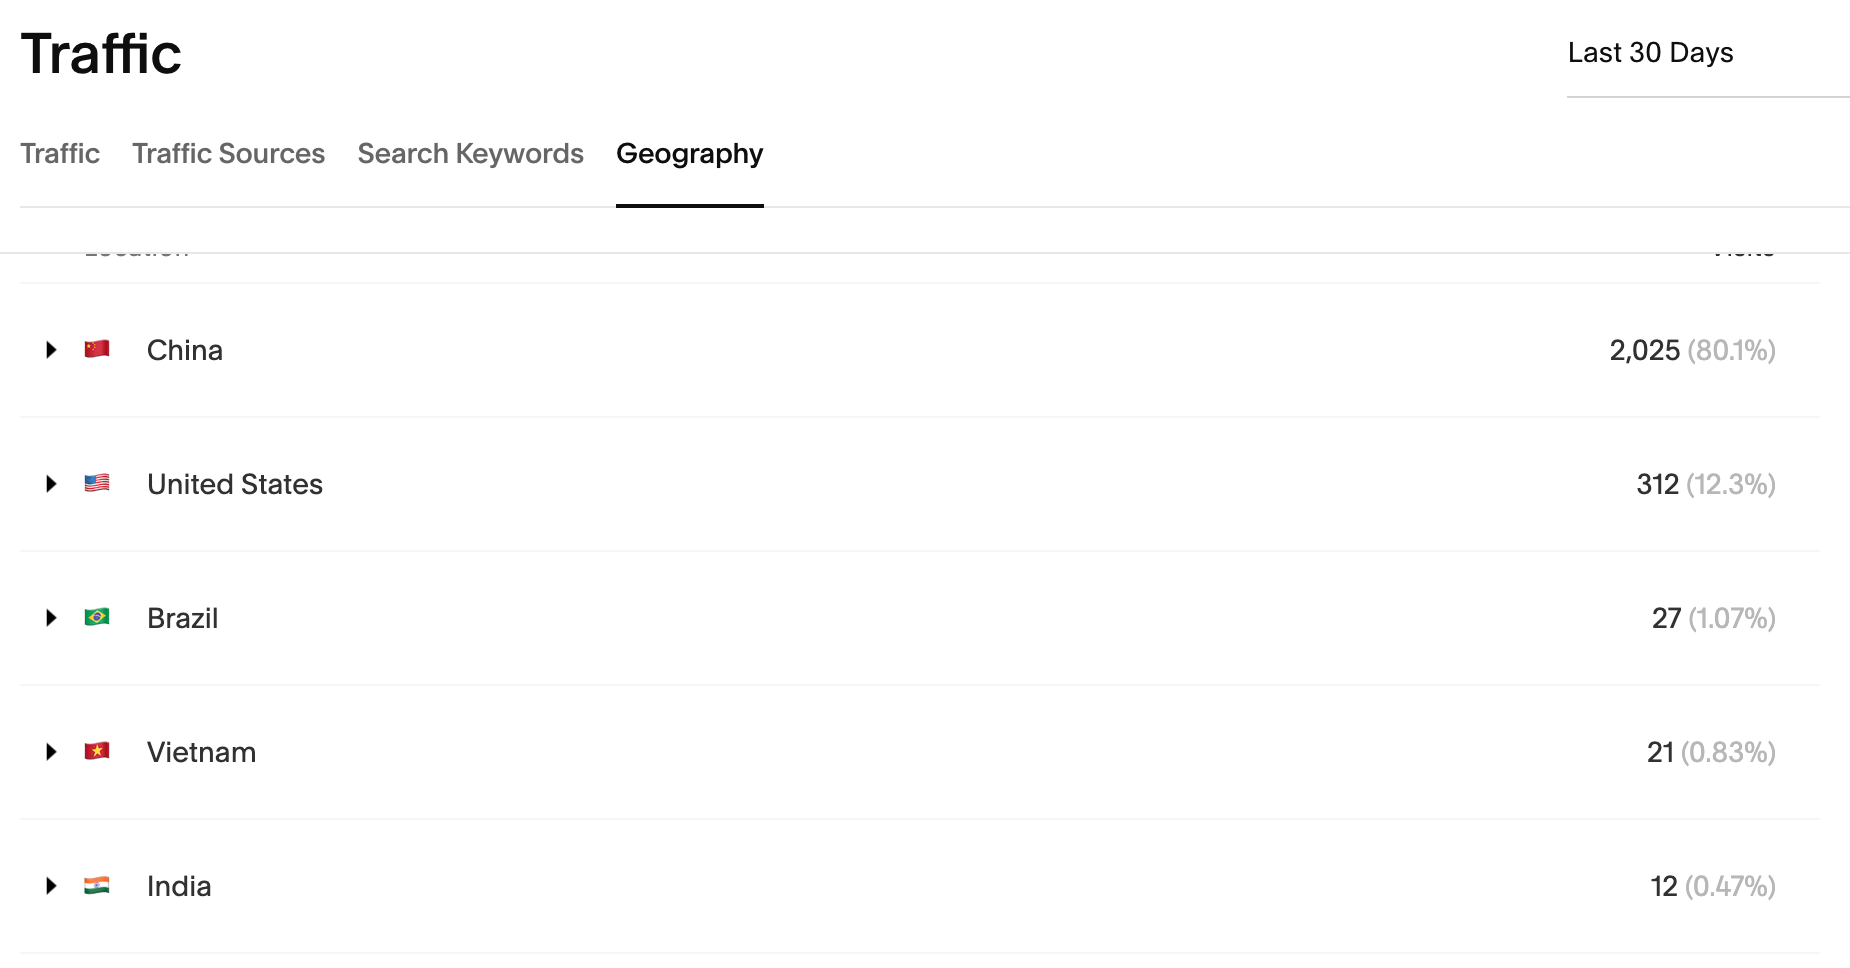
The United States increased from 249 to 312 visits, or approximately 25%. Brazil rose from 24 to 27 visits, and the latest report also includes visitors from Vietnam, India, and other places worldwide.
The bounce rate is currently 97.31%, so many visitors appear to stop by, look at one page, and continue on with their day. Whether you read one page or ten, I appreciate you spending some of your time here.
Limited Advertising Opportunities
With the audience continuing to grow, I’m offering a limited number of advertising slots on the site.
This is an opportunity for businesses, creators, and organizations to reach a growing international audience without being buried among dozens of competing advertisements. Availability will remain intentionally limited so the site stays uncluttered and participating advertisers receive meaningful visibility.
If you’re interested in advertising on the site, please get in touch before the available spaces are filled.
Thank you again to everyone visiting—from The China to the United States and everywhere in between. Seeing visits rise by roughly 150% in only 18 days is unexpected, humbling, and greatly appreciated.
Thank you for continuing to read my stupidity.

When Guilt Feels Real: Recovery, Mental Health and Making Amends
The Down a Hole podcast is back, and Fish and I are tackling a difficult question: What happens when someone feels genuine guilt about events experienced during psychosis—even after realizing those events never actually happened?
In this episode, we discuss a man in recovery who believed he had three daughters and had failed them as a father. The daughters were not real, but his memories and guilt still felt very real to him. Should he make amends to people who never existed? Could doing so provide relief, or would it reinforce the delusion?
There is no simple answer. Our conversation explores the complicated intersection of sobriety, mental health, guilt, accountability, and spirituality. We also discuss why someone facing these questions should not try to work through them alone. A therapist, psychiatrist, sponsor or another qualified and trusted person can help determine the healthiest next step.
Watching this episode may offer a different perspective on recovery and a better understanding of how real another person’s experiences can feel—even when those experiences do not match our reality. It also reminds us that listening without immediately judging or dismissing someone can create the safety needed for an honest conversation.
The full podcast is available at NielFlamm.com/podcast.
While you are there, check out the other podcast episodes available on the site. Each conversation explores different experiences, perspectives, and challenges. Watching them may help viewers feel less alone, understand someone else’s journey or begin a meaningful conversation of their own.
Sometimes the greatest benefit of a podcast is not that it provides every answer. It encourages us to ask better questions—and to listen when someone is brave enough to share a vulnerable part of their life.

The “Bank Repo” Story Falls Apart: That’s Not How Vehicle Repossession Works
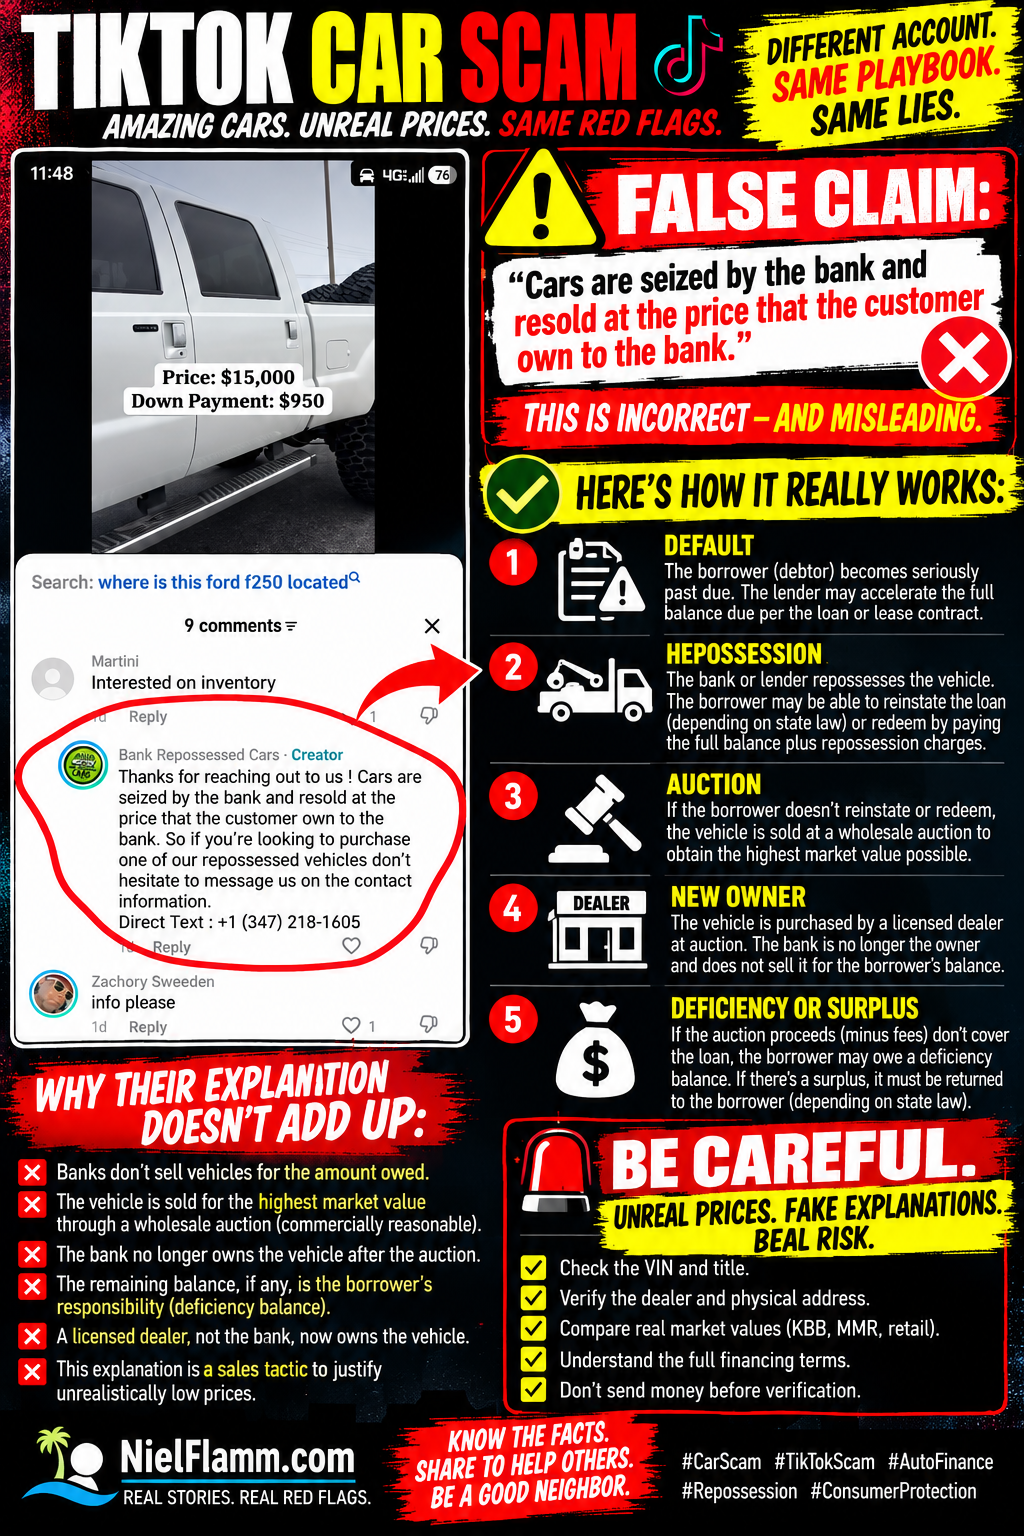
I've been following another TikTok account advertising remarkably inexpensive “bank repossessed” vehicles. This time, I noticed something in the comments that deserves its own post.
The account responded to someone interested in a vehicle with this explanation:
“Cars are seized by the bank and resold at the price that the customer own to the bank.”
In other words, the account appears to be telling potential buyers that banks repossess vehicles and then sell those vehicles for whatever balance the previous customer owed.
That's not an accurate description of the normal repossession and disposition process.
This is an area where I have quite a bit of professional experience.
First, Let's Talk About What Repossession Actually Is
A bank, credit union, captive automotive finance company or other lender doesn't generally repossess a vehicle because it suddenly wants to become a discount used-car dealership.
The vehicle is collateral securing a financial obligation.
When a borrower—often called the debtor—defaults under the retail installment contract or lease, the lender may have the contractual and legal right to repossess the vehicle. Exactly when that can happen and what notices are required depend on the contract and state law. The FTC notes that in many states, a lender may repossess once the borrower defaults, and missed payments are a common form of default. Consumer Advice
State laws vary significantly, so I'm not presenting one procedure as universal across all 50 states.
But the TikTok explanation isn't how the basic economics work.
Reinstatement and Redemption Come Before the Sale
After repossession, the borrower may still have rights.
Depending upon state law and the contract, a borrower may have an opportunity to reinstate the loan by bringing the delinquency current and paying allowable repossession-related expenses.
In other circumstances, the borrower may have the right to redeem the vehicle by paying the full amount required, along with applicable repossession expenses.
The CFPB specifically distinguishes these concepts. Some states permit curing or reinstating a loan after repossession, while redemption generally involves paying the full loan amount plus repossession costs before the vehicle is sold. Consumer Financial Protection Bureau
So repossession doesn't automatically mean:
Bank takes car → bank reviews the remaining balance → a random person gets a screaming deal.
There's a process.
Then Comes the Disposition of the Vehicle
If the borrower doesn't reinstate or redeem where those options apply, the lender may dispose of the collateral.
F
In the automotive finance world, repossessed vehicles commonly move through wholesale channels, including dealer auctions. But to be precise, federal guidance notes that a lender can sell a repossessed vehicle through a public or private sale, depending on applicable law and circumstances. Consumer Advice
Under Article 9 of the Uniform Commercial Code, every aspect of a secured creditor's disposition of collateral must be commercially reasonable. A sale may qualify when it's conducted in the usual manner in a recognized market, at the prevailing market price, or in accordance with reasonable commercial practices among dealers in that type of property. Legal Information Institute
That's an extremely important distinction.
The objective isn't:
“Bob owes $5,850, so let's sell Bob's $35,000 car for $5,850.”
The unpaid loan balance and the vehicle's market value are two different numbers.
That's Where the TikTok Explanation Really Falls Apart
Think about the implications of what this account is saying.
Suppose someone financed a $60,000 vehicle.
Years later, the vehicle is still worth $30,000.
But the borrower happens to owe only $6,000 when the vehicle is repossessed.
According to the explanation in this TikTok comment, the bank would essentially resell the vehicle for what the customer owed.
Why would a lender voluntarily turn a $30,000 asset into $6,000?
That's not how a commercially reasonable disposition works.
The vehicle is sold, the proceeds are applied according to the applicable rules, and then the account is reconciled. Under UCC Article 9, reasonable disposition expenses generally come out of the proceeds, followed by satisfaction of the secured obligation and certain other permitted claims. Legal Information Institute
And then we find out whether there's a deficiency or a surplus.
What's a Deficiency Balance?
Here's where my former world comes into play.
Suppose the borrower owes:
$25,000
The vehicle is repossessed and ultimately sells for:
$18,000
There are also allowable repossession, storage, auction or other disposition expenses.
After applying the proceeds, money is still owed.
That's the deficiency balance.
The CFPB defines a deficiency as the difference between the amount remaining on the loan, plus applicable repossession fees, and what the lender receives from selling the vehicle. Depending on state law and whether the lender complied with applicable requirements, the borrower may remain responsible for that balance. Consumer Financial Protection Bureau
The reverse can also happen.
If the disposition produces more money than the debt and allowable expenses, there can be a surplus, which generally must be returned to the debtor. Legal Information Institute
That's another reason the statement in the TikTok comment doesn't make sense.
The balance owed doesn't establish the vehicle's resale price.
How Do I Know This?
This isn't something I learned yesterday from Google.
In a previous professional life, I worked for a captive automotive finance company—the finance subsidiary of a major European import automobile manufacturer.
I held several different roles there.
I started in primary collections, working delinquent retail contracts at different stages and statuses.
I managed an inbound customer-service team.
I helped set up a predictive dialer.
I worked in retail credit, extending credit through franchised dealership partners.
And one of my other roles was in the loss/deficiency area.
That meant dealing with total losses, collecting total-loss and repossession deficiency balances, and handling post-repossession calls after the lender had taken possession of the collateral.
So when I read:
“Cars are seized by the bank and resold at the price that the customer owe to the bank.”
I don't just see questionable grammar.
I see an explanation of automotive finance that doesn't match the process I spent years working with.
There's Another Problem: “Bank Repossessed” Doesn't Explain a Huge Discount
This matters because the account uses the repossession story to explain prices that appear dramatically below normal market values.
If someone tells me:
“It's cheap because it's bank repossessed.”
That's not enough.
Repossession doesn't erase the market value of an automobile.
Neither does the word auction.
Wholesale values are generally lower than retail values—that's how dealers can acquire inventory, recondition it, cover overhead, and hopefully earn a profit.
But wholesale isn't synonymous with whatever the previous borrower owed.
Those are completely different concepts.
That's why I've been comparing these TikTok prices with KBB retail values and, when reliable vehicle-specific information is available, wholesale/MMR-type benchmarks.
And About That $15,000 F-250...
The video containing this comment shows a Ford F-250 advertised at:
Price: $15,000
Down payment: $950
The TikTok search prompt even asks:
“where is this ford f250 located”
Before anybody sends $950, I'd want a lot more information.
What's the year?
Trim?
Engine?
Mileage?
VIN?
Title status?
Accident history?
Physical location?
Dealer's legal business name?
Dealer license number?
Who actually owns the truck?
What are the complete financing terms?
And if this vehicle was supposedly repossessed by a bank, I'd especially like to know how the seller obtained it and why its current price is what it is.
“Because that's what the previous customer owed” isn't a satisfactory explanation.
A Reputable Lender Has Another Obligation: Commercial Reasonableness
This part shouldn't be overlooked.
A lender can't necessarily dump repossessed collateral for an arbitrary amount and then simply hand the enormous difference to the former borrower as a deficiency.
The disposition must meet applicable legal requirements, including the UCC's requirement that it be commercially reasonable. Legal Information Institute
That protects more than the lender.
It matters to the borrower, too.
Imagine owing $30,000 on a vehicle worth $28,000.
If the lender could arbitrarily sell it to somebody for $5,000 and then demand approximately $25,000 from the borrower, that would create an obvious problem.
That's one reason the manner in which repossessed collateral is disposed of matters.
Be Careful When the Explanation Is Part of the Sales Pitch
I want to make an important distinction.
A questionable explanation in a TikTok comment doesn't, by itself, establish every fact about the person or account behind it.
But I can evaluate the statement they published.
And the statement that repossessed cars are simply resold “at the price that the customer owes to the bank” is materially inconsistent with how reputable lenders generally dispose of repossessed vehicles.
That's significant when that very explanation is being offered to people asking about unusually inexpensive automobiles.
It's one more reason I would verify everything independently before sending a deposit.
Don't rely on the seller to explain why the seller's incredible deal is legitimate.
Check the VIN.
Check the title.
Check the dealer.
Check the physical address.
Check the dealer license.
Check the market value.
Check the financing.
And if the explanation of how repossession works doesn't make sense?
Ask more questions—not fewer.
I've actually worked this process from collections through repossession deficiencies.
So this time, the TikTok algorithm wandered directly into my old office.
Have a question about repossessions, deficiency balances, automotive financing, or one of these suspicious social-media car offers? Reach out by DM or email me at niel@nielflamm.com.